
Passenger Traffic Uptick Means For Shareholders In Aeroports de Paris Stock
- Aeroports de Paris reported group traffic for August 2026 of 37,508,678 passengers, up 0.1%, and half-year traffic of 253,349,315 passengers, up 0.2%.
- The tiny traffic uplift points to broadly steady passenger volumes at Aeroports de Paris, which can matter more for cash flow resilience than headline growth.
- We will now look at how Aeroports de Paris's investment narrative aligns with this marginal passenger traffic increase and what that implies.
Compare Aeroports de Paris' flat traffic trend with airport operators that show stronger momentum by scanning our hand picked list of solid balance sheet and fundamentals (198 results).
Aeroports de Paris Investment Narrative Recap
A shareholder in Aeroports de Paris needs to believe that steady passenger volumes, plus more spending per traveler and broader international exposure, can justify ongoing heavy investment. The latest 0.1% monthly and 0.2% half year traffic moves are marginal, so the short term catalyst still sits in execution on tariff regulation and large capex plans rather than headline demand.
The biggest current risk remains cost creep and leverage at a time when traffic is not doing much work for the income statement. Flat volumes leave less room for error if staff costs, interest expense or taxes move higher, which could pressure cash flow and make the dividend and capex envelope harder to sustain.
Among recent disclosures, the most relevant thread for this traffic release is the focus on earnings quality and growth expectations. Reported profit over the last twelve months includes a sizeable one off gain of €202.0m, and forecast earnings growth of 11.4% a year relies on smoother operations than the traffic numbers alone imply.
For you as a shareholder, the key question is whether Aeroports de Paris can convert broadly stable passenger counts into more resilient cash generation. That means disciplined capex on Paris upgrades, tighter cost control, progress on the upcoming Economic Regulation Agreement, and continued expansion in higher margin non aeronautical activities so small traffic shifts do not dominate the story.
Aeroports de Paris' current consensus story points to revenues of €7.8b and earnings of €861.3m by 2029. That scenario assumes 4.8% yearly revenue growth and an earnings increase of about €264m from €597.0m today.
Uncover why Aeroports de Paris' fair value indicates a 14% potential upside to its current price, which could close sooner than many investors expect.
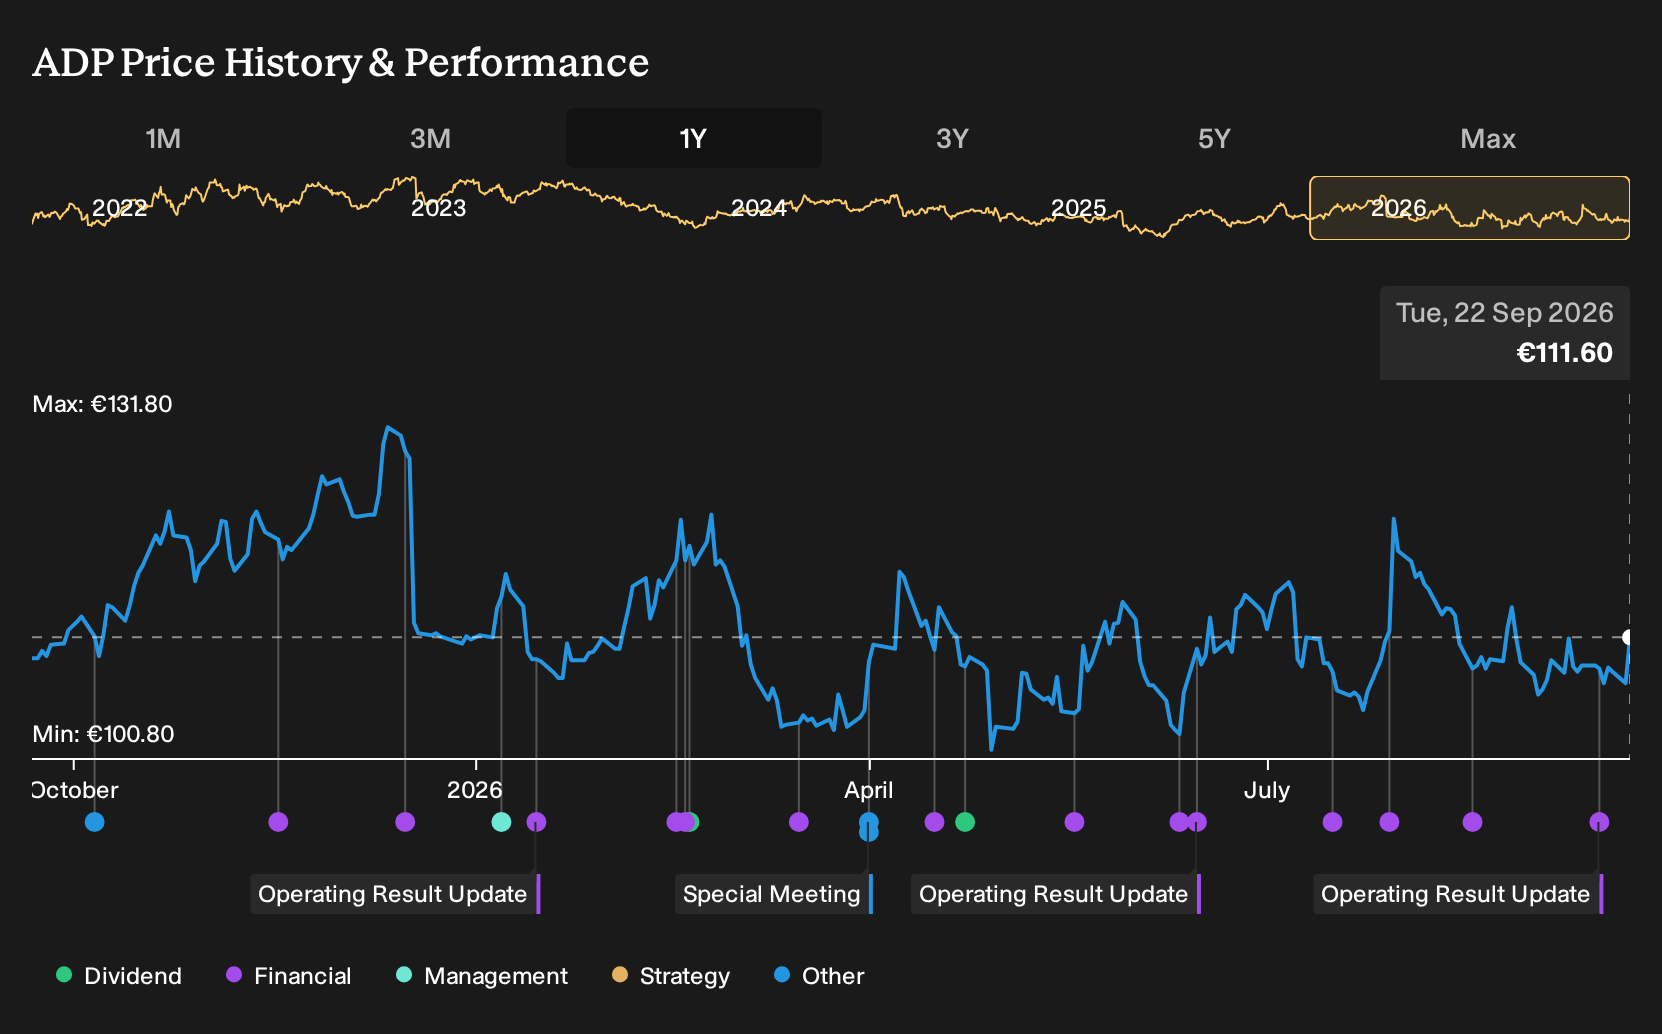
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly €93.7 to €127.1 per share, so retail views on Aeroports de Paris already cover a wide band. Treat those as starting points. Factor in risks around leverage, cost inflation and regulatory outcomes, then weigh how much flat August traffic changes your own stance.
Explore another Aeroports de Paris fair value estimate, including one that suggests there may be as much as 14% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aeroports de Paris research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aeroports de Paris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aeroports de Paris' overall financial health at a glance.
Looking for more Aeroports de Paris style investment ideas?
Once you have a view on Aeroports de Paris, it can help to set it alongside a few carefully filtered peers so you can judge risk, quality and income potential on the same screen.
- For investors who care most about financial resilience, compare Aeroports de Paris with companies on a list of solid balance sheet and fundamentals (198 results) that pairs healthier balance sheets with solid fundamentals.
- If value is your priority, line up Aeroports de Paris next to a curated 171 high quality undervalued stocks that screens for stronger cash generation and sturdier finances.
- Income focused investors can benchmark Aeroports de Paris against a hand picked 160 dividend fortresses that targets yields above 5% with an eye on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com