
Raiffeisen Bank International (WBAG:RBI) Could Be 14% Overvalued Following Vienna Court Win
Raiffeisen Bank International (WBAG:RBI) is back in focus after winning a court ruling in Vienna that awards around €3.15b in damages linked to funds frozen in Russia, while also publicly rejecting fresh short-seller allegations.
Raiffeisen Bank International’s latest legal win and rebuttal of the short report arrive after a period of strong momentum, with the share price at €63.3 and a 90 day share price return of 16.15% contributing to a 1 year total shareholder return of 124.01%, as well as a very large 3 year total shareholder return that is more than 5 times the starting level.
Scan how Raiffeisen Bank International compares with other financially solid opportunities by reviewing the hand picked list of solid balance sheet and fundamentals (198 results) in today's market.
Bulls view Raiffeisen Bank International’s recent court victory and multi year shareholder gains as a form of validation, while bears highlight the bank’s Russia exposure and the impact of short seller criticism. The key question now is which narrative the current valuation appears to reflect more strongly.
Most Popular Narrative: 14% Overvalued
The most followed valuation narrative for Raiffeisen Bank International puts fair value at about €55.59, compared with the latest close at €63.3. This frames the current price as richer than its implied fundamentals once risk and growth assumptions are baked in.
Strong underlying loan and deposit growth, especially in CEE countries like Czechia and Slovakia, is being supported by continued economic convergence and higher demand for modern banking services, indicating healthy revenue and net interest income expansion potential.
Accelerating digitalization and adoption of cashless payment in emerging Europe is driving fee income growth and yielding opportunities for scalable, higher-margin digital products, as evidenced by the strong quarterly rebound in fee income, likely boosting non-interest income and overall earnings.
See why 21 investors see Raiffeisen Bank International as 14% overvalued.
That narrative is built on a discounted cash flow style approach using a 7.26% discount rate, modest annual revenue growth assumptions of around 1.6%, and a projected profit margin near 27%. It also assumes Raiffeisen Bank International trades on a future P/E of roughly 9x, in line with its current multiple but below wider bank sector levels used in the model.
Analysts contributing to this framework expect earnings to reach about €2.5b by 2029, with scope for outcomes between €2.2b and €3.0b depending on how fee income, costs and regional risks play out. The fair value of €55.59 reflects these scenarios blended together, alongside ongoing exposure to Russia, litigation costs in markets like Poland, and tax and regulatory overhang in Austria and Ukraine.
For readers comparing narratives with market pricing, the key takeaway is that the prevailing model views Raiffeisen Bank International as a solidly profitable regional lender, but not one where current growth and risk projections justify a materially higher earnings multiple than today.
Result: Fair Value of €55.59 (OVERVALUED)
Still, Raiffeisen Bank International’s Russia exposure and unpredictable litigation costs in Poland remain capable of upsetting earnings expectations and challenging the current valuation narrative.
Find out about the key risks to this Raiffeisen Bank International narrative.
Another View on Raiffeisen Bank International’s Valuation
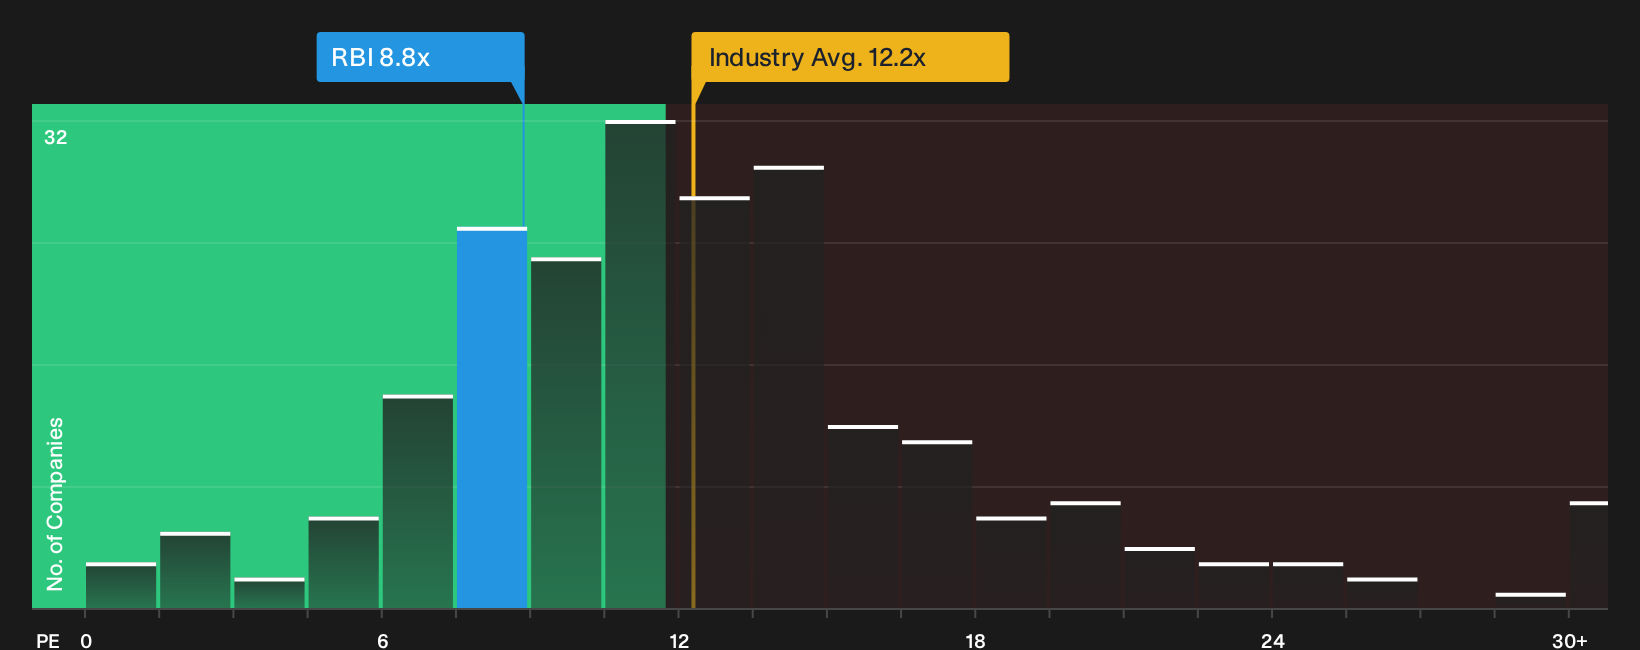
A different lens paints Raiffeisen Bank International as inexpensive. The stock trades on a P/E of 8.8x, while the European Banks group sits near 12.4x and close peers around 15.8x. The fair ratio is 11.3x, which hints the market could eventually lean toward a higher multiple.
That gap suggests either the earlier fair value narrative is too cautious, or the discounted multiple is compensation for the Russia, litigation and earnings quality risks flagged by analysts. Which story do you believe the current discount is really pricing in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Raiffeisen Bank International can be useful, especially if you move quickly and weigh the upside against the red flags yourself. Take a moment to review the 4 key rewards and 3 important warning signs
Looking for more Raiffeisen Bank International style investment ideas?
If Raiffeisen Bank International has sharpened your focus, do not stop here. Broadening your search for ideas now could help you avoid having to catch up later.
- Target potential mispricing by scanning the 171 high quality undervalued stocks that combine stronger fundamentals with room for the market to reassess expectations.
- Prioritise resilience by reviewing the 229 resilient stocks with low risk scores that score well on balance sheet strength and lower overall risk profiles.
- Explore opportunities by checking the 619 high quality undiscovered gems that pair financial quality with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com