
Slowing Sales Growth Might Change The Case For Investing In Procore Technologies (PCOR)
- Recent commentary on Procore Technologies highlights slowing sales momentum and a cost structure that is still weighing on operating margins and profitability.
- The key issue is not demand for construction software in general but how efficiently Procore Technologies converts that demand into sustainable, margin-supportive revenue.
- We will now examine how Procore Technologies' investment narrative is affected by slowing demand and persistent questions over its cost structure.
Procore Technologies Investment Narrative Recap
To own Procore Technologies, you need to be comfortable with a construction software leader that is still loss making and working through a heavy cost base. The big belief is that a large addressable market and broad product suite can support durable subscription revenue once sales efficiency and spending are brought under tighter control.
The recent focus on slowing sales momentum and weak operating margins keeps the main near term catalyst very clear: evidence that Procore can hold double digit revenue growth while lifting profitability. The biggest risk is that elevated operating expenses and macro sensitive construction activity keep the platform stuck in low margin territory.
Recent commentary on Procore Technologies has not introduced a new product launch or deal announcement. The most relevant reference point is the ongoing push into AI powered tools such as Procore Helix and Agent Builder, which management has framed as key to deeper customer adoption and workflow automation.
For you, the question is whether these AI modules and broader financial and resource management capabilities can support better cross sell, higher average revenue per customer, and improved retention. If that progress stalls, concerns about slowing demand, North America concentration, and persistent operating losses are likely to stay front of mind.
What The Current Procore Technologies Forecasts Assume
Procore Technologies' current analyst narrative points to US$2.0b in revenue and US$141.6m in earnings by 2029. That path is built on a forecast 13.4% yearly top line expansion and a swing in profitability from a loss of US$76.9m today to positive earnings, which is an uplift of about US$218.5m.
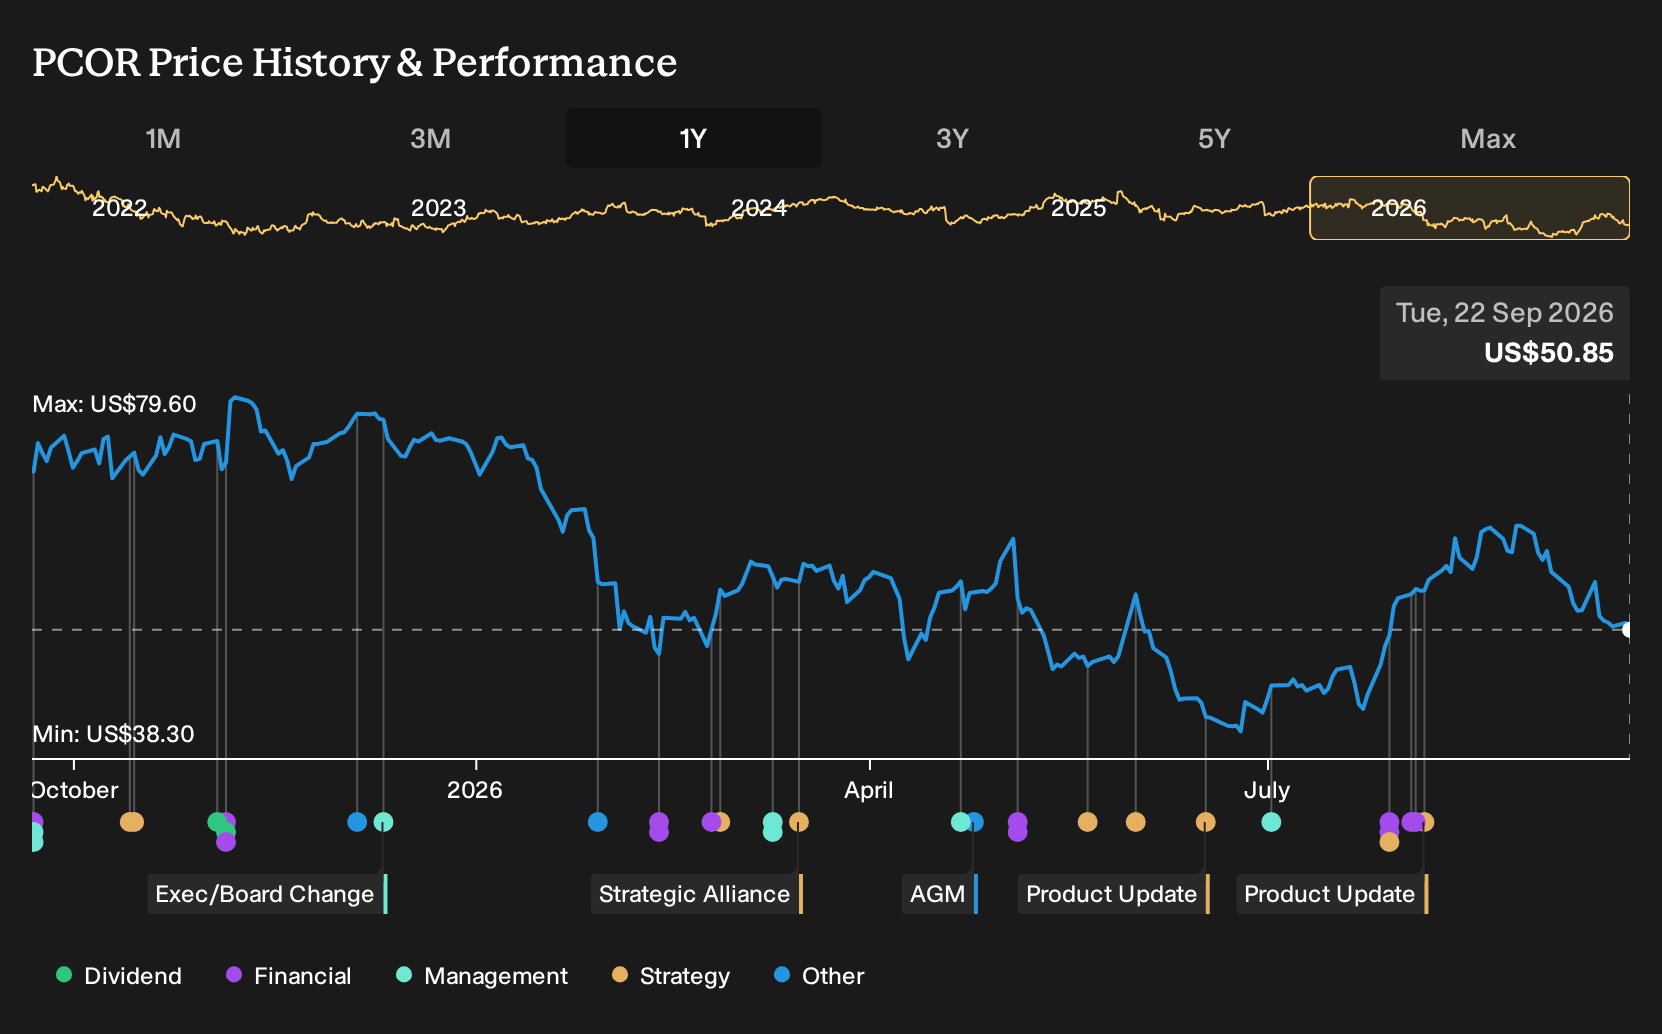
Uncover why Procore Technologies' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Procore Technologies leans heavily on AI as a long term catalyst. The most optimistic analysts were modeling US$2.1b of revenue and US$176.0m of earnings by 2029 before this news, far above the baseline. You can treat that as a reminder that opinions vary widely and may shift as fresh information lands.
Explore 4 other Procore Technologies fair value estimates, including one that suggests potential upside of up to 67% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Procore Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Procore Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procore Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Procore Technologies?
Once you have a view on Procore Technologies, it can help to widen the lens and compare it with other companies that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- For investors focused on quality at a reasonable price, scan a curated set of companies that screen as both financially solid and potentially mispriced with the 29 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, filter for businesses that carry fewer red flags by running the 30 resilient stocks with low risk scores.
- When you want to go beyond familiar tickers and look for underfollowed opportunities with strong fundamentals, the 16 high quality undiscovered gems can surface ideas that rarely make the headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com