
Veeco Instruments (VECO) And The AI Demand Question Behind Its Valuation
Veeco Instruments (VECO) drew fresh attention after its recent share move, with the price closing at $44.36. Investors are weighing this semiconductor equipment specialist against its returns, profitability, and current valuation metrics.
Recent trading has been choppy for Veeco Instruments, with the share price up 8.5% over the past week but down 7.3% over the past month and 37.7% over the past quarter. At the same time, the year-to-date share price return of 45.3% sits alongside a 1-year total shareholder return of 49.9% and a 5-year total shareholder return of 94.9%. Together, these figures indicate longer term momentum that has recently cooled as investors reassess the balance between growth potential and risk.
Scan how Veeco Instruments compares to other semiconductor equipment players by reviewing our hand picked list of 86 AI infrastructure stocks that are also tied to chip demand and fabrication spend.
Veeco Instruments now trades well below the average analyst price target, even after the recent pullback. Is that a genuine markdown, or is the market simply pricing in real execution and cycle risk?
Most Popular Narrative: 26% Undervalued
Veeco Instruments is trading at $44.36, while the most followed narrative pegs fair value around $60.33 using an 11.36% discount rate. That gap focuses attention on whether current AI and chip demand can support the growth assumptions included in that estimate.
Current investor sentiment may be overestimating the sustained demand and revenue growth from advanced semiconductor manufacturing equipment, as macroeconomic uncertainty, reduced capital expenditure from major chipmakers, and the risk of global trade tensions including potential recurring tariffs and regulatory barriers, particularly in China, could materially slow new orders and end-market growth, leading to more volatile top-line results in coming years.
See why 11 investors see Veeco Instruments as 26% undervalued.
Result: Fair Value of $60.33 (UNDERVALUED)
Still, the narrative could be challenged if AI related demand softens, or if Veeco Instruments faces sharper pricing pressure from large, concentrated customers.
Find out about the key risks to this Veeco Instruments narrative.
Another View on Veeco Instruments Valuation
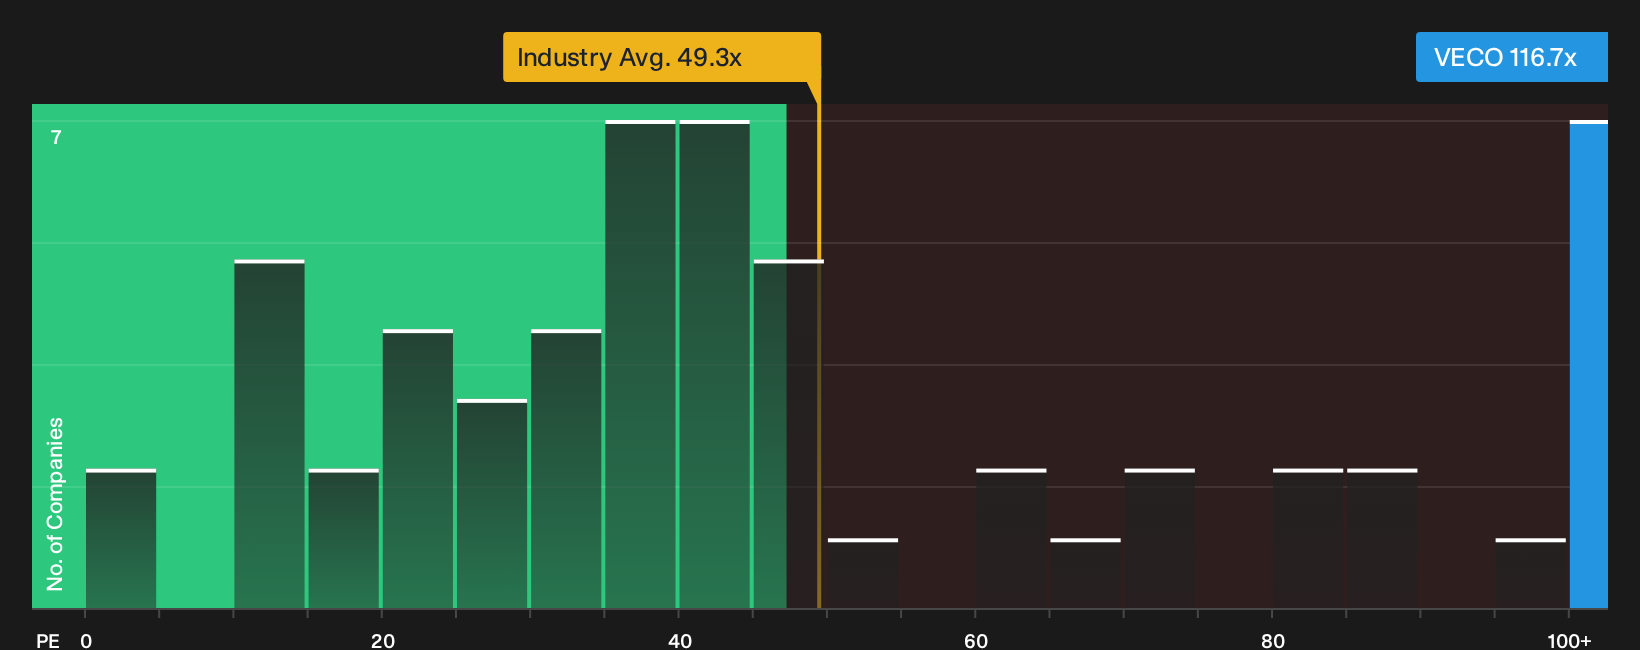
The fair value narrative points to Veeco Instruments trading below an estimated $60.33 per share. Using a simple P/E lens paints a very different picture. The stock trades at about 116.7x earnings, compared with 72.1x for peers and 47.3x for the broader US semiconductor group.
The fair ratio for Veeco Instruments sits at 64.3x P/E, which is far lower than where the shares change hands today. That gap suggests valuation risk if the market drifts closer to that fair ratio over time, rather than the earnings path investors are currently focusing on. Which yardstick do you trust most when the story gets bumpy?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Veeco Instruments valuation are clear, so use that tension as a prompt to review the numbers yourself and move quickly while sentiment is still forming. To weigh the upside case against the concerns already flagged by other investors, start with the 2 key rewards and 4 important warning signs.
Looking for more Veeco Instruments sized investment ideas?
If Veeco Instruments has you thinking more carefully about valuation and risk, do not stop here. Broader idea generation can help sharpen every decision.
- Chase potential mispricings by scanning the 29 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (23 results) with the cash and debt profiles many investors only check after a drawdown.
- Get ahead of the crowd by tracking 16 high quality undiscovered gems that have strong metrics but limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com