
iPhone 18 Launch Could Be A Game Changer For T Mobile (TMUS)
- T-Mobile US has already rolled out Apple’s iPhone 18 lineup, new Apple Watch models and AirPods 5 with heavy trade in deals, extended 36 month financing and iPhone Handoff support, alongside fresh device and home internet promotions across consumer, business and Metro by T-Mobile customers.
- The broad push into richer Apple bundles, flexible equipment plans and 5G Standalone roaming with Jio indicates that T-Mobile US is leaning harder into higher value usage and multi device relationships rather than just chasing headline subscriber adds.
- The next area of focus will be how T-Mobile US’s expanded Apple offers and iPhone Handoff feature intersect with its long term investment narrative.
Scan beyond T-Mobile US and see how other carriers are positioning around device financing, trade in credits and 5G by reviewing our hand picked list of solid balance sheet and fundamentals (23 results).
T-Mobile US Investment Narrative Recap
To own T-Mobile US you need to believe the carrier can keep turning its 5G network, broadband push and AI tools into higher value postpaid and home internet relationships, while avoiding a spike in churn from plan changes or price moves. The recent Apple launch and richer bundles fit within that core story but do not alter it.
At the moment, the key near term swing factor is how customers respond to heavier device promotions and extended financing. These can support premium plan adoption but also pressure margins. A major risk is that aggressive offers across wireless and cable increase competitive intensity and force even richer incentives.
The iPhone 18 and Apple Watch lineup, combined with trade in credits and EIP Flex 36, appears most relevant here because it directly targets the premium users T-Mobile US aims to move to higher ARPA. Rich subsidies and longer payment terms can help keep that group inside the ecosystem and support 5G broadband and home internet adoption.
The same announcement also highlights execution risk. Heavy bill credits, equipment financing and iPhone Handoff at US$5 per month add complexity to pricing and retention. Investors are watching whether these Apple centric offers and new 5G Standalone roaming with Jio contribute to steadier service revenue and cash generation without materially increasing churn or promotional spending.
T-Mobile US projections point to revenues of US$104.8b and earnings of US$17.9b by 2029. Analysts are assuming revenue expands at roughly 4.4% a year, with earnings rising by about US$7.3b from US$10.6b today to reach that 2029 consensus level.
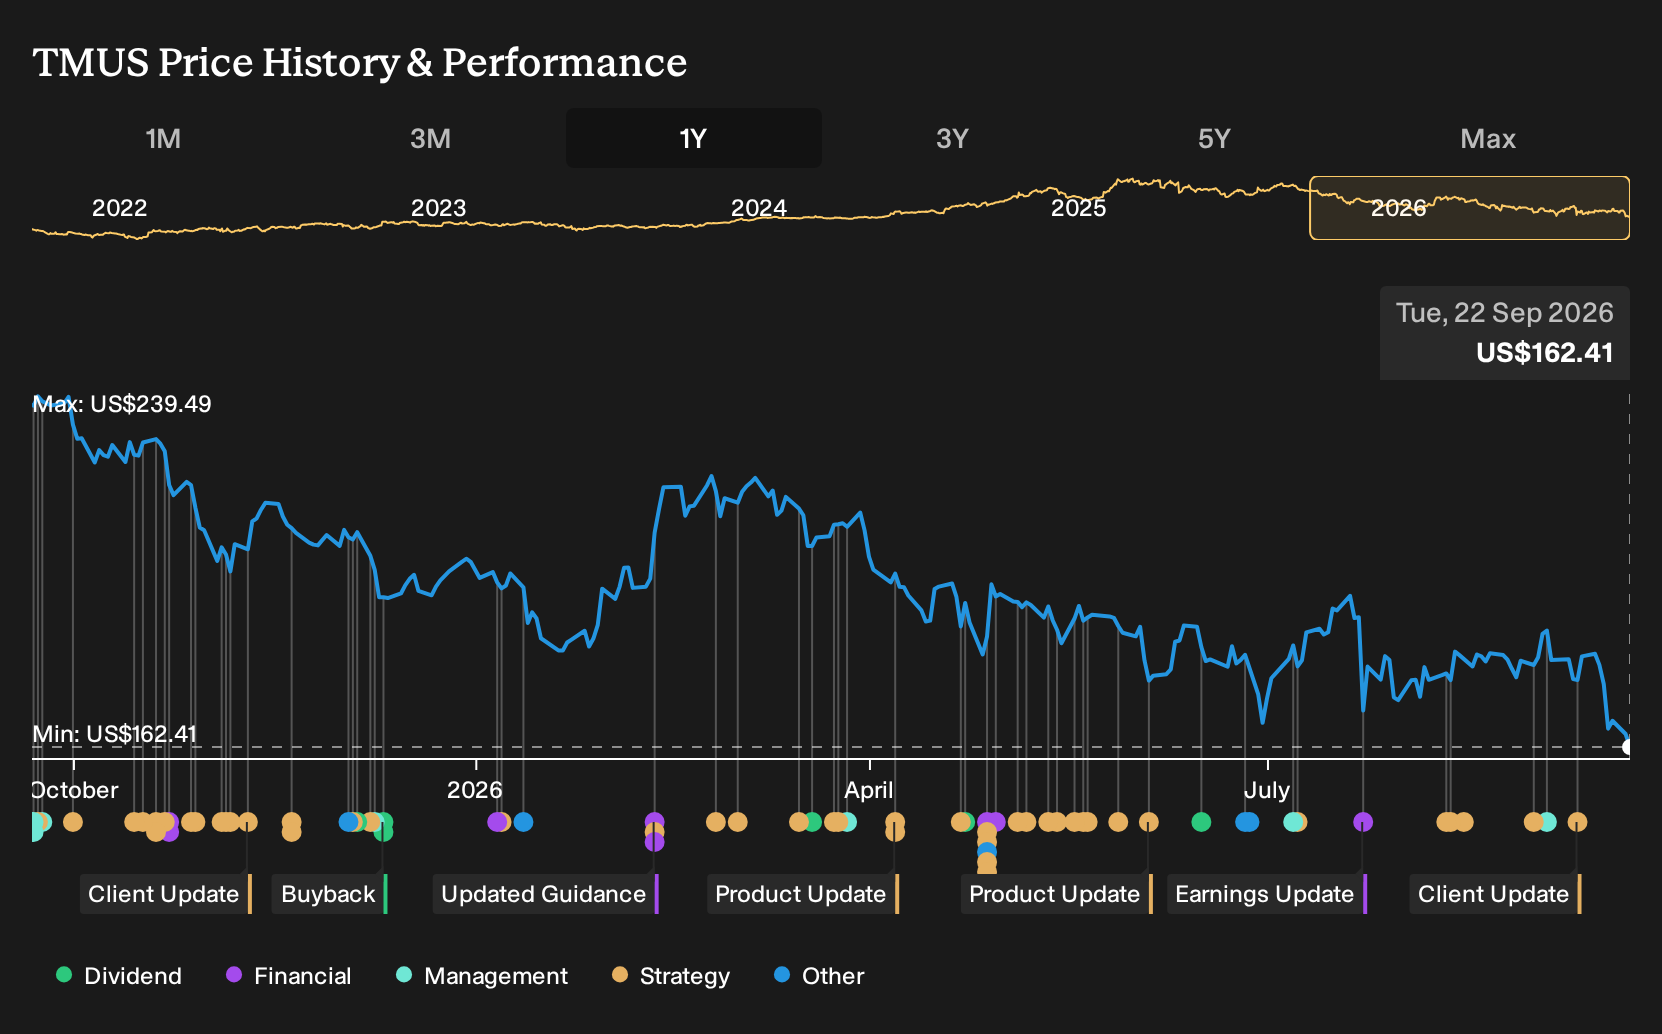
Uncover why T-Mobile US' fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view flips the story around T-Mobile US capital spending rather than churn. Some of the lowest analysts lean into the risk that heavy 5G, fiber and AI outlay caps future earnings power. They were penciling in revenue of about US$101.6b and earnings of roughly US$15.7b by 2029 before this Apple news, so their expectations already sat below consensus. You can treat this new iPhone push and 5G Standalone roaming milestone as a fresh data point that may eventually shift both the cautious and optimistic camps.
Explore 3 other T-Mobile US fair value estimates, including one that suggests it could be worth just $243.38!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your T-Mobile US research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking For More Investment Ideas Beyond T-Mobile US?
If T-Mobile US has sharpened your focus on quality, balance sheet strength and clear earnings power, it can be useful to line it up against a wider set of opportunities using structured stock lists from the Simply Wall St Screener.
- For investors who want value with resilience, review our hand picked 29 high quality undervalued stocks that combine attractive pricing with solid fundamentals.
- If capital preservation sits high on your priority list, scan a curated 30 resilient stocks with low risk scores to see which businesses score well on stability.
- When you want to get ahead of the crowd, check out a focused 16 high quality undiscovered gems that highlights companies with strong metrics but limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com