
KLA (KLAC) Stock Looks Expensive Despite Strong Semiconductor Growth
KLA Corporation has delivered very strong share price gains in recent years, which naturally raises the question of whether the current valuation is still supported by its earnings power. With the stock coming off another solid run, investors are asking how much of the story is already reflected in the multiple they are paying today.
- Over the past 5 years, KLA has returned about 470%, so a lot of future earnings strength may already be embedded in the market’s expectations.
- Fresh research pointing to substantial growth in semiconductor metrology, including increased investment and R&D by KLA, can influence how durable investors expect its earnings base to be.
- There is a second opinion on KLA worth weighing. See what analysts think KLA's shares could be worth.
For investors, the debate is whether KLA's current share price is justified by the earnings that the business generates today and is expected to produce over time.
If you want to test the same earnings based valuation question you are asking of KLA across a wider field of opportunities, run the 29 high quality undervalued stocks.
Is KLA Getting Expensive on Earnings?
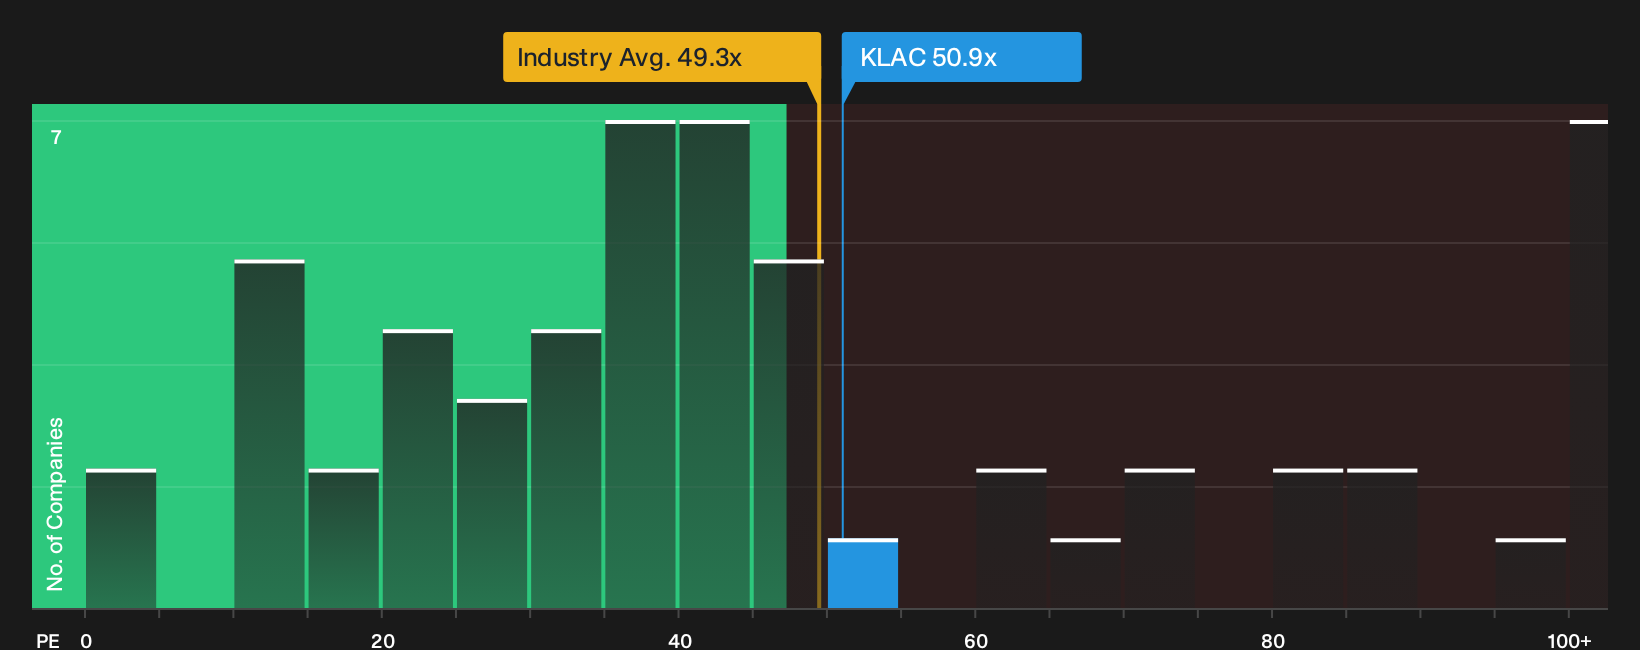
The P/E ratio is a useful lens for KLA because earnings are a central driver of how investors value established semiconductor equipment suppliers. KLA trades on a P/E of about 50.9x, which is slightly above the wider semiconductor industry average of 49.3x and also higher than the peer group at roughly 48.2x. On this metric, you are paying more per dollar of earnings for KLA than for a typical competitor in its sector.
The fair P/E level suggested by a more tailored model that factors in KLA's growth profile, profitability, size and risk sits below the current 50.9x, so the stock screens as overvalued on this framework. Because the metrology market outlook has been strong and KLA has been investing in R&D to keep its tools competitive, enthusiasm around that opportunity may be contributing to investors accepting this richer earnings multiple. If you want to see how much of a gap that model finds between price and earnings, and compare KLA's P/E against other stocks on the same basis, run the. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for KLA pick up where the P/E question leaves off and spell out which growth, margin and earnings paths would need to hold for the stock to look materially stronger or weaker than today's price. Rather than focusing on a single multiple or model output, each one sets out the key assumptions behind its view of fair value so you can compare those inputs with KLA's reported results over time.
Community views on KLA Corporation are split between those who see a long runway left in the current setup and those who think the risks already crowd the valuation.
Bull case: 19% undervalued
"The current valuation implies the share price does not fully reflect KLA’s record revenue and free cash flow, its very high process control market leadership, or the scale of multi year AI and advanced packaging driven growth that management now targets..."
Discover why this Narrative puts KLA at 19% undervalued.
Bear case: 8% overvalued
"Ongoing and intensifying US-China trade tensions, compounded by unpredictable global tariff regimes and new export controls, are increasingly limiting KLA's access to the critical Chinese semiconductor market..."
Explore why this Narrative puts KLA at 8% overvalued.
One more check for KLA before you stop at the share price
Before you close the book on KLA Corporation after comparing multiples, it helps to look at who is actually steering the business and how their incentives are wired. See who runs KLA and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com