
Lennar (LEN) Issued Fresh Guidance, Does It Look Fairly Valued?
Lennar (LEN) just put fresh numbers on the table, reporting third quarter and nine month results to August 31, 2026, along with new fourth quarter operating guidance that details expected orders and deliveries.
Those fresh results and fourth quarter guidance landed against a choppy backdrop for Lennar, where the 1-day share price return of 6.38% follows a year-to-date share price decline of 20.30% and a 1-year total shareholder return that is down 31.25%, suggesting that recent momentum is improving off a weaker longer-term base.
Spot potential rebounds beyond Lennar by scanning our curated list of 29 high quality undervalued stocks with resilient balance sheets and cash flows.So after a sharp one day bounce and weak recent earnings, does Lennar now offer a skew that still rewards buyers for taking on the housing cycle risks, or is the valuation already doing that heavy lifting?
Most Popular Narrative: 1% Undervalued
Lennar’s most followed valuation narrative pegs fair value at $83.69, almost level with the last close at $83.06, yet still frames a small discount using a relatively conservative return hurdle of 8.78%.
The analysts have a consensus price target of $83.69 for Lennar based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of $79.7, the analyst price target of $83.69 is 4.8% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 43 investors see Lennar as 1% undervalued.
Result: Fair Value of $83.69 (ABOUT RIGHT)
Still, analyst expectations for higher mortgage rates and heavier buyer incentives could pressure Lennar’s margins, especially given its exposure to more rate sensitive entry level buyers.
Find out about the key risks to this Lennar narrative.
Another View: DCF Flags Less Upside
While the popular Lennar narrative points to fair value near $83.69, the Simply Wall St DCF model tells a cooler story. On that framework, Lennar at $83.06 trades above an estimated future cash flow value of $65.09, which points to limited upside and a thinner margin of safety.
That gap does not automatically make Lennar expensive. However, it does suggest investors are paying a premium to the SWS cash flow estimate. The key debate becomes simple: Are you more comfortable anchoring on analyst earnings assumptions or on a cash flow model that asks for a lower entry price?
Look into how the SWS DCF model arrives at its fair value.
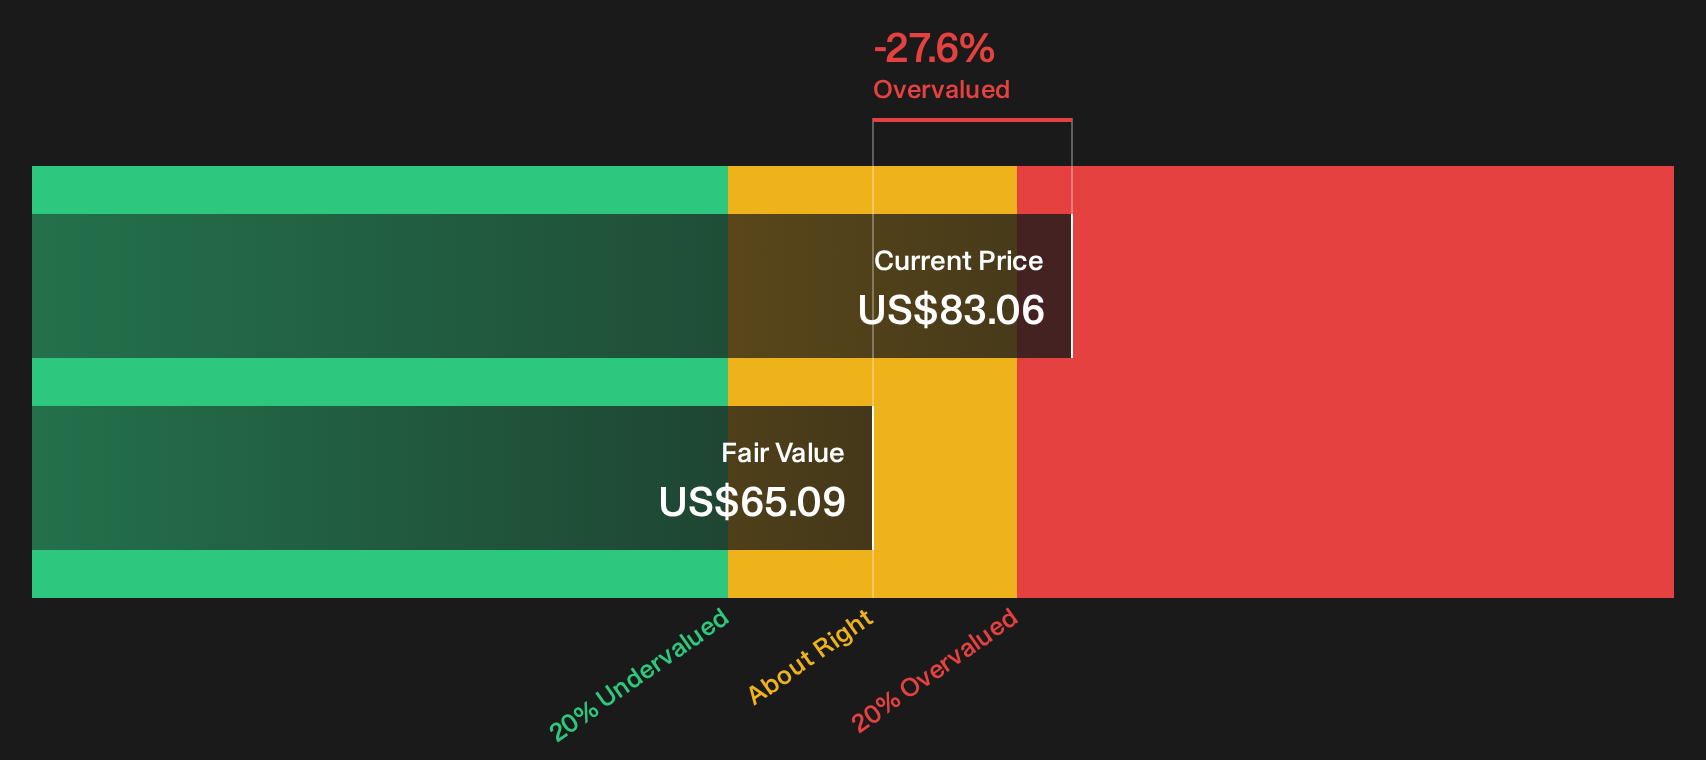
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lennar for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading this mix of pressure and potential around Lennar, it makes sense to move quickly, review the underlying data yourself, and decide where you land on the balance of risk and opportunity by weighing its 3 key rewards and 1 important warning sign.
Ready to act beyond Lennar?
If Lennar has your attention today, do not stop there. Broaden your watchlist now or risk missing ideas that fit your goals even better.
- Target resilient compounding potential by scanning a curated 30 resilient stocks with low risk scores built around companies with lower overall risk profiles.
- Spot compelling entry points by reviewing a focused 16 high quality undiscovered gems packed with financially solid businesses that fewer investors are watching.
- Strengthen portfolio foundations by filtering through a list of solid balance sheet and fundamentals (23 results) that prioritises robust financial positions and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com