
Duolingo (DUOL) Teams Up With Brawl Stars On A Fair Value Debate
Why a gaming crossover matters for Duolingo stock
Duolingo (DUOL) just teamed up with Brawl Stars on a global in-app crossover that pulls Duo the Owl into the game and brings Spike into language lessons, blending gaming and education for shared engagement.
Against that backdrop, Duolingo’s share price has been choppy, with a 90 day share price return of 11.77% and a 30 day gain of 1.08%, but a year to date share price decline of 16.30% and a 1 year total shareholder return fall of 50.68%. This shows that momentum has faded despite product headlines like the Brawl Stars event.
Surf 16 high quality undiscovered gems that, similar to Duolingo’s gaming crossover, are using fresh partnerships to keep users engaged even as market attention lags the underlying product story.Duolingo looks like a strong product story with playful partnerships and a global user base. The tougher call is whether a US$6.99b price tag still makes sense following a 1 year return that fell 50.68%.
Most Popular Narrative: 23% Undervalued
Duolingo’s most followed valuation storyline pegs fair value at $192.64 against a last close of $147.71, which frames the current share price as a sizable discount and puts extra weight on what could keep engagement and monetization moving together.
Analyst consensus sees Chess, Math, and Music as enhancing user growth and engagement, but these new subjects could be the cornerstone of Duolingo's evolution into a dominant global multi-subject learning platform, unlocking an even larger total addressable market and driving a multi-year acceleration in both subscriber growth and long-term revenue expansion far beyond language learners.
See why 18 investors see Duolingo as 23% undervalued.
Result: Fair Value of $192.64 (UNDERVALUED)
Still, two issues could trip up this bullish Duolingo narrative: rising AI powered language tools that undercut paid learning, and higher customer acquisition costs that squeeze profitability.
Find out about the key risks to this Duolingo narrative.
Another View on Duolingo’s valuation
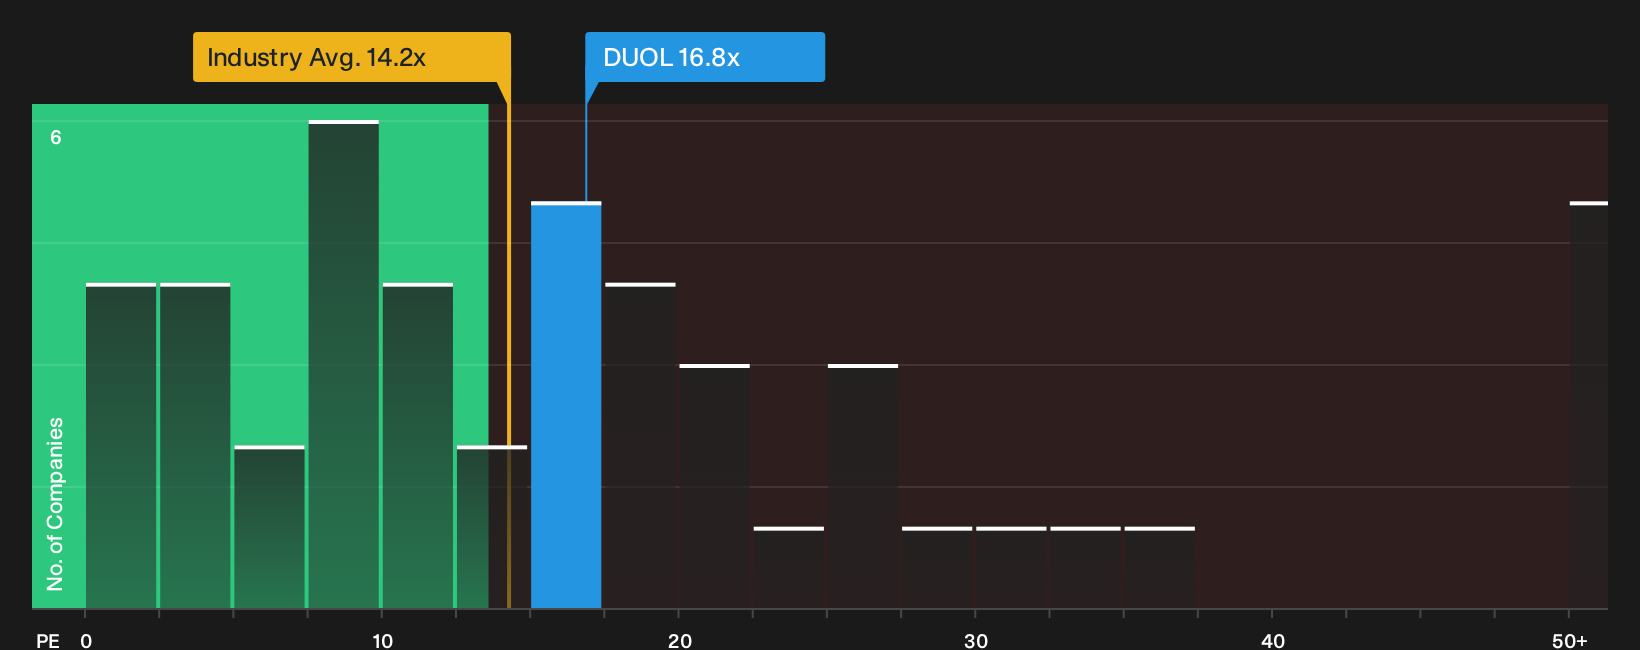
The bullish narrative presents Duolingo as 23% undervalued at a fair value of $192.64, yet the simple P/E picture is less generous. DUOL trades on a 16.8x P/E, which is higher than the US Consumer Services average of 14.2x and above a fair ratio of 10.9x. That gap points to valuation risk if sentiment or growth expectations cool from here, so investors are left to decide which story they find more convincing when real money is on the line.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Duolingo can feel confusing. Move quickly, review the core data, and weigh both sides using 2 key rewards and 2 important warning signs
Looking for more Duolingo style investment ideas?
If Duolingo’s mixed signals have you thinking harder about price versus potential, you can use screeners to hunt for new opportunities before everyone else starts paying attention.
- Target potential value opportunities by filtering for companies combining quality fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with robust finances and healthy balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Seek stability with income by scanning for payout opportunities using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com