
Is AUTO1 Group (XTRA:AG1) Fully Valued Following Its CFO Resignation?
AUTO1 Group (XTRA:AG1) has been thrust into focus after CFO Christian Wallentin resigned for family reasons, leaving CEO and Co Founder Christian Bertermann to assume interim finance responsibilities.
Recent trading reflects mixed sentiment around AUTO1 Group. The share price return is up 2% over the last day to €18.36 but has fallen 13.23% over 30 days and 34.66% year to date. The 3 year total shareholder return of about 19x contrasts sharply with a 35.49% decline over the past year, which suggests that leadership changes and events such as the upcoming Berenberg and Goldman Sachs conference are being weighed against an older, very strong recovery story.
Compare AUTO1 Group's sharp swings with a curated set of resilient peers by scanning the 229 resilient stocks with low risk scores, which flags businesses with sturdier risk profiles and steadier share price behaviour.
AUTO1 Group has swung from a 3-year return of about 19x to a 35% decline over the past year. After that kind of round trip, is most of the recovery already priced in, or is there still clear upside left as the valuation screens suggest?
Preferred P/E of 49.5x for AUTO1 Group: Is it justified?
AUTO1 Group closed at €18.36 while trading on a P/E of 49.5x, which is high relative to both peers and fair value estimates implied by the fair P/E ratio. That combination suggests traders are already paying up for earnings, even as the share price has retreated sharply over the past year.
The P/E multiple compares what you pay per share with the profit attributable to each share. For a used car marketplace like AUTO1 Group that has only recently moved into consistent profitability, a rich P/E can reflect investors factoring in strong forecast earnings growth and the potential scaling of its digital platforms across Retail and Merchant segments.
That optimism is expensive. AUTO1 Group trades at a 49.5x P/E compared with a peer average of 25.1x and a European Specialty Retail sector average of 15x. The fair P/E ratio estimate of 28x is also far below the current level, which is a gap the valuation could move towards if expectations or sentiment reset.
Explore the SWS fair ratio for AUTO1 Group.
Result: Price-to-Earnings of 49.5x (OVERVALUED)
Still, the AUTO1 Group story can break if used car volumes soften or if the high P/E multiple compresses quickly, as sentiment toward growth cools.
Find out about the key risks to this AUTO1 Group narrative.
Another View on AUTO1 Group's Value
On earnings, AUTO1 Group looks expensive at a 49.5x P/E. The SWS DCF model points in the opposite direction. At €18.36 the share price sits well below the model's future cash flow value estimate of €50.51, which frames the stock as undervalued instead of stretched. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
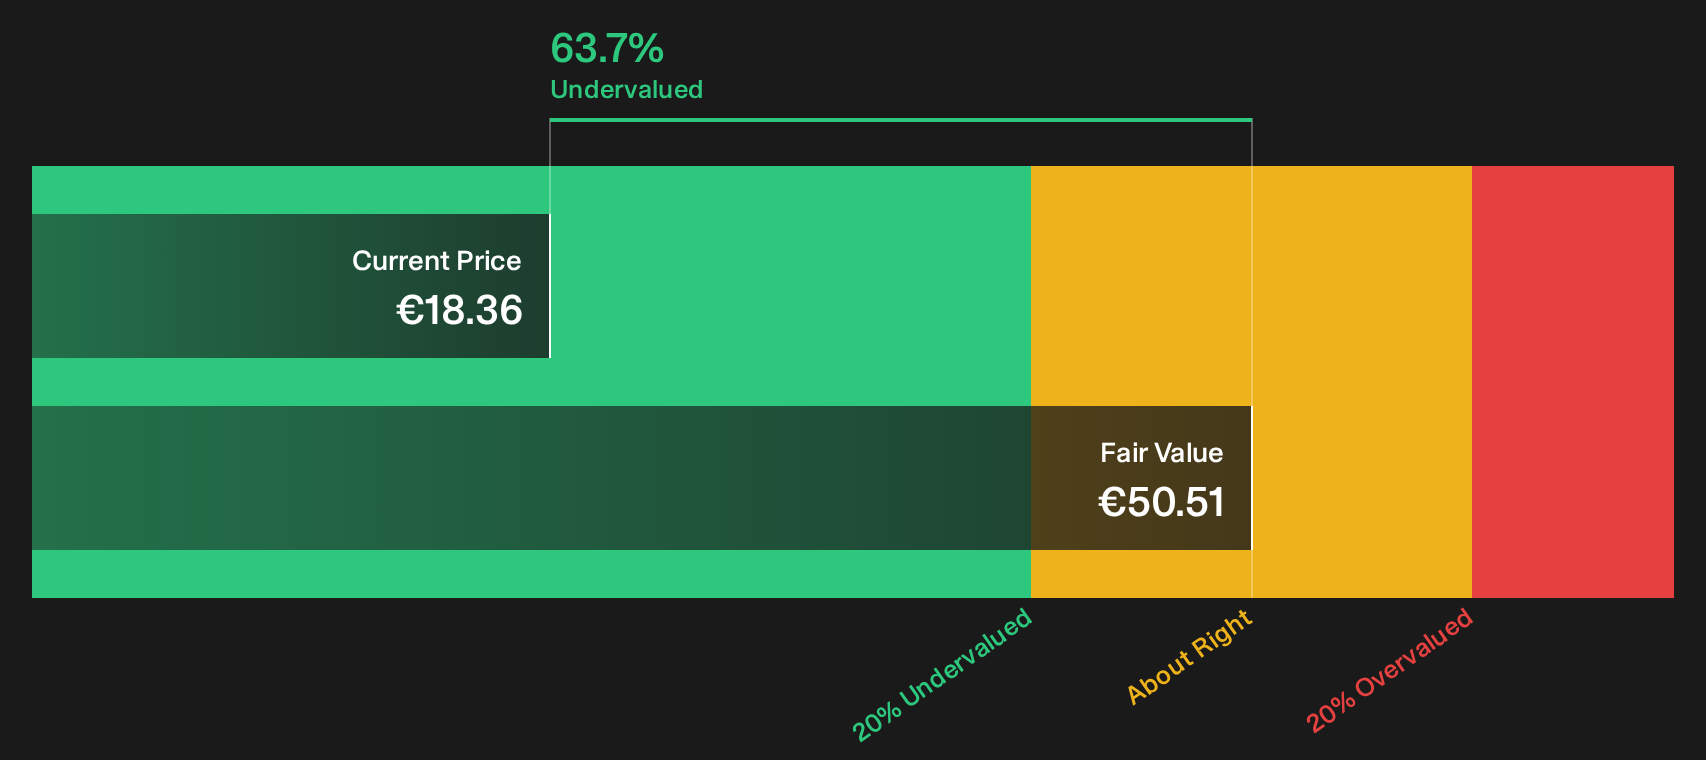
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AUTO1 Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and sentiment often create the most interesting setups. Move quickly, review AUTO1 Group's data directly, and weigh the 3 key rewards and 1 important warning sign.
Looking for more AUTO1 Group style investment ideas?
If AUTO1 Group has your attention, do not stop here. Broaden your watchlist by checking other clear setups that could suit your approach and risk comfort.
- Target resilience by scanning a list of solid balance sheet and fundamentals (198 results) that highlights businesses with sturdier finances when conditions get tougher.
- Hunt for mispriced quality through the 174 high quality undervalued stocks that focuses on stronger fundamentals trading at what our models flag as discounted levels.
- Boost your opportunity pipeline with the 619 high quality undiscovered gems that surfaces underfollowed companies investors often overlook until momentum appears.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com