
South32 (ASX:S32) Shares May Trade At A Discount To Earnings
South32 has delivered a sharp share price run over the past year, which naturally puts a spotlight on whether the current tag is still supported by its earnings power. With the stock now well above where it traded a year ago, the question for investors is how that move lines up against what the business is actually generating in profit.
- South32 has returned 94.9% over the past year, which raises the stakes on whether recent enthusiasm is fully backed by the level and quality of its earnings.
- The group’s value story rests heavily on how efficiently it can turn its resource base and capital spending into sustainable earnings, since that drives the cash available to support its current market valuation.
- There is a second opinion on South32 worth weighing. See what analysts think South32's shares could be worth.
The issue now is whether South32’s current share price can be justified by its earnings when measured against a Fair Ratio benchmark.
If you want to explore the same earnings-based valuation question that hangs over South32 across a wider field, scan through 6 high quality undervalued stocks.
Does South32 Look Undervalued on Earnings?
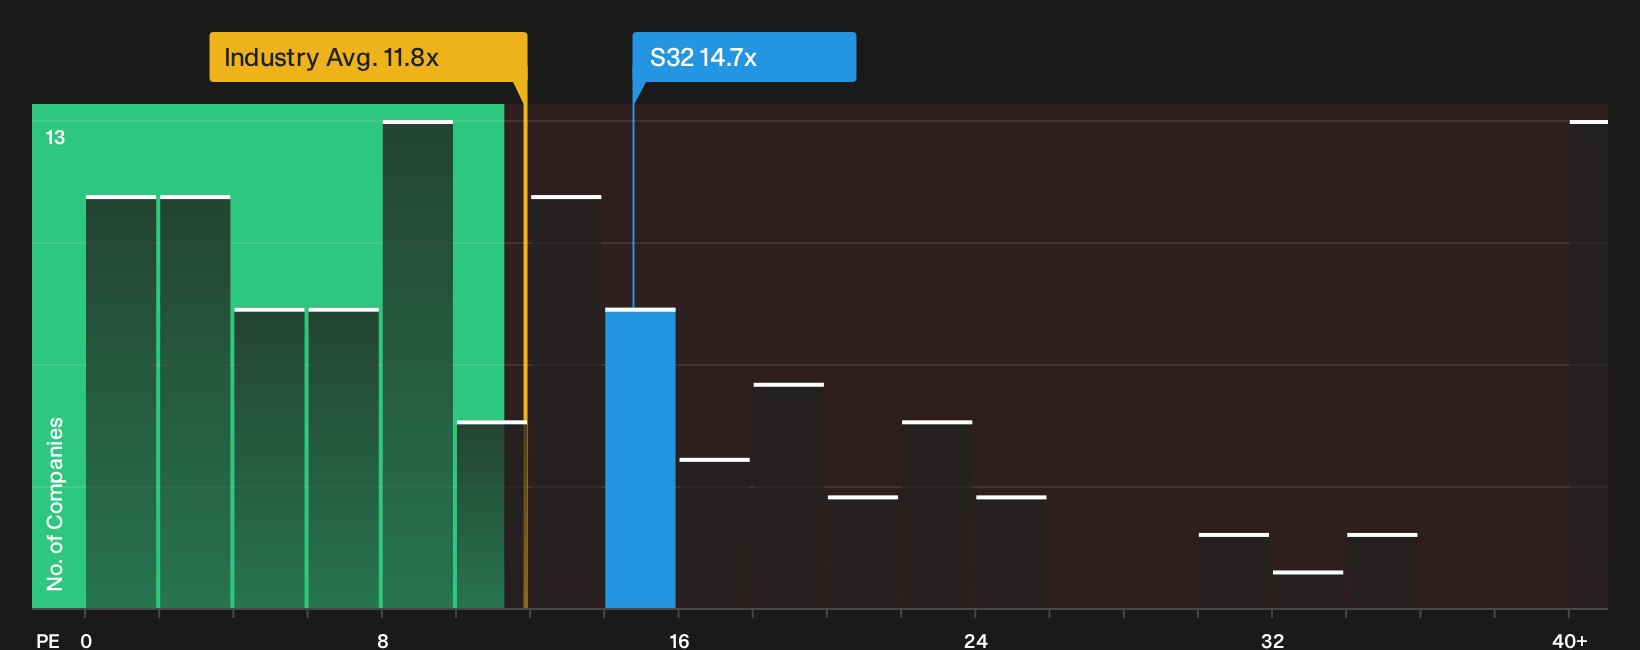
The P/E ratio suits South32 because earnings are a key anchor for how investors look at resource producers over time. On this lens, South32 trades on a P/E of 14.7x, which is below the broader Metals and Mining industry average of 11.8x. That gap suggests the market is assigning some premium over the typical miner, yet not at levels that push it into frothy territory.
A tailored Fair Ratio that factors in South32’s growth profile, margins, size and risk points to a higher earnings multiple than where the shares currently change hands. This tilts the picture toward undervalued on this framework. The P/E is also well under the peer group average of 34.6x, so the stock screens cheaper than many comparable listings that investors use as reference points. This combination of a discount to the Fair Ratio and a wide gap to peers is what gives the current valuation its appeal for investors who focus on earnings power. Explore the numbers behind South32's P/E valuation.
The South32 Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for South32 by explaining what would need to happen to future earnings, growth and margins for the current tag to look materially higher or lower over time, based on scenarios shared on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each narrative sets out the key elements behind its fair value view so you can track those assumptions against actual results as they emerge.
Community views on South32 are split between those who see the portfolio reshape creating more upside and those who think the current earnings already capture most of the value.
Bull case: roughly fairly valued
"Realized portfolio simplification and divestiture of lower margin, higher-risk coal assets refocus South32 on higher-return and future-facing commodities..."
Discover why this Narrative puts South32 at roughly fairly valued.
Bear case: 18% overvalued
"This assessment is based mainly on South32’s current operations and does not fully account for the proposed sale of its aluminium assets to Alcoa..."
Explore why this Narrative puts South32 at 18% overvalued.
One more thing about South32 that deserves your attention
South32’s valuation story only tells part of the picture, because separate checks have raised specific concerns that investors may want to weigh before getting comfortable with the overall risk profile. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com