
September 2026's Top Undervalued Small Caps With Insider Buying
The United States market has shown robust performance, climbing 2.5% in the last week and achieving a 14% increase over the past year, with earnings anticipated to grow by 18% annually in the coming years. In this dynamic environment, identifying small-cap stocks that are perceived as undervalued and exhibit insider buying can offer unique opportunities for investors seeking potential growth.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.2x | 0.4x | 36.57% | ★★★★★★ |
| Bank of Marin Bancorp | NA | 7.4x | 30.57% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.6x | 2.4x | 28.76% | ★★★★☆☆ |
| Shore Bancshares | 11.6x | 3.3x | 36.94% | ★★★★☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -39.62% | ★★★☆☆☆ |
| Citizens Community Bancorp | 16.3x | 3.6x | 9.31% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.7x | 2.6x | 9.04% | ★★★☆☆☆ |
| Hanover Bancorp | 20.4x | 2.8x | 35.25% | ★★★☆☆☆ |
| Orion Group Holdings | 101.5x | 0.4x | 46.04% | ★★★☆☆☆ |
| Surgery Partners | NA | 0.6x | 15.15% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Azenta (AZTA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Azenta specializes in providing multiomics and sample management solutions, with a market capitalization of approximately $3.55 billion.
Operations: Azenta generates revenue primarily from its Multiomics and Sample Management Solutions segments, with gross profit margins reaching up to 45.26%. Operating expenses, including R&D and general administrative costs, significantly impact financial outcomes.
PE: -13.4x
Azenta, a small U.S. company, has recently seen insider confidence with share repurchases totaling 2.3 million shares for US$50 million from April to June 2026. Despite higher-risk funding through external borrowing, the company's earnings are forecasted to grow significantly at nearly 110% annually. Recent leadership changes saw Dr. Martin Madaus stepping in as interim CEO, bringing extensive experience in diagnostics and life sciences tools. Revenue guidance for fiscal year ending September 2026 was slightly raised to US$613-618 million, indicating potential growth amidst industry challenges.
- Take a closer look at Azenta's potential here in our valuation report.
Explore historical data to track Azenta's performance over time in our Past section.
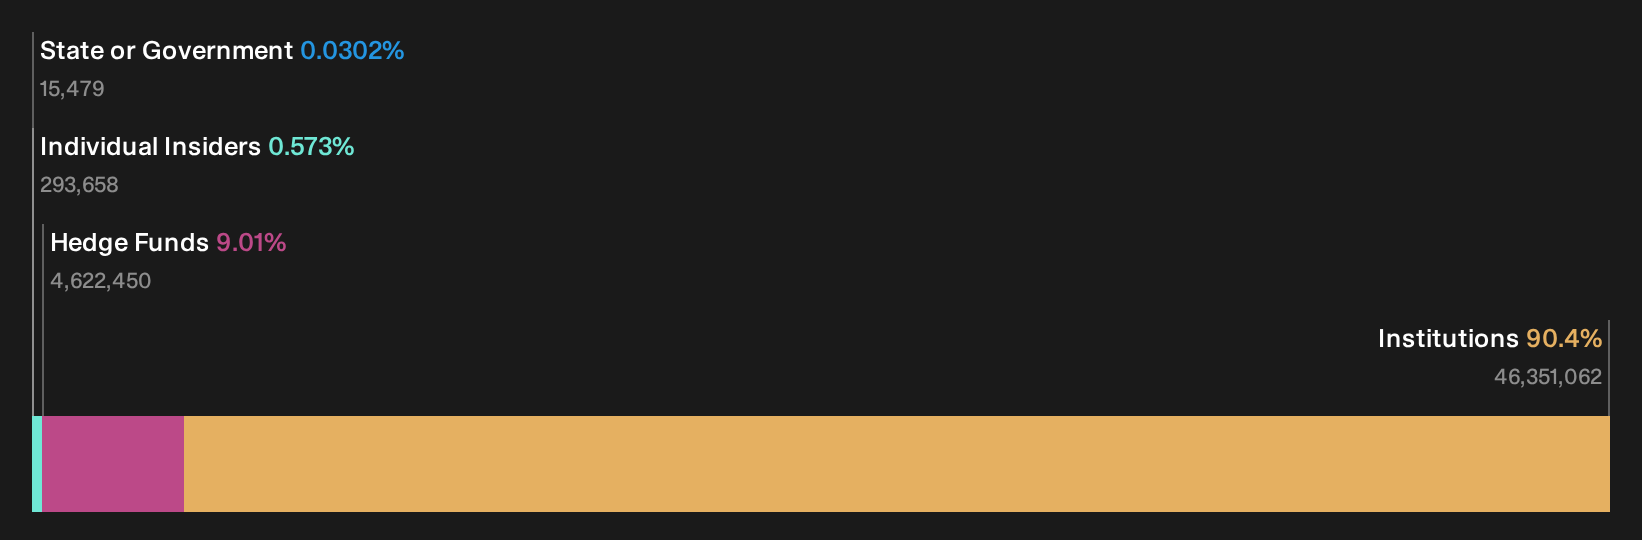
Surgery Partners (SGRY)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Surgery Partners operates surgical facilities, including ancillary services, and has a market capitalization of approximately $2.24 billion.
Operations: Surgical Facilities, including Ancillary Services, generate $3.37 billion in revenue. The gross profit margin stands at 22.51%, reflecting the cost of goods sold subtracted from total revenue before accounting for other expenses. Operating expenses and non-operating expenses further impact financial outcomes, with net income showing a loss of $88.6 million as of the latest period ending September 2026.
PE: -23.1x
Surgery Partners, a player in the ambulatory surgical center industry, is navigating through a challenging year with its strategic focus on optimizing its portfolio. Despite reporting a net loss of US$15 million for Q2 2026, revenue increased to US$848.9 million from US$826.2 million the previous year. The company remains committed to acquisitions and anticipates closing deals by year's end, although not reaching their US$200 million target due to disciplined M&A strategies amidst industry fragmentation. Insider confidence is reflected in ongoing acquisition discussions, highlighting potential growth avenues despite current financial hurdles.
- Dive into the specifics of Surgery Partners here with our thorough valuation report.
Examine Surgery Partners' past performance report to understand how it has performed in the past.

Enovis (ENOV)
Simply Wall St Value Rating: ★★★★★☆
Overview: Enovis is a company specializing in reconstructive and prevention and recovery medical solutions, with a market cap of approximately $2.65 billion.
Operations: The company generates revenue primarily through its Reconstructive and Prevention and Recovery segments, with recent figures showing $1.16 billion and $1.13 billion, respectively. Over time, the gross profit margin has shown an upward trend, reaching 61.32% in 2026 from earlier lower levels. The business incurs significant operating expenses, including general and administrative costs consistently above $900 million in recent periods.
PE: -1.0x
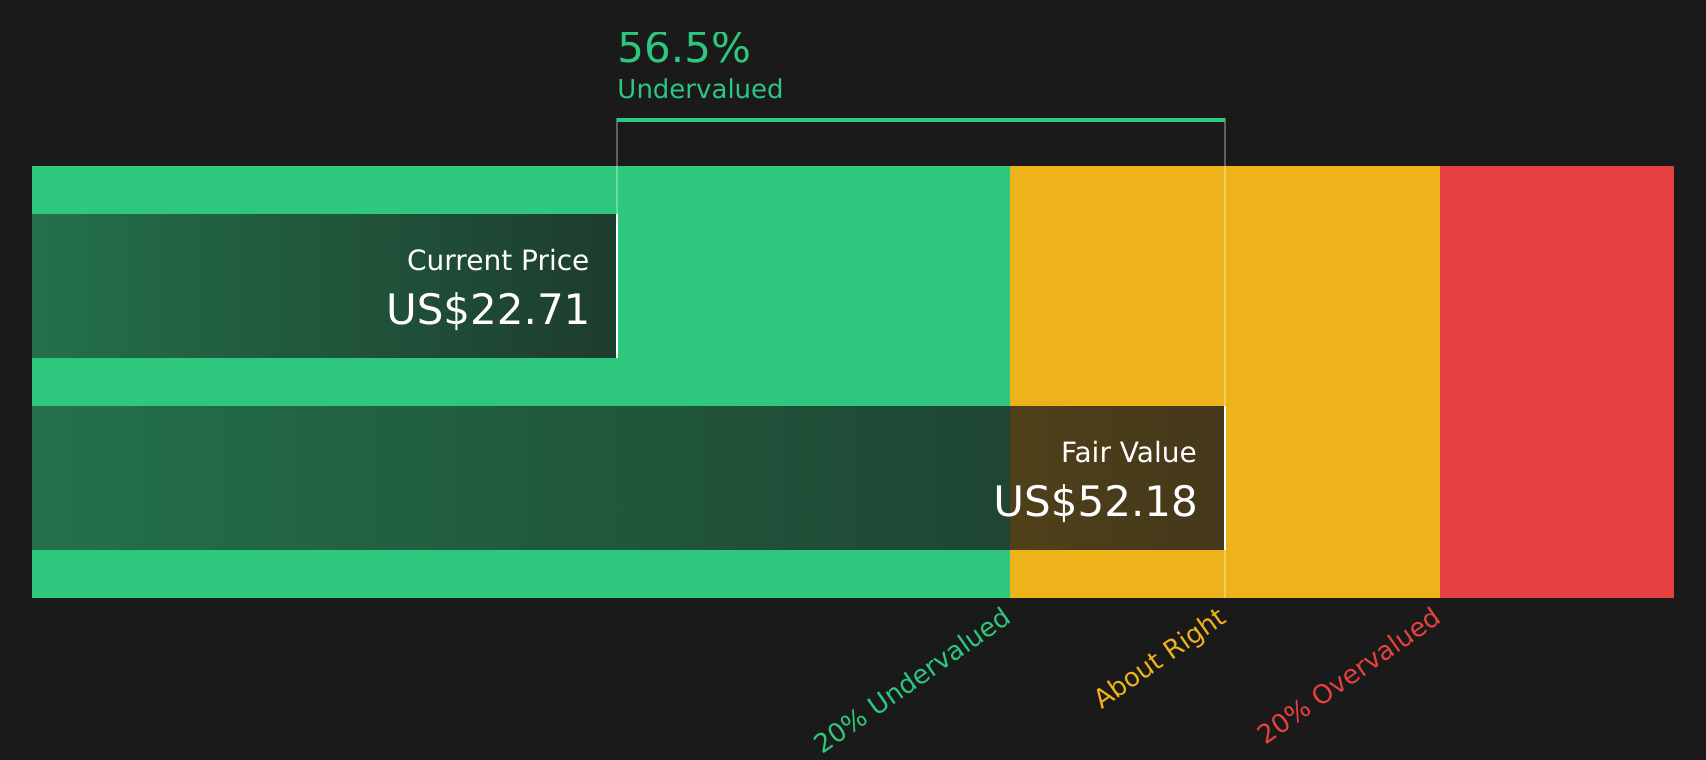
Enovis, a smaller player in the U.S. market, shows potential despite recent challenges. Their CEO demonstrated insider confidence by purchasing 13,035 shares valued at US$249,620 on September 1st, increasing their holdings by over 50%. The company's Q2 results reveal sales of US$582.78 million with a reduced net loss of US$1.19 million compared to last year’s US$36.74 million loss. While external borrowing remains their sole funding source, earnings are projected to grow significantly at 138% annually. Recent product launches in veterinary laser therapy could bolster future revenue streams and enhance market positioning amidst industry volatility and index exclusions.
- Navigate through the intricacies of Enovis with our comprehensive valuation report here.
Assess Enovis' past performance with our detailed historical performance reports.
Next Steps
- Dive into all 65 of the Undervalued US Small Caps With Insider Buying we have identified here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com