
Why Omnicell (OMCL) Shares Moved And What Investors Are Watching
Omnicell (OMCL) has been drawing fresh attention after recent share price moves, with the stock last closing at $33.17. Investors are weighing this valuation against mixed recent returns and the company’s healthcare technology footprint.
Recent trading shows a small rebound, with a 1-day share price return of 2.28% and a 7-day share price return of 1.65%. However, this sits against a 30-day share price return that declined 6.77% and a year-to-date share price return that fell 26.52%. The 1-year total shareholder return of 7% contrasts with weaker 3- and 5-year total shareholder returns, suggesting short term momentum is trying to turn after a tougher multi year stretch for Omnicell.
Compare Omnicell’s recent swings with a curated list of solid balance sheet and fundamentals (23 results) that may offer a different blend of resilience and recovery potential.
Omnicell’s rebound to $33.17 after a difficult stretch puts you at a crossroads. Should you lean into the recent uptick now, or wait and see what the valuation looks like first?
Most Popular Narrative: 46% Undervalued
On the most followed view of Omnicell, a fair value of about $61.29 sits well above the recent $33.17 close. This frames the current debate around how much of the long term story is already in the price.
The continued rollout and adoption of the cloud-native OmniSphere platform across Omnicell's customer base will simplify enterprise-wide medication management, make adding new features and integrating advanced analytics much easier, and accelerate the company's transition to higher-margin, recurring SaaS-based revenues, supporting improved revenue predictability and net margins.
See why 7 investors see Omnicell as 46% undervalued.
Result: Fair Value of $61.29 (UNDERVALUED)
Still, Omnicell’s story can unravel if tariff costs squeeze margins more than expected, or if hospital capital budgets tighten and delay cabinet upgrades.
Find out about the key risks to this Omnicell narrative.
Another View: Omnicell Through The Earnings Lens
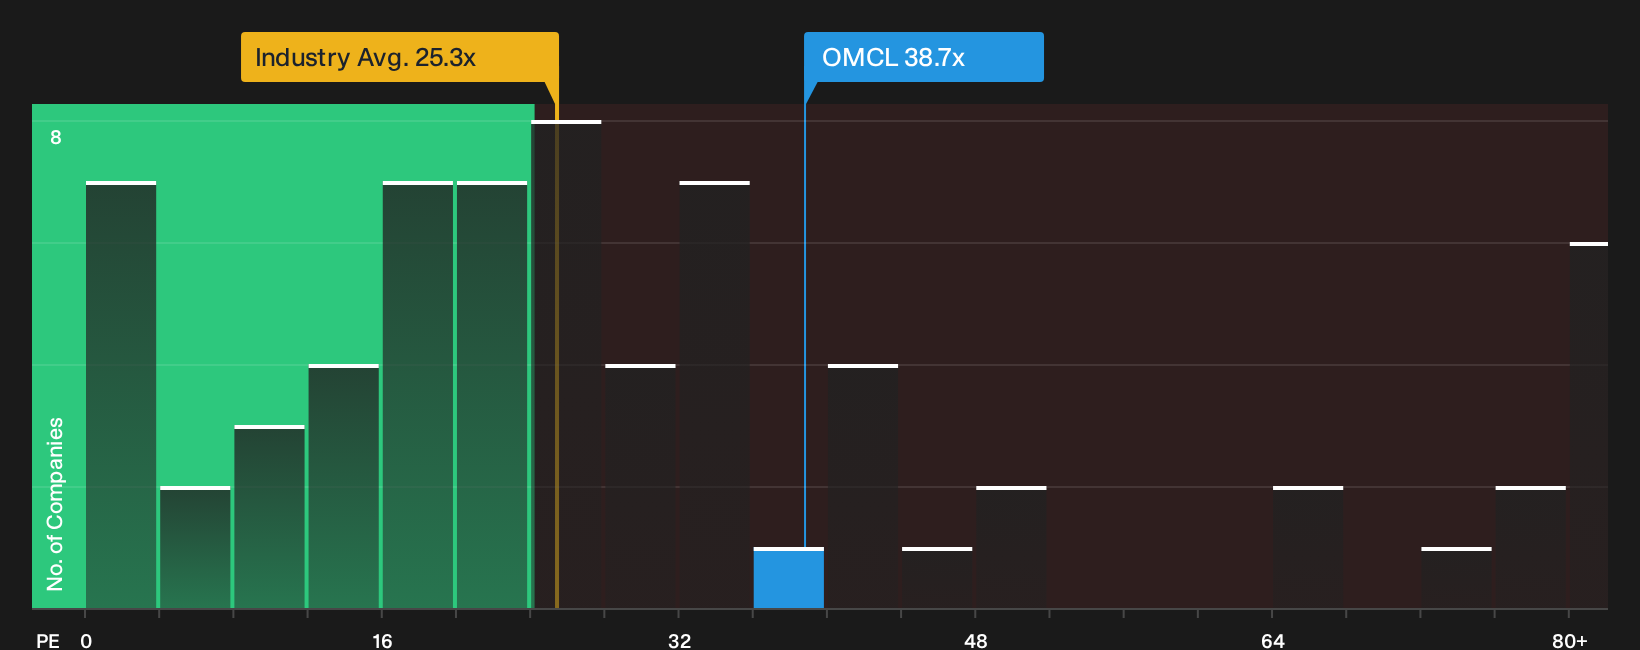
The first fair value story portrays Omnicell as undervalued, yet the current pricing on earnings presents a tougher perspective. At a P/E of 38.7x compared with the US Medical Equipment sector at 25.1x and a fair ratio of 28.2x, the stock carries a richer tag that may limit room for error.
That gap indicates investors are already paying a higher price for future delivery, so any setback in execution or margins could affect returns more quickly than a pure discount story suggests. The key question is whether you are comfortable paying a premium today for a company that is still rebuilding its longer term record.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity, the Omnicell picture is only complete once you have tested the numbers yourself and weighed the trade offs. If you want a quick snapshot of what the market currently likes about the business, take a look at the 4 key rewards.
Looking for more Omnicell style investment ideas?
Do not stop your research with Omnicell. Use the Simply Wall St Screener to quickly surface fresh ideas that match the kind of risk and return profile you actually want.
- Chase value opportunities by scanning a curated set of companies that screen well on quality and valuation through the 29 high quality undervalued stocks.
- Prioritise resilience by hunting for businesses with strong balance sheets and fundamentals using the targeted list of solid balance sheet and fundamentals (23 results).
- Get ahead of the crowd by reviewing a focused group of under the radar stocks with solid fundamentals using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com