
Dear McDonald’s Stock Fans, Mark Your Calendars for September 23
McDonald's (MCD) remains one of the restaurant industry’s most recognizable and globally scaled brands, with more than 45,000 locations across over 100 countries. However, softer domestic demand has weighed on the stock, with shares down about 18% year-to-date (YTD).
That performance has intensified the focus on McDonald’s ability to reignite domestic traffic while sustaining the momentum of its international growth engine. The spotlight could sharpen further on Wednesday, Sept. 23, when the company is scheduled to host its Investor Day.
Management is expected to offer greater detail on its “McDonald’s NEXT” strategy, including longer-term targets, restaurant development, remodel spending, capital allocation, menu innovation and franchisee economics. The company is also expected to outline plans to revive stalled U.S. momentum while sustaining international growth.
McDonald’s beverage platform is expected to be another area of interest. In last year’s annual report, the company described beverages and desserts as a more than $100 billion global opportunity and highlighted its efforts to expand offerings across U.S. and international markets.
Hence, management’s outlook on traffic, investment, and cash flow will carry added importance. The company’s targets could provide investors with greater visibility into the path ahead.
About McDonald's Stock
McDonald's is among the world’s best-known fast-food companies, selling burgers, chicken, fries, breakfast items, desserts, coffee, and beverages through restaurants across numerous countries.
Headquartered in Chicago, the company operates through a combination of company-owned and franchised restaurants, relying on conventional franchises, developmental licenses, and affiliated structures around the world.
The fast-food giant currently commands a market cap of about $177 billion. Yet that enormous footprint has not translated into equally impressive stock performance. McDonald’s shares have plummeted 17% over the last 52 weeks and are down 7% over the past three months.
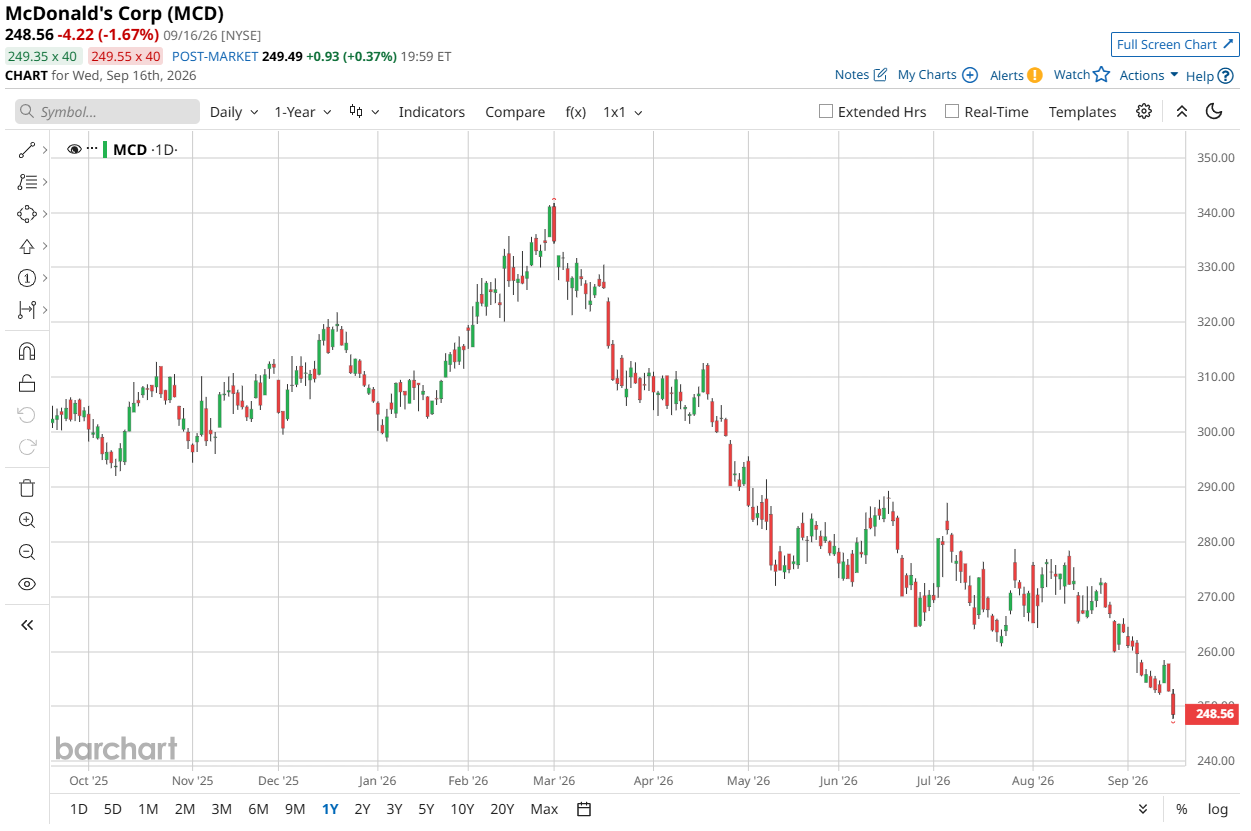
From a valuation standpoint, MCD stock is currently trading at 19.56 times forward adjusted earnings and 6.34 times sales. Both multiples remain above the industry average, but they are also below their own five-year average multiples. For long-term investors, that relative discount could make the current valuation worth a closer look.
Furthermore, the almost Dividend King has increased its dividend for 49 consecutive years and currently pays an annual dividend of $7.44 per share, translating into a 2.94% yield. Its most recent dividend of $1.86 per share was distributed on Wednesday, Sept. 16, to shareholders of record as of Tuesday, Sept. 1.
A Closer Look at McDonald's Q2 Earnings
McDonald’s posted mixed Q2 2026 results on Aug. 4, with earnings growth holding up despite weaker underlying sales momentum. Total revenue rose 3.7% year-over-year (YOY) to $7.1 billion, helped by higher franchised revenues and restaurant-level sales growth. Even so, revenue came in slightly below the Street estimate of $7.13 billion.
The U.S. remained the biggest drag on topline performance. Comparable sales increased 0.8% YOY, with higher average check and a favorable product mix providing support. Those gains were partially erased by declining comparable guest counts, highlighting continued pressure on consumer traffic and perceptions of value.
International markets, by contrast, delivered a stronger performance. Comparable sales climbed 1.5% YOY in International Operated Markets, led by Germany, Australia and the U.K. International Developmental Licensed Markets posted comparable sales growth of 1.9% YOY, driven by Japan.
Profitability remained healthy despite the modest pace of sales growth. Operating income rose 3.3% from the year-ago value to $3.3 billion, while non-GAAP net income increased 5.1% from the last year’s quarter to $2.4 billion. Meanwhile, adjusted EPS climbed 6% YOY to $3.38, beating the Street estimate of $3.32.
McDonald’s also adjusted its restaurant-development timeline. Management has moved its goal of reaching 50,000 restaurants globally to 2028 from 2027, pointing to a pressured consumer environment and cumulative inflation in development costs.
Still, the company remains on track to open approximately 2,600 gross restaurants in 2026, keeping it in what management describes as its fastest restaurant expansion phase.
On the other hand, analysts expect Q3 FY2026 EPS to increase 5.3% YOY to $3.39. For full-year FY2026, they project bottom-line growth of 5.5% from the previous year to $12.87, while their FY2027 estimates call for 8% growth from last year to $13.90.
What Do Analysts Expect for McDonald's Stock?
BTIG analyst Peter Saleh maintains a “Buy” rating on MCD stock with a $350 price target. His view is supported by confidence in McDonald’s franchise-driven earnings resilience, continued digital and loyalty momentum, and expectations that operational improvements in the United States can help reaccelerate traffic and support multiple expansion.
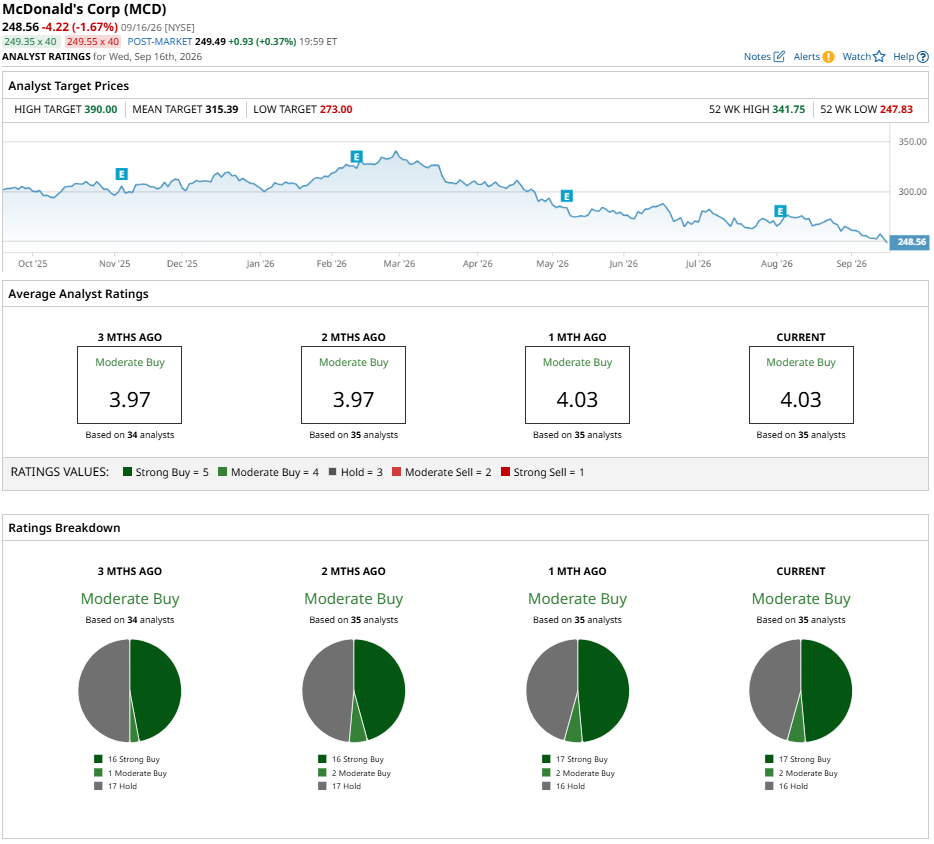
Wall Street’s broader assessment is also leaning bullish, with McDonald’s carrying an overall rating of “Moderate Buy.” Of the 35 analysts covering the name, 17 recommend “Strong Buy,” two recommend “Moderate Buy,” and 16 suggest “Hold.”
To that end, the stock’s average price target of $315.39 represents potential upside of 26.9%. Meanwhile, the Street-high target of $390 suggests a gain of 56.9% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.