
Sunrun (RUN) Stock Looks Cheap Based On Its Current Earnings
Sunrun has seen its share price fall sharply over the past few years, which puts the spotlight squarely on what investors are paying for its earnings today. With the stock changing hands at US$8.79 at the last close, the key issue is whether that price lines up with what the business is currently generating in profit terms.
- Over the past 5 years the share price has declined 79.5%, which raises a direct question about how the market now values Sunrun's earnings power.
- As a capital intensive residential solar operator that relies heavily on financing, the timing and reliability of future profits and cash flows can have a significant influence on what investors are prepared to pay for each dollar of earnings.
- The analysts covering Sunrun have run their own numbers. See what analysts think Sunrun's shares could be worth.
The issue now is whether Sunrun's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing Sunrun against other opportunities that are also being assessed on valuation grounds, it can help to compare it with a wider group of 29 high quality undervalued stocks.
Is Sunrun a Bargain on Earnings?
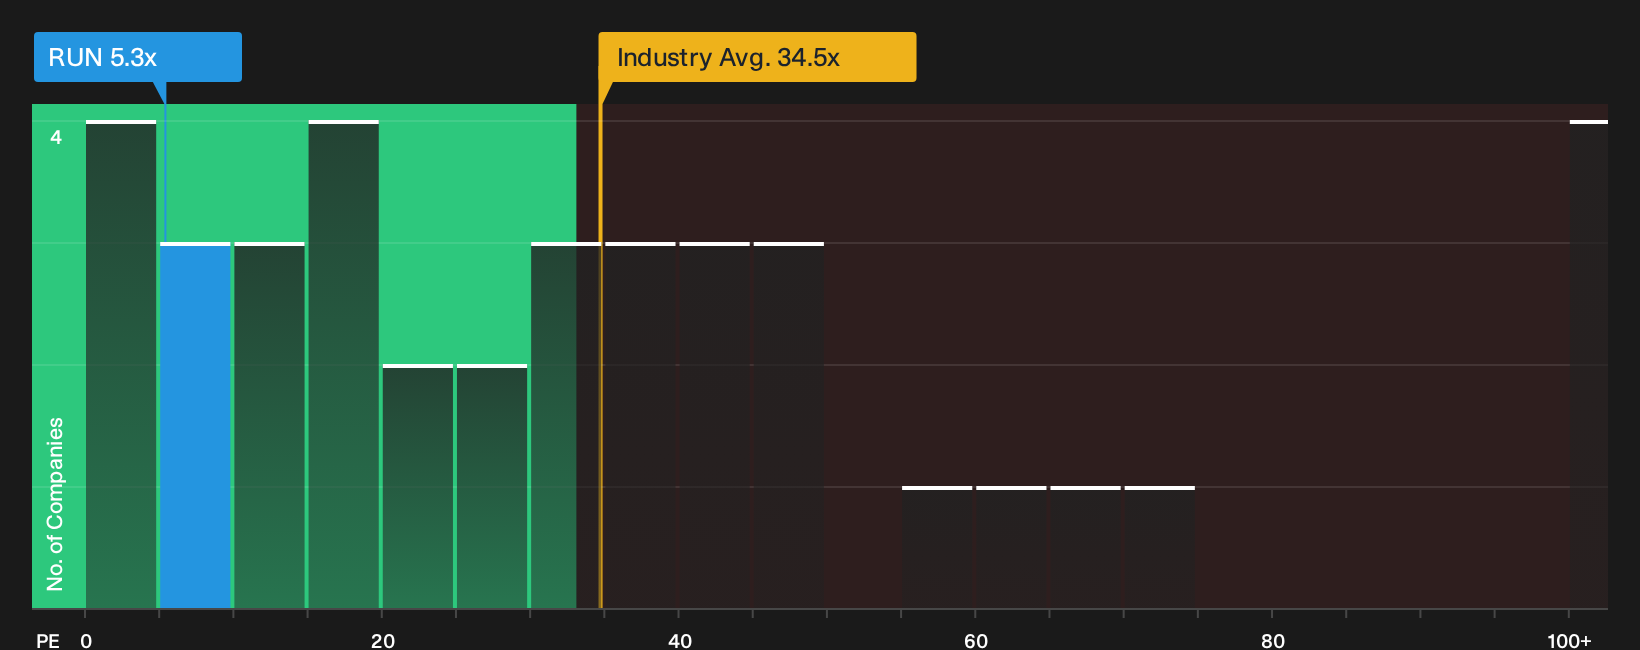
The P/E ratio fits Sunrun because earnings are the anchor for what investors are paying today, not what might happen far down the line. On this yardstick, Sunrun trades at about 5.3x its recent earnings. That is far below the Electrical industry average of roughly 34.5x and also lower than the peer group average of about 41.7x.
The Fair Ratio, which reflects what you might expect for a business with Sunrun’s mix of growth prospects, profit profile, scale and risk, sits above the current P/E. That gap implies the stock is pricing in a weaker earnings story than this tailored benchmark would suggest. For anyone assessing Sunrun, the key question is whether the risks around its capital intensive model and financing needs justify such a low earnings multiple or whether the discount points to potential mispricing. Explore the numbers behind Sunrun's P/E valuation.
The Sunrun Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation puzzle leaves off and explain what mix of future growth, margins and earnings would need to unfold for Sunrun to be worth materially more or less than today’s price. Each one links its number to a clear view on where Sunrun's scale, profitability and risk profile could head next. You can then revisit these views as fresh information on the business comes through.
One of the top community narratives on Sunrun: 54% undervalued
"Sunrun (NASDAQ: RUN) operates at the intersection of two powerful forces: the long-term push toward clean energy and the short-term reality of higher interest rates."
Discover why this Narrative puts Sunrun at 54% undervalued.
Sunrun's price is only one clue, not the whole investment story
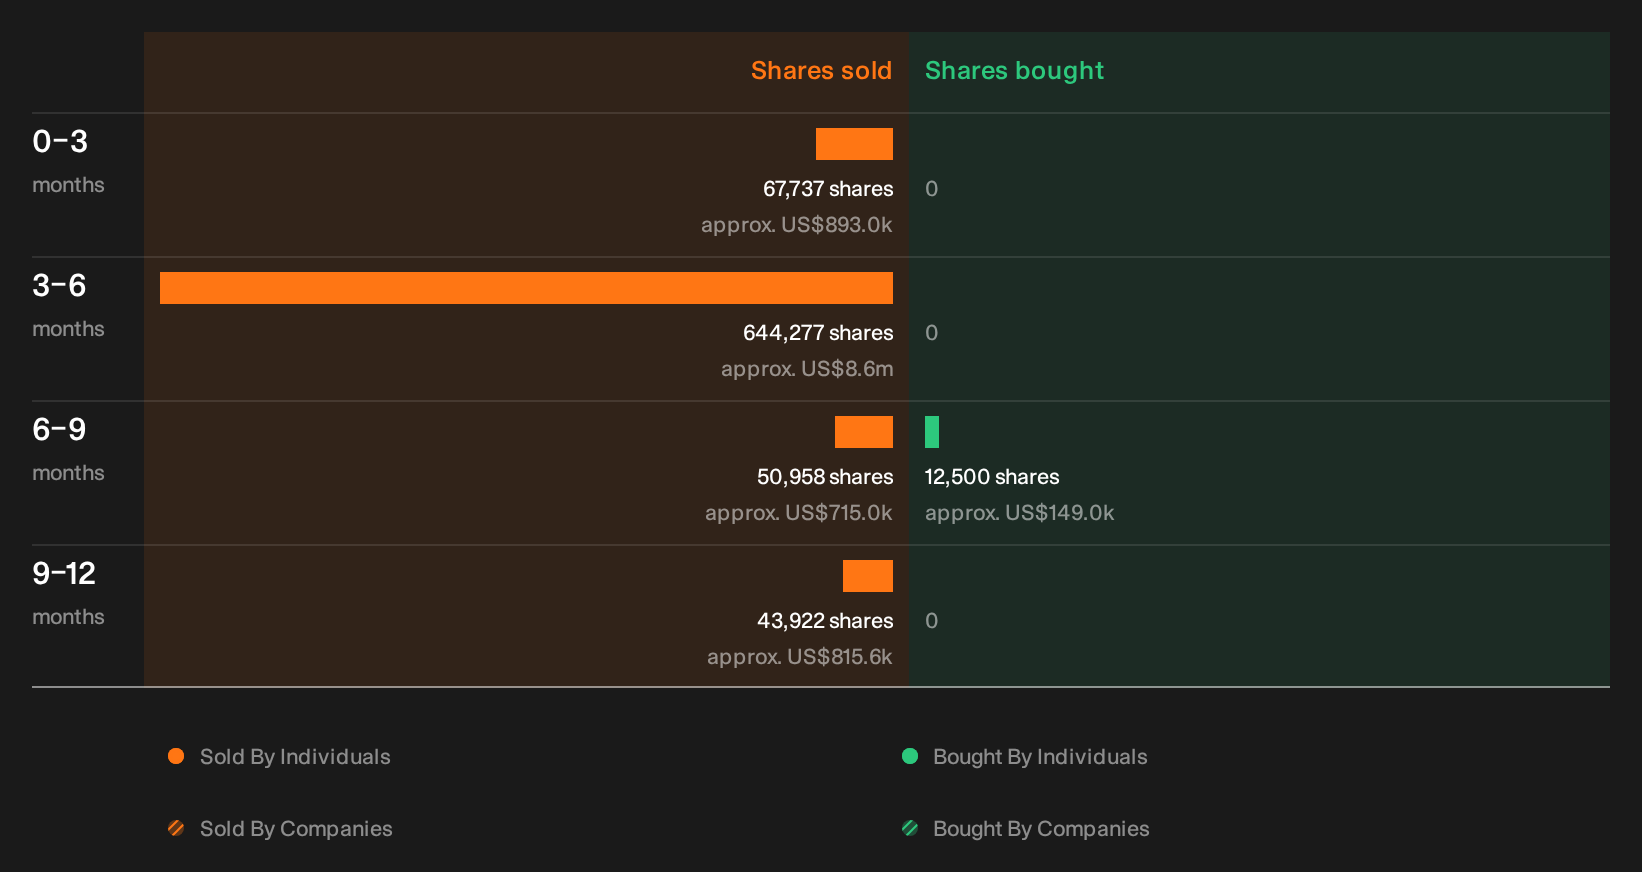
Valuation only tells you what the market is paying today. Our checks also point to recent moves by Sunrun insiders, and the specific sellers, volumes and possible read-throughs are the missing piece you still need to explore. See the recent insider selling flagged for Sunrun.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com