
Alten (ENXTPA:ATE), Why Is It Getting Fresh Attention?
Alten (ENXTPA:ATE) has drawn fresh attention after recent price moves left the stock down about 7% over the past month but up roughly 31% in the past 3 months. Investors are reassessing what that swing implies for valuation and expectations.
That recent pullback follows a stronger upswing, with Alten’s share price delivering a 31.3% return over the past 3 months and a 7.99% total shareholder return over the past year. This points to momentum rebuilding after a weaker multi year stretch.
Spot 619 high quality undiscovered gems that share Alten’s consulting and engineering profile but are still flying under most investors’ radar.After a 31.3% three month rebound and a longer three year period where total return declined 38.4%, Alten now sits at an awkward middle ground. Is the meaningful upside already captured, or does valuation still offer room?
Most Popular Narrative: 26% Undervalued
On the most followed view, Alten’s fair value sits at €96 per share, comfortably above the last close of €71.05. This puts attention squarely on whether the underlying project pipeline and margins can support that gap.
The anticipated project reinitiations in the automotive and aerospace sectors, particularly in Europe and the U.S., could lead to improved revenue growth once these postponed projects commence, impacting Alten’s future top-line. Successful acquisitions, as evidenced by headcount increases from acquisitions, indicate potential revenue synergies and long-term earnings growth as these acquisitions are integrated and start contributing to the bottom line.
See why 7 investors see Alten as 26% undervalued.
The narrative uses a 9.18% discount rate to bring those future cash flows and earnings back into today’s terms, then pairs that with a target P/E of about 16.8x on projected earnings. That framework produces a fair value of €96, which implies Alten is trading at a meaningful discount if those revenue and margin assumptions hold and if postponed sector projects in areas like automotive and aerospace do restart as expected.
Result: Fair Value of €96 (UNDERVALUED)
Still, Alten’s story can unravel if postponed automotive and aerospace projects are cancelled outright, or if weak demand outside France keeps pressure on profitability and organic growth.
Find out about the key risks to this Alten narrative.
Another View: Alten Through The Market’s Lens
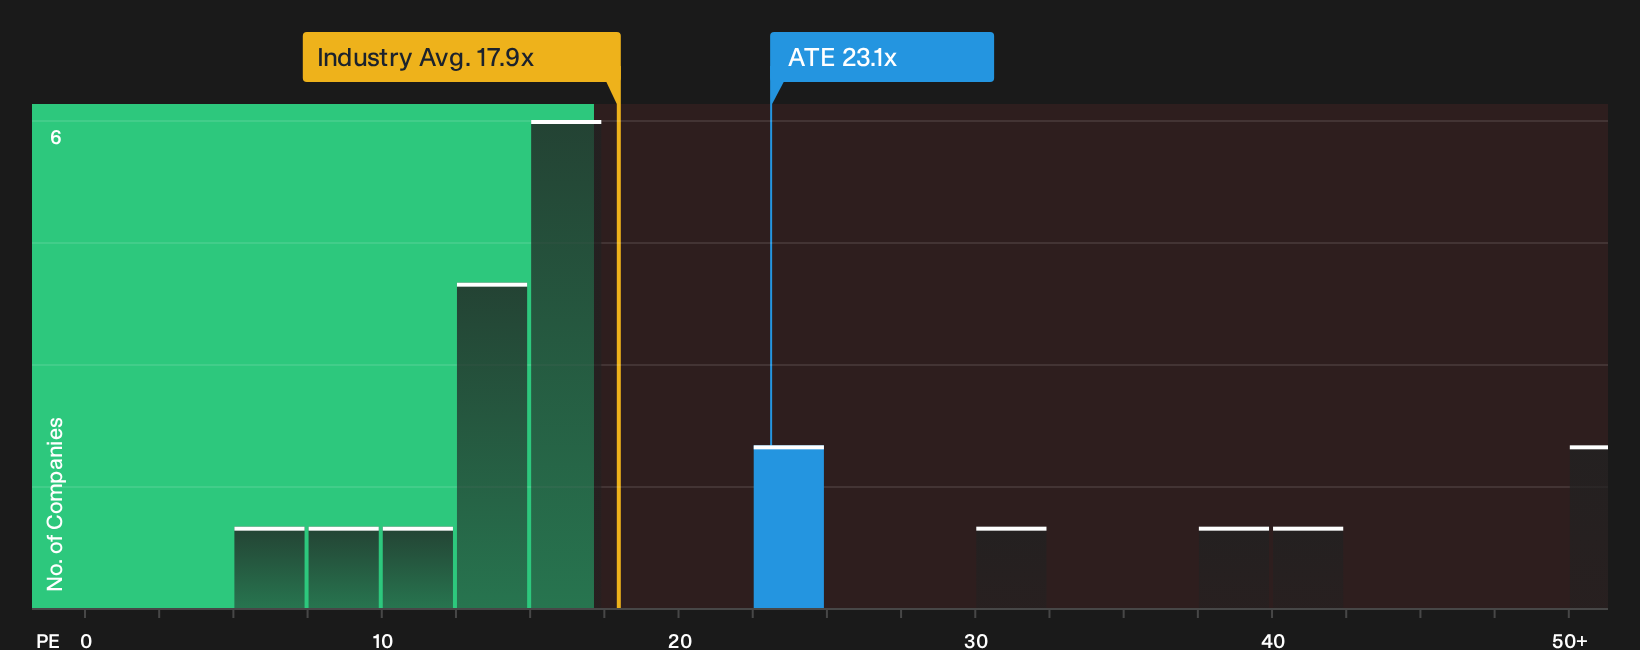
The first story on Alten leans heavily on future cash flows and analyst forecasts. The current market message is different. At a P/E of 23.1x, the stock trades far above European IT peers at 18.1x and its own fair ratio of 29.3x. This suggests both upside potential and clear valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed mood around Alten matches your own read of the situation? Take a few minutes to review the key data points and weigh both sides of the argument, then check the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Alten?
Alten’s story is only one angle. Broaden your watchlist with a few focused ideas that match different risk levels and return goals using the Simply Wall Street screener.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (198 results) that can help anchor a portfolio when sentiment shifts.
- Hunt for quality at a discount by reviewing the 175 high quality undervalued stocks that pair strong financial profiles with prices that may not yet reflect their fundamentals.
- Dial back risk while staying invested by filtering for the 229 resilient stocks with low risk scores that score well on financial strength and volatility measures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com