
Principal Financial Group (PFG) Stock Could Look Rich Despite Strong Earnings Backing
Principal Financial Group has delivered a strong ride for long term holders, which naturally raises a question for anyone looking at the stock today. With that backdrop, the issue now is whether the current share price is properly supported by the earnings that underpin the business.
- Over the past 5 years, Principal Financial Group has returned 106.6%, which puts real weight on whether the underlying earnings profile can carry that kind of share price performance.
- The group leans heavily on fee based income and insurance underwriting, so the durability of those profit streams and how efficiently they convert into cash can shape what investors are willing to pay for each dollar of earnings.
- The analysts covering Principal Financial Group have run their own numbers. See what analysts think Principal Financial Group's shares could be worth.
The stock's next move may depend on whether Principal Financial Group's current earnings level and quality make the recent valuation multiples look sensible at today's price.
If you are weighing Principal Financial Group against other earnings focused opportunities, it can help to compare it with a wider set of 29 high quality undervalued stocks.
Does Principal Financial Group Look Pricey on Earnings?
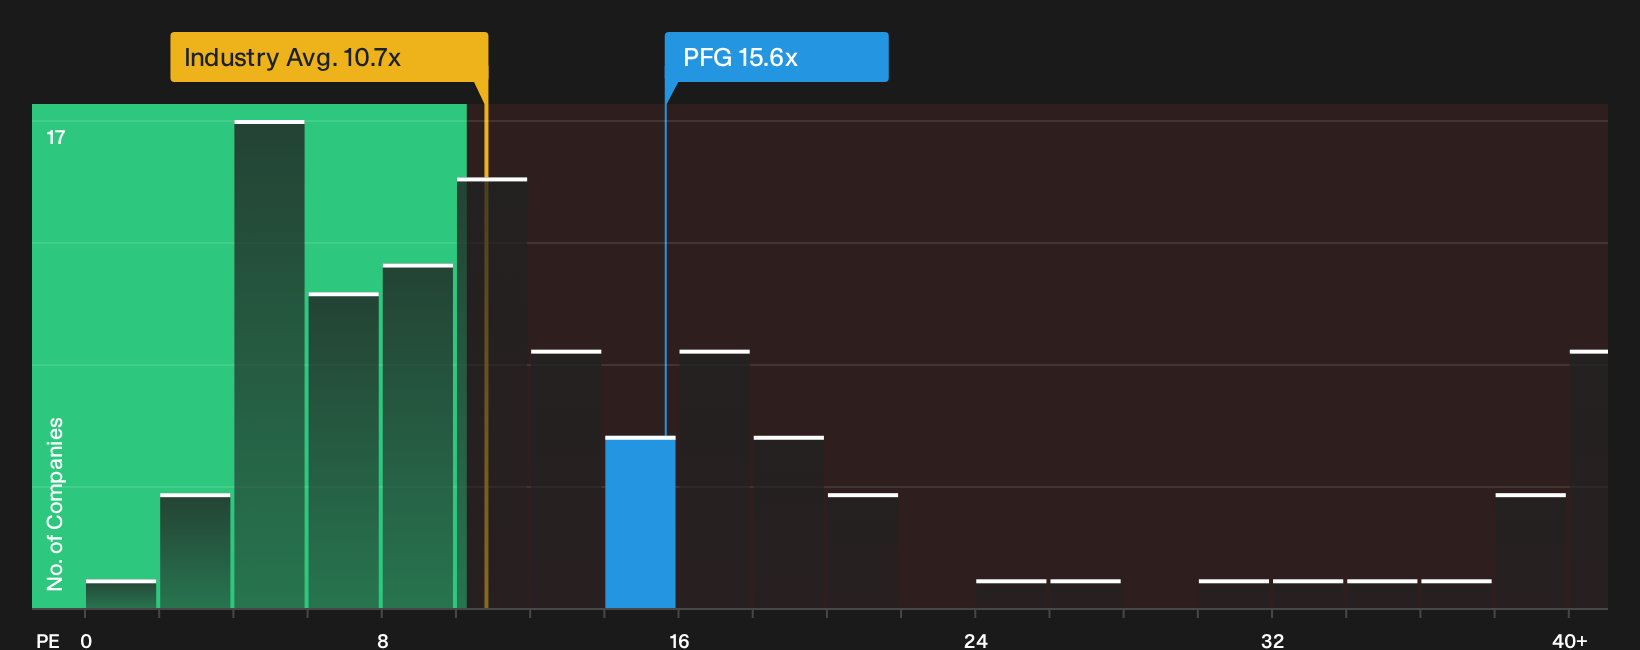
P/E fits Principal Financial Group because earnings are the main anchor for how investors usually think about insurers. The current P/E of 15.6x sits a little above the peer average of 15.0x and well above the broader Insurance group on 10.7x. That points to the market paying a richer tag for each dollar of Principal Financial Group earnings than for many sector alternatives.
The in house fair multiple, which blends the company’s forecast profitability, growth profile and risk, comes in below where the stock trades today. Since the current 15.6x P/E is higher than that tailored yardstick, the shares screen overvalued on this metric compared with what those fundamentals might support. For anyone weighing Principal Financial Group against other insurance stocks, the key question is whether its earnings quality and stability justify paying that premium P/E. Explore the numbers behind Principal Financial Group's P/E valuation.
The Principal Financial Group Narrative: What Would Justify Today's Price?
Narratives for Principal Financial Group pick up where the P/E puzzle leaves off and spell out which future paths for growth, margins and earnings would need to play out for the current share price to look materially higher or lower. Each scenario lays out its own set of underlying assumptions rather than a single multiple or model result, so you can compare those expectations with the actual numbers as they arrive on Simply Wall St's Community page.
Community views on Principal Financial Group split around how durable its fee income and margins really are from here.
Bull case: 9% undervalued
"Continued investment in digital infrastructure, including AI-powered productivity tools, is expected to yield long-term improvements in customer engagement, cost efficiency, and operating leverage..."
Discover why this Narrative puts Principal Financial Group at 9% undervalued.
Bear case: 21% overvalued
"Market volatility is expected to persist, making upcoming quarters more difficult to predict, which could negatively impact fee revenue in retirement and asset management..."
Explore why this Narrative puts Principal Financial Group at 21% overvalued.
One more factor on Principal Financial Group before you make a move
Valuation tells you what the market is paying today, but the set of professional expectations for where Principal Financial Group could be a few years from now offers a different lens to compare with those numbers. Explore where analysts expect Principal Financial Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com