
QuinStreet (QNST) Stock Could Be A Bargain After Strong Earnings
QuinStreet shares have swung sharply in recent years, which puts a spotlight on whether the current US$15.28 price is really supported by the company’s earnings power. With fresh earnings news still in view, the issue for investors is how much of that story is already reflected in the valuation.
- Over the past 3 years, QuinStreet has delivered a 69.8% gain, so anyone looking at the stock today is effectively being asked to pay up for a very different earnings profile than in 2021.
- Recent revenue growth and a positive reaction to the latest earnings update can support expectations for stronger profitability, which matters a lot for how much investors are willing to pay per dollar of earnings.
- There is a second opinion on QuinStreet worth weighing. See what analysts think QuinStreet's shares could be worth.
The stock's next move may depend on whether QuinStreet's recent earnings justify the multiple investors are currently paying at around US$15.28 a share.
If you want more context around QuinStreet's valuation story, a focused screen such as 29 high quality undervalued stocks can be a useful next step in your research.
Does QuinStreet Look Undervalued on Earnings?
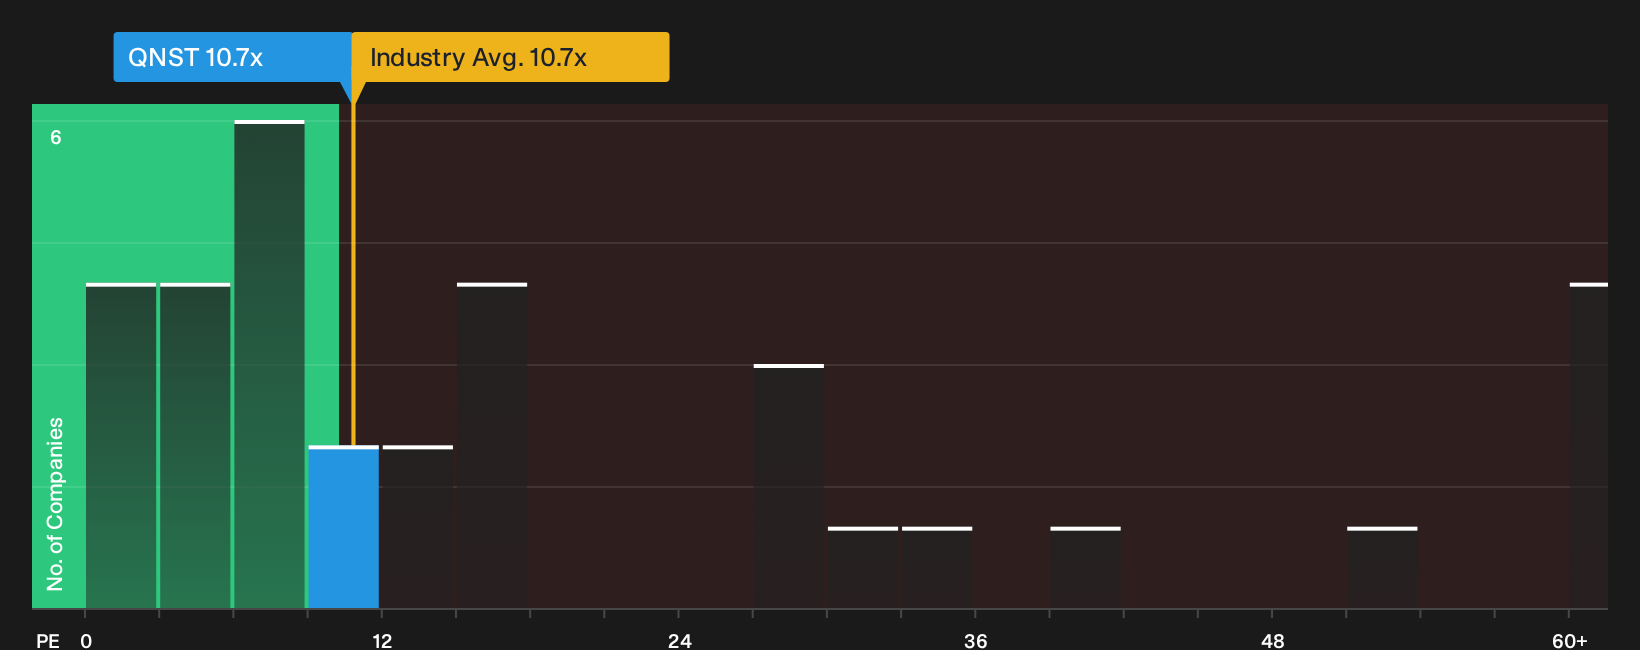
The P/E ratio suits QuinStreet because the company is already generating earnings and investors are clearly watching what they are paying for each dollar of profit. At roughly 10.7x earnings, QuinStreet trades close to the broader interactive media and services average of about 10.7x, yet meaningfully above the peer group around 6.9x. That mix suggests the market is valuing the business in line with the wider sector, while still assigning a premium to this stock versus more direct comparables.
Because the current multiple sits below the level suggested by a more tailored fair-value model that factors in QuinStreet’s growth profile, profitability and risk, the shares screen as undervalued on this framework. The strong Q2 beat on revenue and EPS, plus raised guidance and the share price reaction, has improved sentiment. However, the P/E still leaves the stock at a discount to what that model implies could be justified. Explore the numbers behind QuinStreet's P/E valuation.
The QuinStreet Narrative: What Would Justify Today's Price?
Narratives on QuinStreet pick up where the valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one frames fair value as a thesis about how QuinStreet's business might play out over time, so you can watch whether that story holds up as new information comes through on the Community page.
One of the top community narratives on QuinStreet: 28% undervalued
"Heavy investment in proprietary technology, AI-driven platforms, and diversification of traffic sources enhances targeting, conversion, and operational efficiencies..."
Discover why this Narrative puts QuinStreet at 28% undervalued.
QuinStreet's valuation raises a final question about where this business could be a few years from now
Analyst projections give you a separate reference point to compare with today’s price, offering a view on future earnings power without proving it will be strong or weak. Explore where analysts expect QuinStreet to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com