
How Investors Are Reacting To Kratos Defense & Security Solutions Stock Ignites Cruise Missile Engine
- Kratos Defense & Security Solutions and GE Aerospace reported the successful ignition of the GEK800, now designated F143, turbofan cruise missile engine at the X-58 facility. The test phase achieved a 100% success rate and kept the long range, stand off propulsion program on schedule.
- The GEK800 milestone highlights Kratos' push to pair affordable manufacturing with complex propulsion technology. The company is aiming to support large volume production for future long range cruise missile demand and allied procurement programs.
- This article will examine how Kratos' investment narrative around unmanned systems and propulsion is shaped by the GEK800 ignition milestone.
Kratos Defense & Security Solutions Investment Narrative Recap
To own Kratos Defense & Security Solutions, you need to believe that unmanned systems, missile propulsion, and software driven defense gear can scale from programs into sustained production. The F143 ignition milestone fits that thesis because it keeps a flagship propulsion effort on track. This matters for keeping customer confidence high and program timelines intact.
The key near term swing factor still sits in how quickly funded programs convert into cash generation rather than just backlog and inventory. Execution risk around heavy CapEx and working capital does not disappear with this test result. The biggest worry remains contract timing and supplier reliance, not this single engine milestone.
The most relevant recent development is the earlier focus on Kratos Defense & Security Solutions as a beneficiary of rising unmanned and drone defense demand after high profile infrastructure attacks. That theme goes directly to why the F143 matters. It ties propulsion know how to practical long range strike and counter drone ecosystems.
For you as an investor, the thread between those drone defense narratives and this propulsion update is program follow through. Progress on GEK800 reduces technical risk on one pillar of that story, while funding concentration, supply chain leverage, and the pace of production ramp remain unresolved. The near term test is execution, not new headlines.
Kratos Defense & Security Solutions is framed around analyst expectations that revenues could reach $3.0b and earnings $189.5m by 2029, built on a forecast 24.7% yearly revenue growth rate and an earnings move of about 6x from $30.9m today to that 2029 consensus figure.
Uncover why Kratos Defense & Security Solutions' fair value indicates a 125% potential upside to its current price, which could narrow quickly.
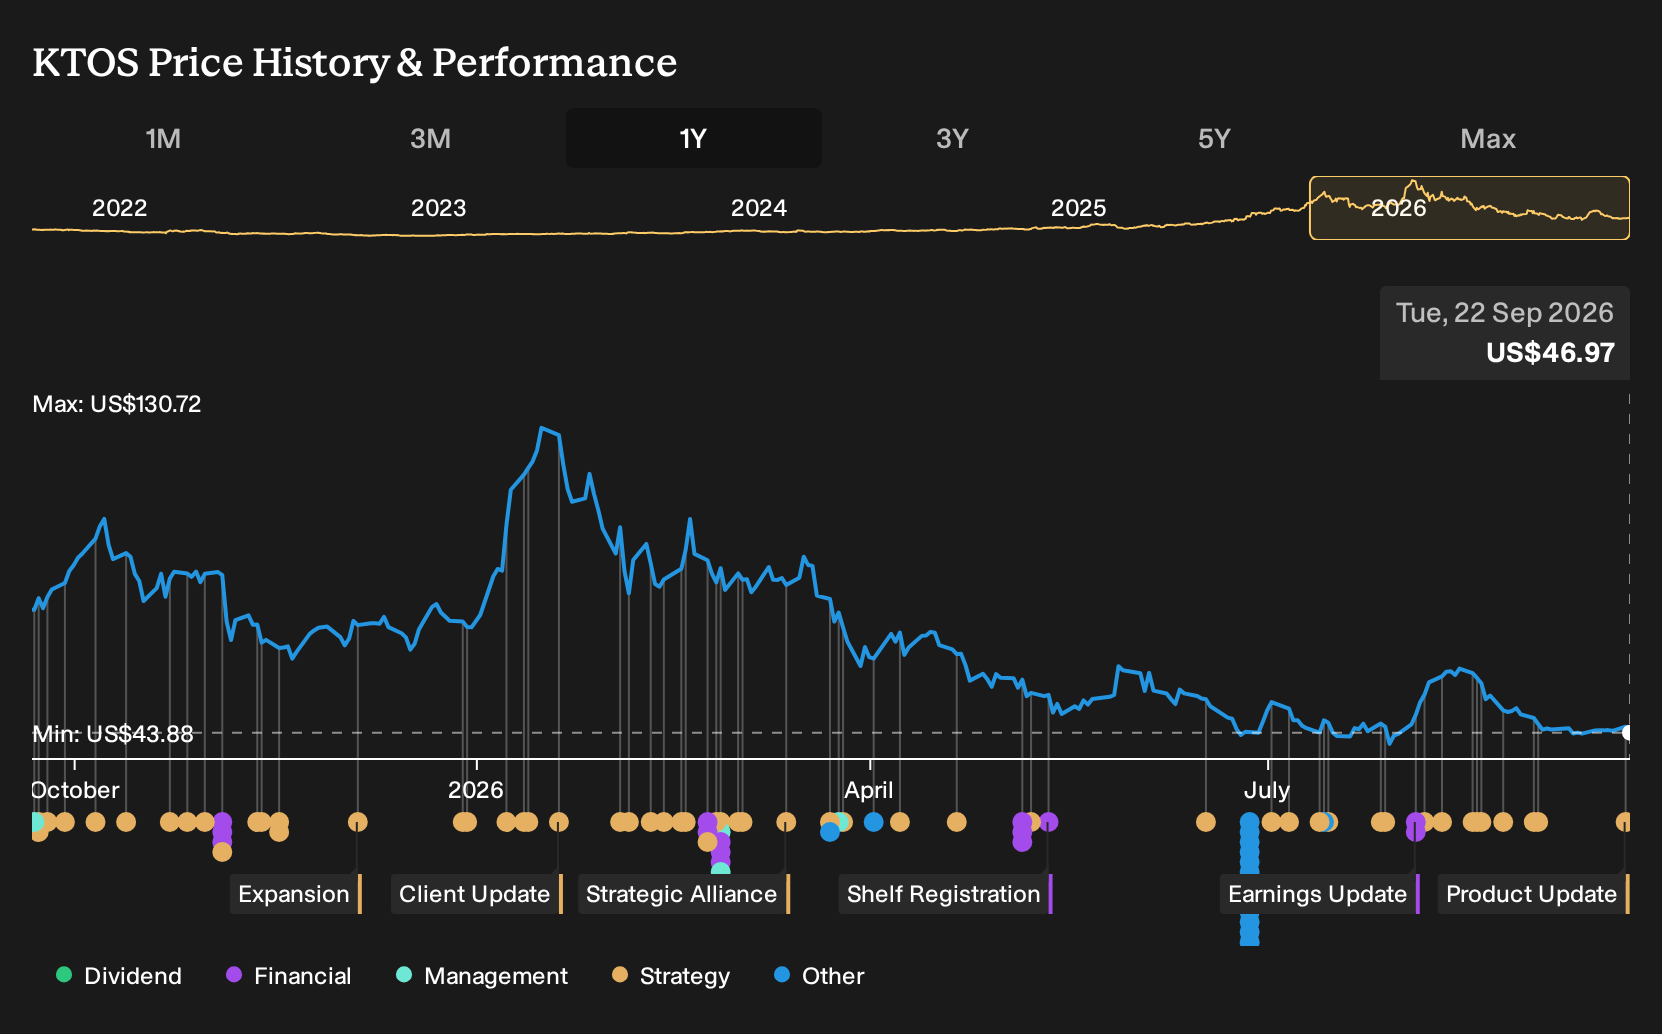
Exploring Other Perspectives
One alternate take on Kratos Defense & Security Solutions focuses on budget risk rather than technology milestones. In that view, tighter U.S. spending and export controls could cap the opportunity, which is why the lowest analysts were only penciling in about US$2.6b of 2029 revenue and US$115.0m of earnings. These more cautious forecasts, set before the F143 ignition news, show how far opinions can stretch. Use this new test result as a prompt to compare both narratives and decide which assumptions you find more realistic.
Explore 6 other Kratos Defense & Security Solutions fair value estimates, including one that indicates as much as 16% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kratos Defense & Security Solutions' overall financial health at a glance.
Looking for more Kratos Defense & Security Solutions style investment ideas?
If the Kratos Defense & Security Solutions story has you thinking about where else defense, aerospace, or adjacent themes could intersect with your portfolio, it helps to scan a wider field of listed companies using the Simply Wall St Screener.
- If you want growth potential at a smaller scale, explore early stage opportunities with 9 elite penny stocks with strong financials that still meet basic financial quality checks.
- For investors who care most about paying a fair price for strong fundamentals, filter the market using the 29 high quality undervalued stocks that combine solid balance sheets with attractive cash flow profiles.
- If capital preservation and lower volatility matter more to you than chasing every headline, start with the 30 resilient stocks with low risk scores that score well on Simply Wall St's risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com