
Learn Why The Bull Case For Alaska Air Group (ALK) Could Change Following Analyst Day Preview
- Alaska Air Group is preparing for an analyst day after a period of recently reported profit and loss performance. This has drawn scrutiny over how durable its earnings profile is in a competitive airline sector.
- The key issue now is whether Alaska Air Group can keep translating its operating model into consistent profitability as rivals compete aggressively on routes, pricing, and capacity.
- We will now assess how Alaska Air Group's investment narrative could be affected by fresh questions around the durability of its profitability.
Alaska Air Group Investment Narrative Recap
To own Alaska Air Group, you need to believe the airline can turn a currently loss-making operation into steadier profits while managing higher costs and intense competition. The near-term story centers on whether management can use the analyst day to provide credible guardrails on unit costs and capacity discipline without overpromising.
The most important near-term catalyst is clear communication around margin ambitions, cost control and the timing of Hawaiian integration benefits. A key risk is that rising labor, fuel and integration expenses could exceed what Alaska can earn on fares and fees. If the analyst day does not materially change those expectations, the news would be incremental rather than transformative.
The analyst day preview, including early commentary on 2027, is the announcement that appears to matter most right now. Investors are watching for concrete detail on how Alaska Air Group plans to handle debt that is not well covered by operating cash flow, while still funding fleet refresh, digital projects and the Hawaiian combination.
The information from that event will likely shape how to think about the existing catalysts, from the Seattle international gateway build-out to loyalty and premium initiatives. If management links those projects to clear milestones on profitability, capacity and integration, it may influence how investors weigh those opportunities against the cost, competition and regional demand risks already identified.
Alaska Air Group's current loss of $175.0 million is set against analyst expectations for earnings of $1.4 billion by 2029, alongside forecast revenues of $18.5 billion in the same year. That projection implies annual revenue growth of 7.9% and an earnings swing of about $1.6 billion from today's level.
Uncover why Alaska Air Group's fair value indicates a 42% potential upside to its current price that could narrow quickly.
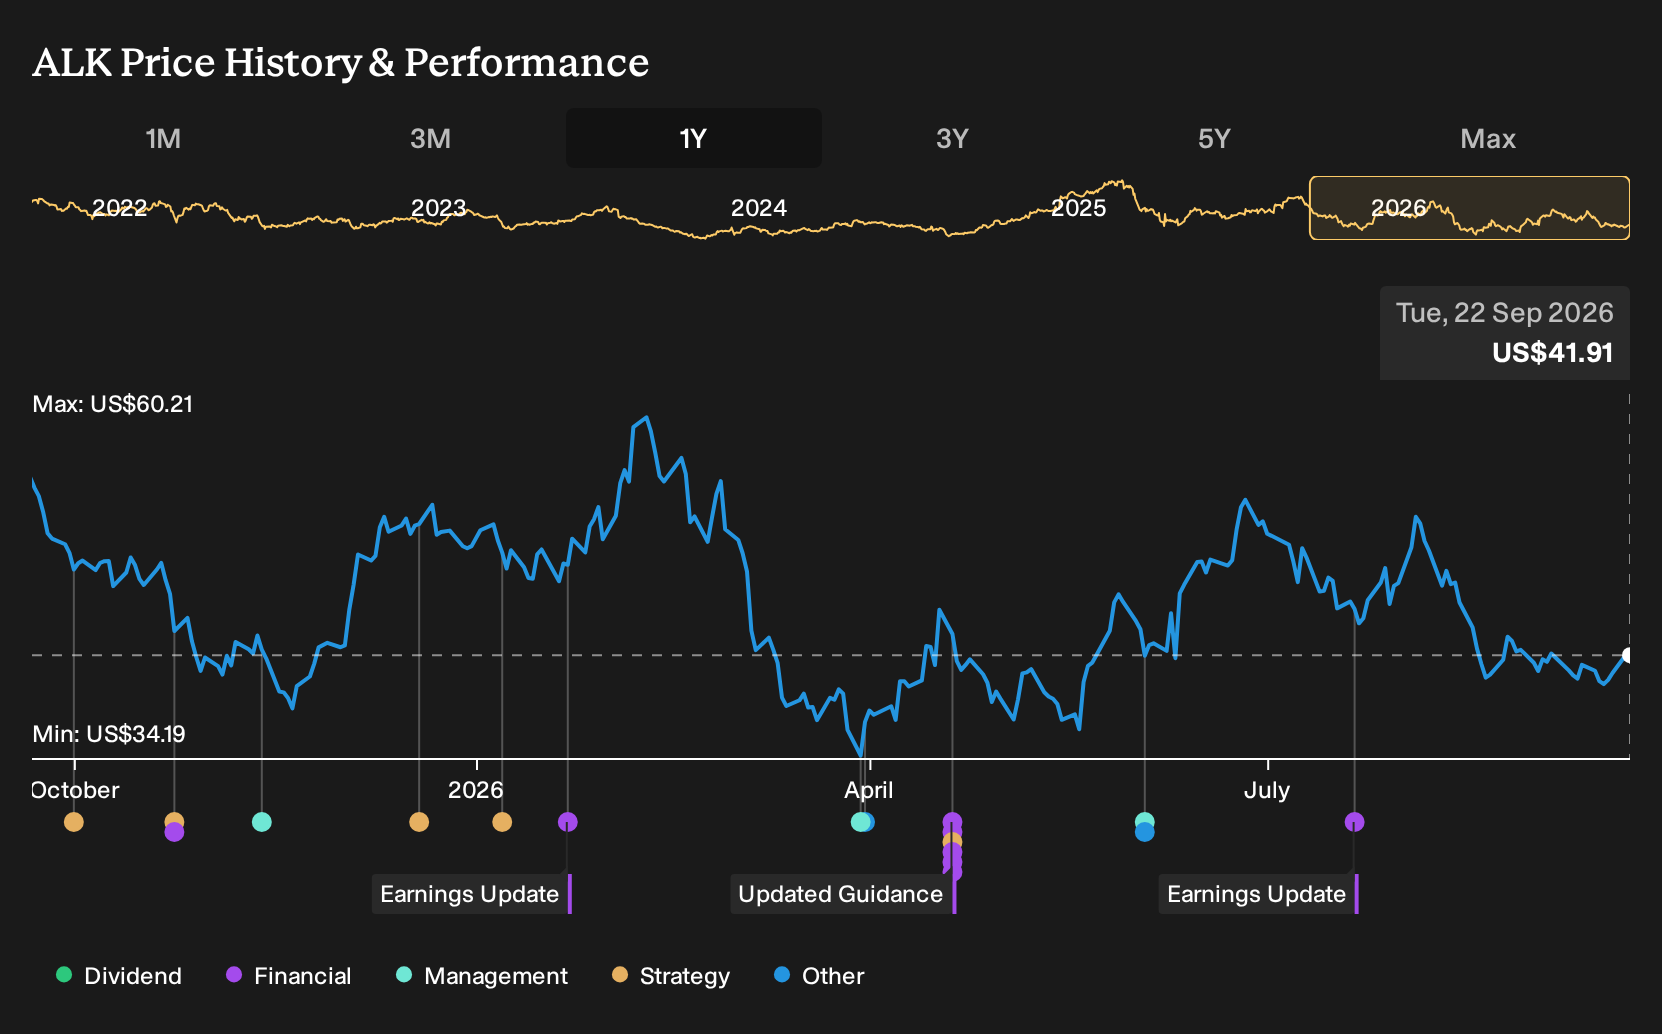
Exploring Other Perspectives
You might see Alaska Air Group very differently if you focus on the Alaska Accelerate profit target instead of cost pressure. The most cautious analysts were already penciling in about US$17.9b of revenue and US$1.1b of earnings for 2029 before this analyst day news. This shows how wide opinions run and why fresh guidance could shift both stories.
Explore 3 other Alaska Air Group fair value estimates, including one that suggests it could be worth just $57.91!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alaska Air Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alaska Air Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alaska Air Group's overall financial health at a glance.
Looking for more investment ideas beyond Alaska Air Group?
Once you have a view on Alaska Air Group, it helps to compare that thesis with a wider watchlist so you are not relying on a single story. The Simply Wall St Screener can surface other companies with very different risk and reward profiles. This can sharpen your sense of what feels compelling at today's prices.
- If you want income that does more of the heavy lifting, check out a set of companies built around robust payout profiles through the 7 dividend fortresses.
- If downside risk is front of mind, narrow your focus to businesses with stronger balance sheets and cleaner fundamentals using this curated list of solid balance sheet and fundamentals (23 results).
- If you prefer situations that the market may not be paying much attention to yet, scan a focused 16 high quality undiscovered gems that still pass solid quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com