
How Location Data Fine At Google Has Changed Its Investment Story
- Irish regulators fined Google €403 million for past GDPR breaches tied to how location data was collected, retained, and used across services such as Search, Maps, and Android settings between May 2018 and February 2020.
- The ruling pressures Alphabet to overhaul location data practices within six months, adding compliance costs and highlighting how privacy controls can affect ad targeting and user trust across its core platforms.
- We will now assess how Alphabet's investment narrative is affected by this EU privacy enforcement, especially around data governance and compliance costs.
Scan how regulators and AI heavyweights are reshaping data risk by comparing Alphabet with a curated group of 30 resilient stocks with low risk scores.
Alphabet Investment Narrative Recap
Alphabet still hinges on a simple belief. Its scale in Search, YouTube and Cloud can fund heavy AI and data center spending while keeping user trust intact. The Irish GDPR ruling adds friction, but the fine is small next to Alphabet’s US$3.27t market value and recent US$445.9b of revenue, so financial impact looks limited.
The near term swing factor remains how effectively Alphabet turns AI products and Google Cloud demand into durable cash generation while capital expenditure climbs. The biggest risk is that rising legal and regulatory scrutiny, including this privacy case, forces changes that weaken targeting and ad economics across key services.
The Mitti Labs carbon credit agreement is highly relevant when thinking about Alphabet’s data use and regulatory scrutiny. It links Google’s AI and satellite analytics to real world climate outcomes across 100,000 hectares of rice farms. That type of project depends on robust data governance and clear consent frameworks.
For you as a shareholder, this kind of deal points to a second catalyst in addition to AI monetisation. There is an expanding set of commercial use cases for Alphabet’s AI and cloud stack across climate, agriculture and infrastructure. Execution quality and compliance discipline around these projects will influence whether AI driven growth offsets rising legal and capex pressures.
Alphabet Forecasts Behind the Privacy Noise
Alphabet's narrative projects US$701.1b revenue and US$221.8b earnings by 2029. Analysts build this on 18.4% yearly revenue growth and an earnings increase of about US$61.6b from US$160.2b today.
Discover why Alphabet's fair value indicates a 22% potential upside to its current price that may not last much longer.
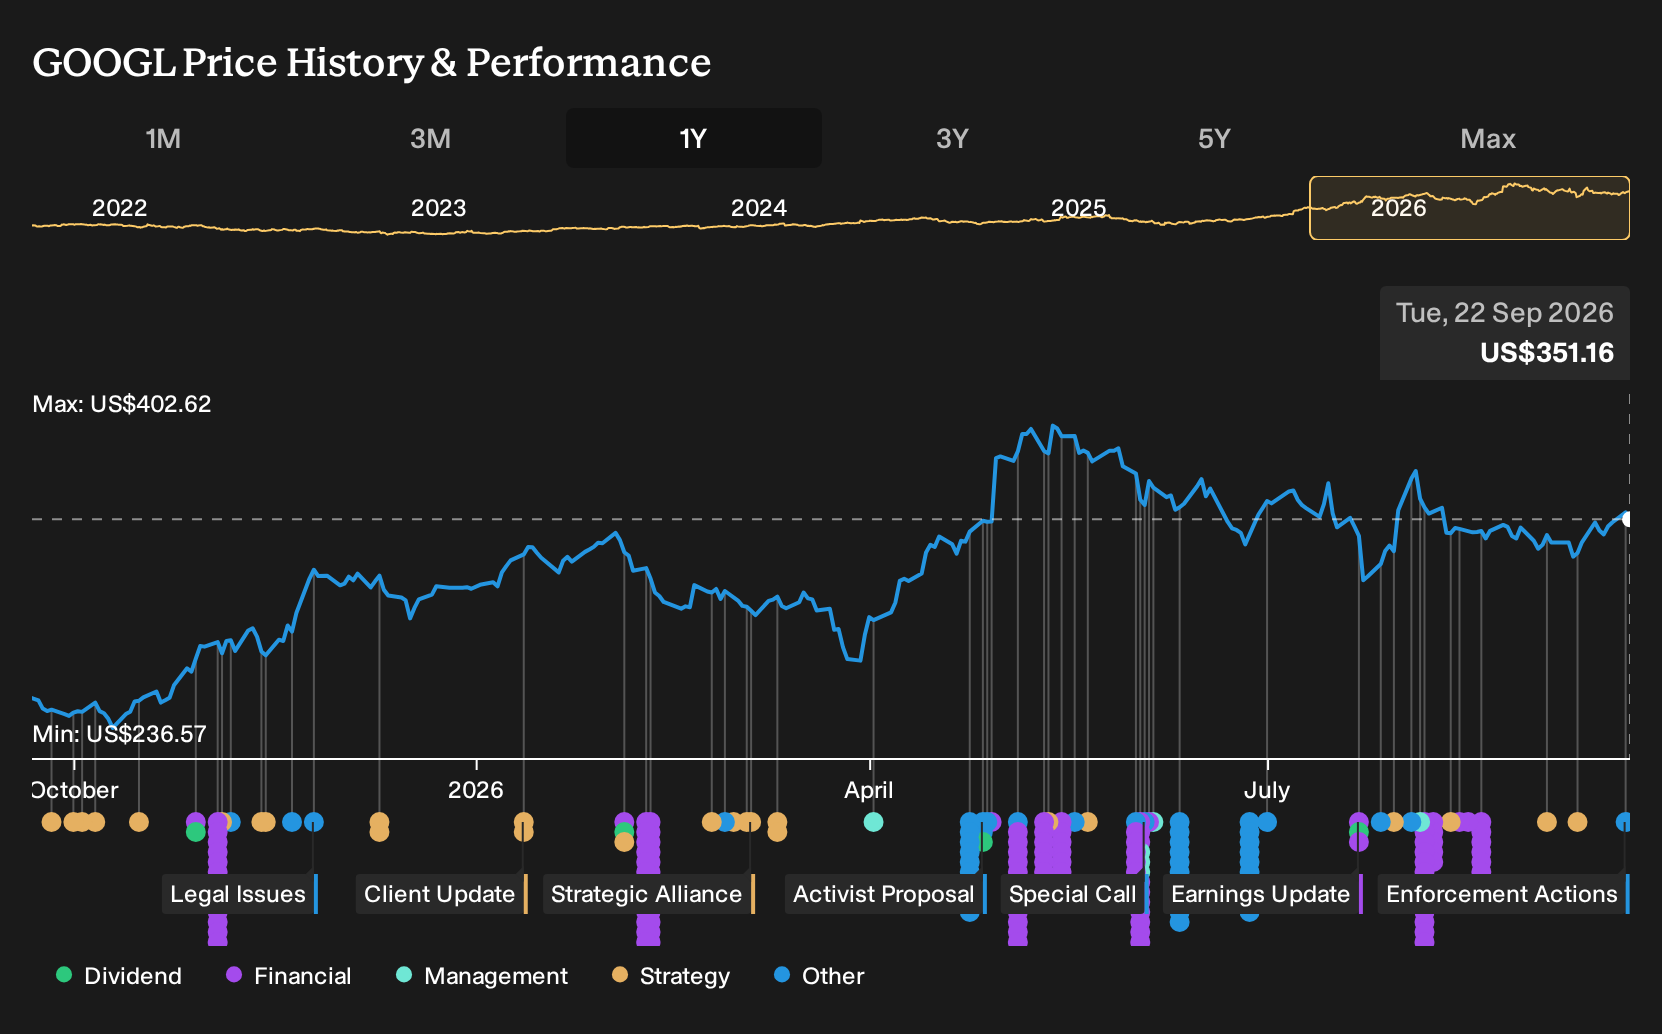
Exploring Other Perspectives
Some of the most optimistic Alphabet analysts focus less on fines and more on paid AI as the swing factor. Before this GDPR ruling, the bullish camp was modeling revenue of about US$832.0b and earnings near US$263.7b by 2029. You can now ask whether tighter data rules reshape those upbeat assumptions and explore other viewpoints.
Explore 62 other Alphabet fair value estimates, including one that suggests potential upside of as much as 38% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research.
- A great starting point for your Alphabet research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alphabet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alphabet's overall financial health at a glance.
Looking for more Alphabet investment ideas?
If this GDPR ruling has prompted a rethink about concentration risk, it can be useful to compare Alphabet with other businesses that have different balance sheet profiles, payout habits, and growth drivers. The Simply Wall St Screener helps you quickly filter for traits that matter to you and build a watchlist that complements your current exposure.
- For investors who care most about resilience and lower volatility, start with a curated set of 30 resilient stocks with low risk scores that can sit alongside higher growth holdings like Alphabet.
- If you want income to play a bigger role in your returns, consider a group of 7 dividend fortresses that focus on meaningful payouts rather than headline growth alone.
- To broaden your opportunity set beyond widely followed mega caps, review a collection of 16 high quality undiscovered gems that combine solid fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com