
Symbotic (SYM) Could Be 46% Below Fair Value As Robotics Revenue Draws Focus
Fresh attention on Symbotic (SYM) has been sparked by renewed focus on its warehouse robotics revenue and perceived valuation gap, as investors weigh Walmart concentration against the company’s automation driven growth story and cash flow potential.
Recent trading has been choppy for Symbotic, with the share price at US$45.07 after a 12.59% 30 day share price return and a 10.55% 90 day share price return. However, the year to date share price return has fallen 30.52%, the 1 year total shareholder return is down 14.99%, and the 5 year total shareholder return remains very large. This suggests that shorter term momentum is rebuilding even as investors reassess longer term expectations in light of the warehouse automation story and customer concentration risks.
Scan beyond Symbotic and line up other warehouse and automation plays using our curated list of 95 robotics and automation stocks that are poised to benefit as real revenue starts to matter in robotics.
Symbotic has rebounded to US$45.07 after a tough year. This leaves you choosing between paying up for momentum now or waiting for a pullback that may not come before the valuation case is tested.
Most Popular Narrative: 46% Undervalued
Against Symbotic's last close at $45.07, the most widely followed narrative pegs fair value at $83, which implies a sizeable valuation gap that investors are weighing against execution risk, customer concentration and the pace of warehouse automation deployments.
Analyst consensus expects revenue growth from the Walmart ASR acquisition and next-gen storage. However, the true magnitude may be underestimated, since the redesigned, patent-protected storage solution delivers high system density, retrofittability, and rapid assembly. This is viewed as fundamentally accelerating TAM expansion and opening up high-value, space-constrained use cases that could lead to changes in multi-year backlog, gross margin, and revenue visibility.
See why 23 investors see Symbotic as 46% undervalued.
That storyline relies on a discount rate of 8.46% to bring projected cash flows back to today, and it assumes Symbotic can convert a reported multi year backlog and new vertical wins into both higher revenue and an 11.81% profit margin in the outer years. The fair value of $83 is therefore not a simple extrapolation of recent share price swings, but a synthesis of expectations around deployment efficiency, software mix, capital intensity and the durability of automation demand.
Result: Fair Value of $83 (UNDERVALUED)
Still, the bullish Symbotic narrative could unravel if Walmart or other major customers slow deployments, or if higher capital needs pressure cash flows and force fresh equity raises.
Find out about the key risks to this Symbotic narrative.
Another View: What Multiples Say About Symbotic
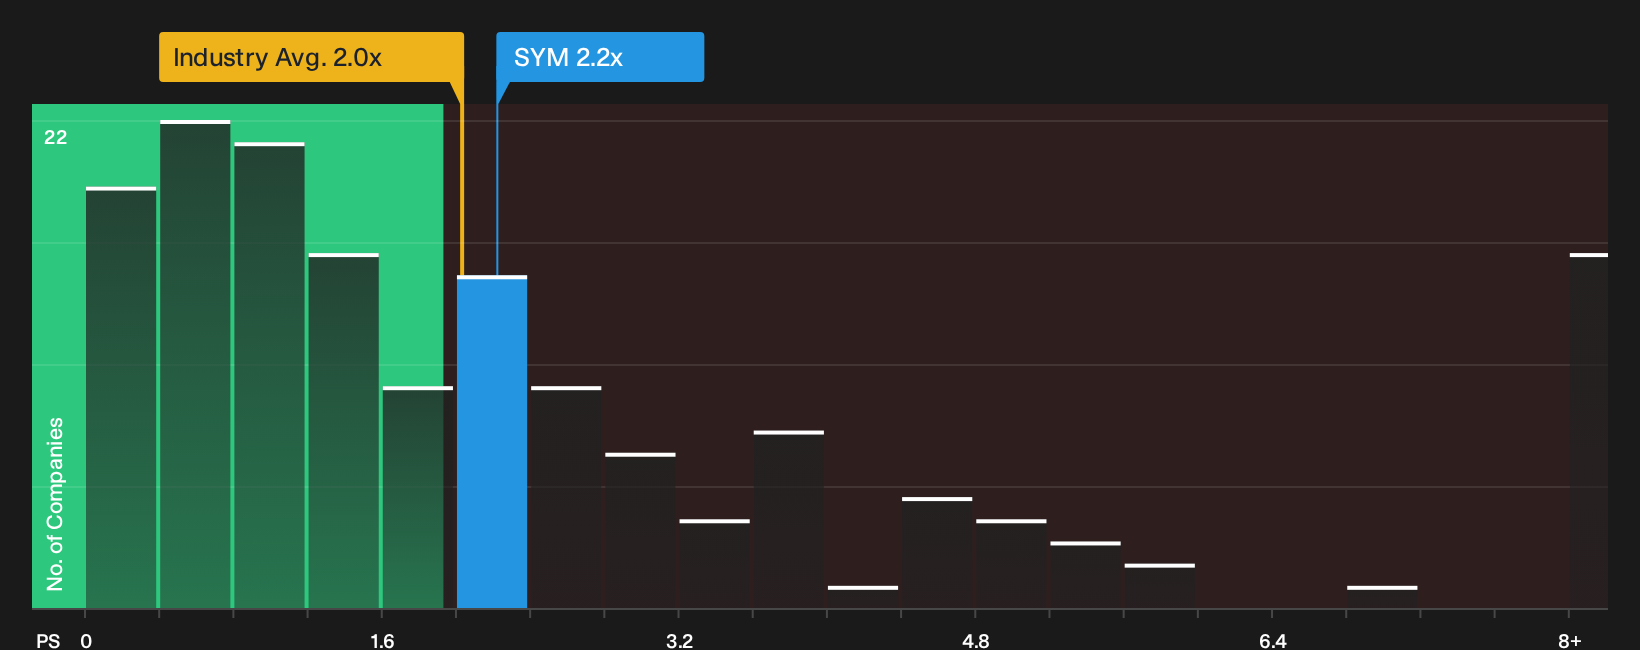
There is a catch. While the narrative and our fair value work point to upside for Symbotic at $83, the current P/S ratio of 2.2x is slightly higher than the US Machinery average of 2x, yet below the peer average of 2.8x and a fair ratio of 4.7x. This leaves investors deciding whether this gap signals extra risk or a possible opportunity.
To stress test that trade off against simple pricing, review how Symbotic stacks up in the detailed valuation breakdown, including the fair ratio context, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Symbotic is clearly split, which means speed matters if you want to cut through the noise and anchor on your own work. Use the full breakdown of 3 key rewards and 1 important warning sign
Looking for more Symbotic sized investment ideas?
Symbotic is only one piece of your portfolio puzzle. Broaden your watchlist now with ideas that match different goals before the next wave of opportunities moves on.
- Target bigger upside potential by scanning focused small caps in the 9 elite penny stocks with strong financials.
- Strengthen long term value by reviewing companies with strong fundamentals and appealing prices in the 29 high quality undervalued stocks.
- Reduce portfolio stress by concentrating on businesses with lower risk scores in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com