
Merck (MRK) Could Be 56% Below Fair Value After Fresh Regulatory Wins
Merck (MRK) is back in focus after fresh regulatory milestones, including an FDA label update for WINREVAIR in pulmonary arterial hypertension and new approvals and opinions for KEYTRUDA-based regimens in key markets.
Investors have responded to this steady stream of clinical and regulatory updates, with Merck’s 90-day share price return of 25.13% and year-to-date share price return of 41.77%. This contrasts with a small 30-day pullback of 1.08% as the stock consolidates near US$150.91, while a 1-year total shareholder return of 94.27% signals momentum that has been building rather than fading.
Capitalize on Merck’s recent regulatory momentum by comparing it with a curated 37 healthcare AI stocks poised to benefit from the same focus on advanced therapies and targeted approvals.The question now is whether Merck’s near US$151 share price already reflects that regulatory streak, or if the current intrinsic discount hints at more upside still ahead.
Most Popular Narrative: 0% Overvalued
Merck’s most followed narrative anchors fair value at $150.42, almost exactly in line with the last close at $150.91. This keeps attention squarely on what drives that valuation rather than a pricing gap.
With its acquisition and licensing strategy, Merck has nearly tripled its late-phase pipeline since 2021, which is expected to have a potential commercial opportunity of over $50 billion by the mid-2030s, driving earnings growth.
See why 408 investors see Merck as 0% overvalued.
Result: Fair Value of $150.42 (ABOUT RIGHT)
Still, Merck’s story could change quickly if pricing pressure on key oncology products tightens or if GARDASIL softness in China proves more persistent than expected.
Find out about the key risks to this Merck narrative.
Another View: Merck Through A Cash Flow Lens
The earlier narrative leans on analyst targets that peg Merck close to fair value around $150. Yet Simply Wall St’s DCF model points to a future cash flow value of $235.29 per share, which implies the current $150.91 level is trading at a steep discount. That gap raises a simple question for investors: Are analysts too cautious on what Merck’s pipeline and margins might ultimately deliver?
Look into how the SWS DCF model arrives at its fair value.
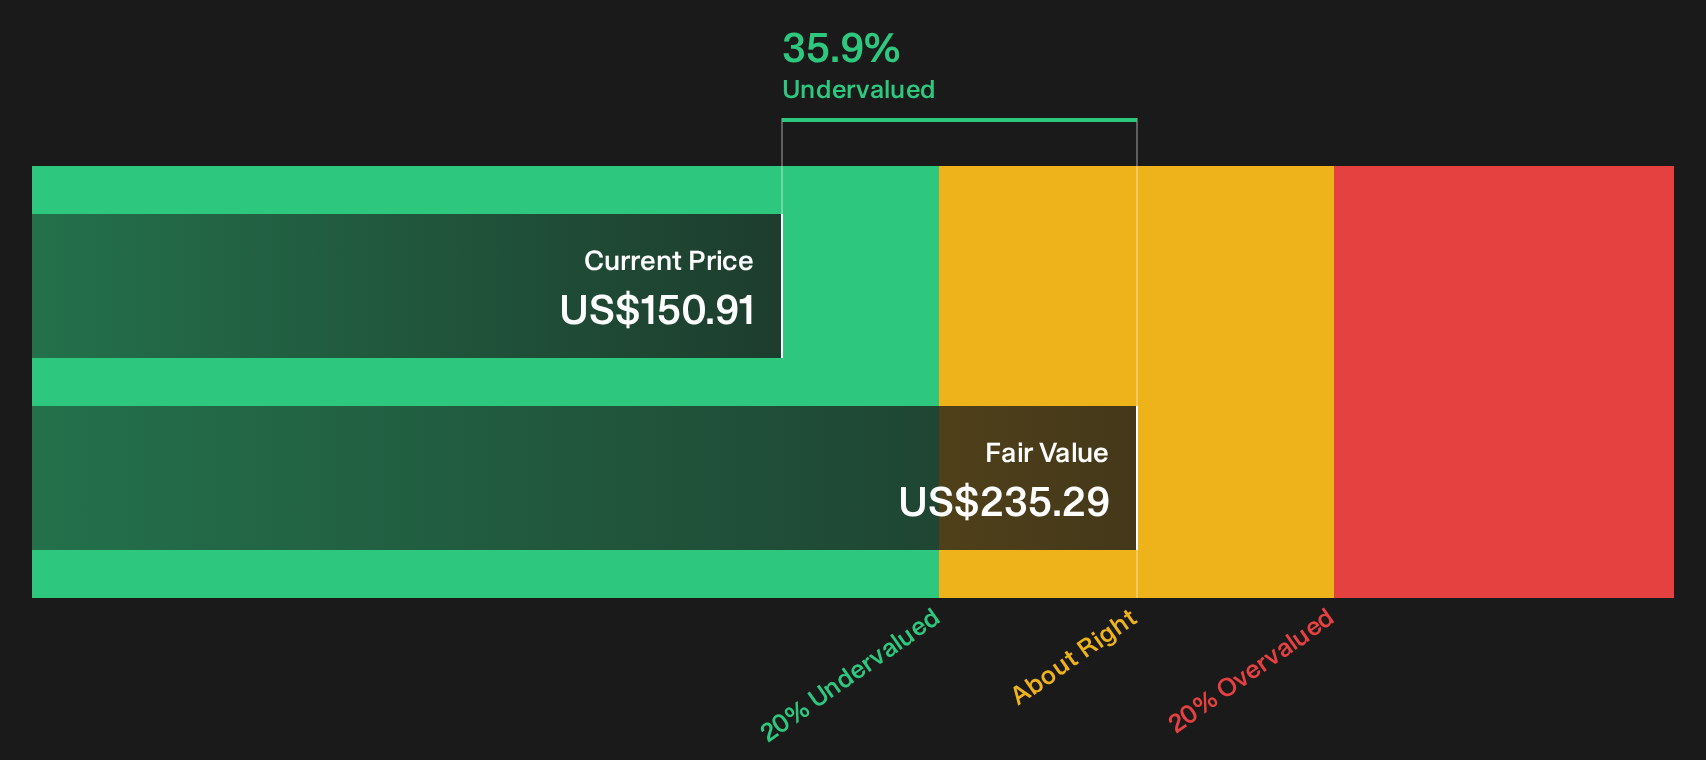
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Merck for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of optimism and caution running through Merck’s story right now? Act quickly, review the data yourself, and evaluate the 2 key rewards and 5 important warning signs.
Looking for more Merck investment ideas?
Do not stop with Merck alone. Use the Simply Wall St screener to source fresh ideas, compare quality, and pressure test whether your capital is working hard enough.
- Target undervalued potential by scanning a curated list of companies screened for quality and pricing gaps through the 29 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with solid finances surfaced through the list of solid balance sheet and fundamentals (23 results).
- Spot lesser known opportunities by reviewing a handpicked group of strong fundamentals in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com