
Champion Homes (SKY) Could Be 14% Undervalued As HUD Showcase Sharpens The Debate
Champion Homes (SKY) gave investors a fresh talking point after using the HUD Innovative Housing Showcase to spotlight its offsite-built New Horizon and New Frontier models, which are aimed at tackling the affordable housing shortage.
Recent trading has tilted in Champion Homes' favor, with a 1-day share price return of 2.72% and a 7-day move of 4.96%, while the 1-year total shareholder return of 19.01% and 3-year total shareholder return of 41.76% point to momentum that has been building rather than fading.
Scan beyond Champion Homes and see which other housing and construction plays are showing similar momentum and balance sheet strength in our curated list of solid balance sheet and fundamentals (23 results)
Champion Homes now trades around the recent HUD showcase buzz and a 1-year return near 19%. Does that justify paying up today, or does it make more sense to wait for a cheaper entry before looking at valuation?
Most Popular Narrative: 14% Undervalued
Champion Homes is priced at $88.84 against a widely followed fair value estimate of $103.50, which suggests a meaningful valuation gap that hinges on how investors view future demand for factory-built housing.
Increasing national focus on housing affordability and supportive policy momentum (such as the bipartisan advancement of the ROAD to Housing Act) is expected to drive structural, long-term demand for manufactured homes, directly benefiting Champion's volumes and revenue growth in coming years.
Accelerating shifts among first-time buyers and traditional homeowners toward affordable, high-quality off-site construction, supported by targeted marketing and product innovation, should expand Champion's customer base and support sustainable top-line growth.
See why 5 investors see Champion Homes as 14% undervalued.
Result: Fair Value of $103.50 (UNDERVALUED)
Still, the narrative around Champion Homes starts to look fragile if material costs rise again or if affordability pressures begin to choke off demand at key retail channels.
Find out about the key risks to this Champion Homes narrative.
Another View on Champion Homes Valuation
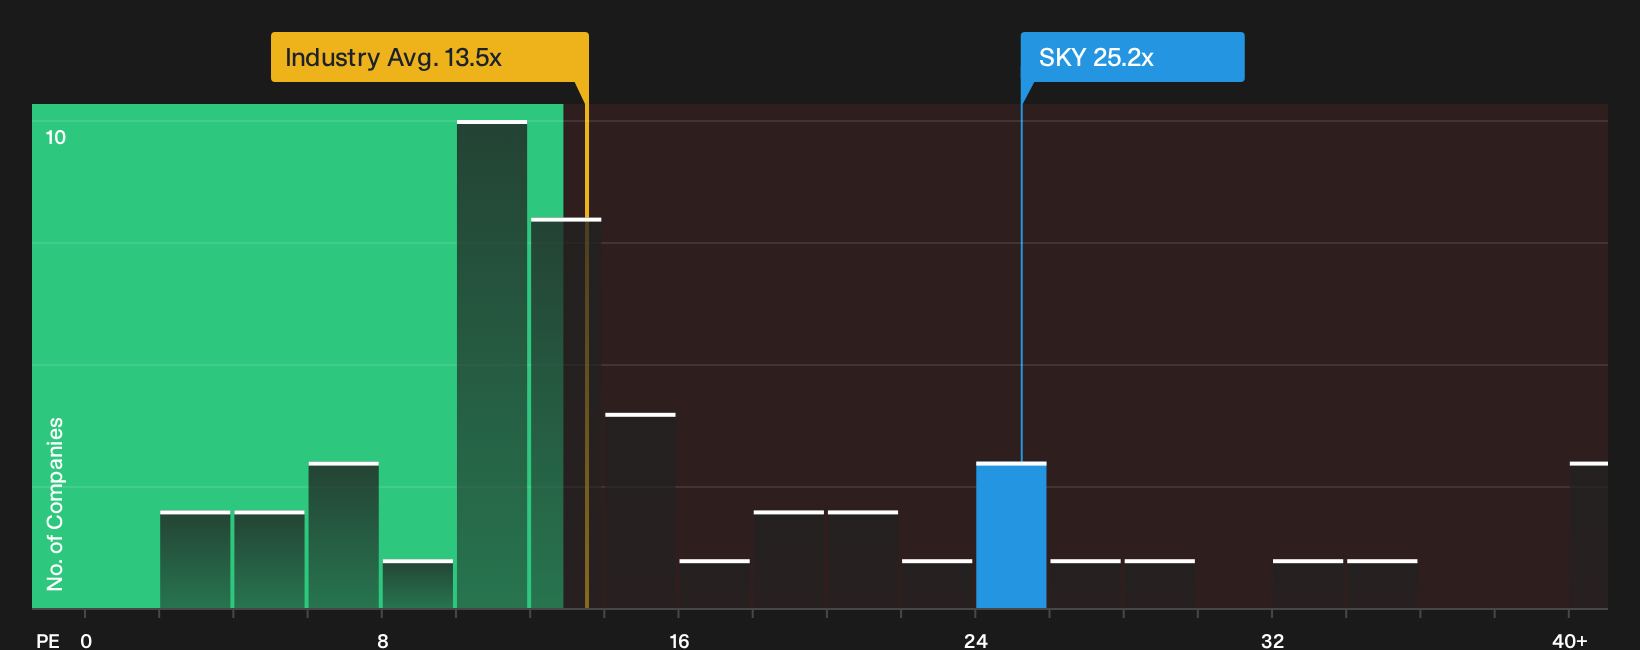
There is a catch. On a simple earnings multiple, Champion Homes looks expensive even while the fair value models point to upside.
The stock trades on a P/E of 25.2x, compared with 13.1x for the broader US Consumer Durables group and 17.6x for closer peers. The fair ratio sits at 19.2x, which is the level the market could move toward if sentiment cools or growth expectations get reassessed. That gap leaves investors weighing potential upside from the undervaluation thesis against the risk that the multiple compresses instead.
It raises a straightforward question: Is the extra price you pay for Champion Homes a fair trade for the growth profile, or is it a margin of safety in reverse?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough to get a sense of where sentiment sits on Champion Homes today, and how quickly it could shift if the story changes? Move from reading to testing the thesis yourself by weighing the upside case against the trade offs highlighted in the 2 key rewards.
Looking for more investment ideas beyond Champion Homes?
If Champion Homes sharpened your focus on quality and price, you can use that momentum to look for clear, data-backed opportunities before the crowd gets there.
- Target potential value opportunities by scanning companies that combine quality fundamentals with attractive pricing using our curated 29 high quality undervalued stocks.
- Prioritize resilience by filtering for businesses with sturdy finances in the list of solid balance sheet and fundamentals (23 results).
- Uncover lesser-known opportunities by reviewing our handpicked list of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com