
Is Weaker Earnings Guidance Altering The Investment Case For KB Home Stock (KBH)?
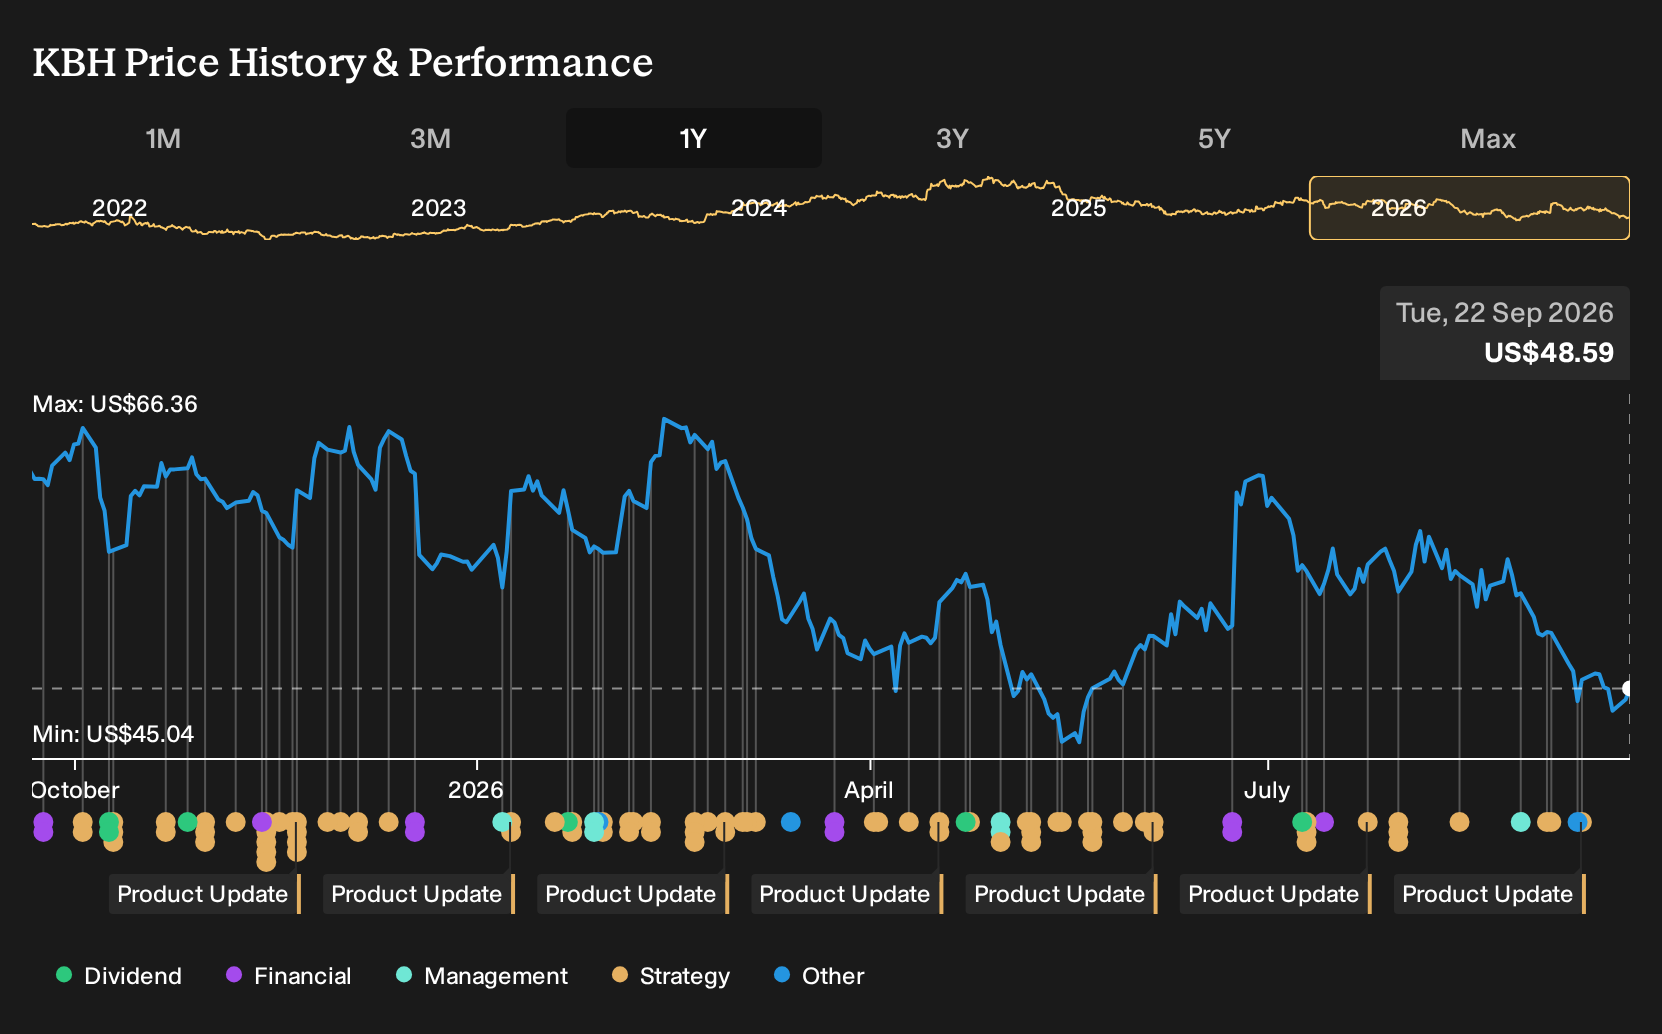
- KB Home reported third quarter 2026 results with revenue of US$1,297.1 million and net income of US$65.28 million, alongside lower earnings per share year on year, and updated housing revenue guidance for the fourth quarter and full year.
- The builder paired softer year to date profitability with continued capital returns by completing a US$275.12 million buyback that retired 7.46% of its shares, tightening the share count even as operating income remains under pressure.
- This article examines how KB Home's earnings decline and new housing revenue guidance may influence the current investment narrative for the builder.
KB Home Investment Narrative Recap
For KB Home, the long term story still hinges on buyers being willing and able to close on new homes at acceptable pricing, while build times and cost control keep projects economical. The sharp drop in nine month revenue and earnings shows how quickly that equation can get tougher. The key short term swing factor is whether orders and deliveries stabilize around current guidance or soften further into 2027.
The biggest operational risk right now is margin compression if KB Home needs deeper pricing adjustments in weaker regions while carrying high debt and lower profitability than last year. Third quarter results already show thinner net income, so any renewed pressure on consumer confidence or competition would likely keep returns under strain rather than ease them.
The most relevant fresh datapoint for that debate is KB Home's housing revenue outlook for the fourth quarter and full year 2026. Management now expects Q4 housing revenue between US$1.45b and US$1.65b, and full year between US$4.90b and US$5.10b. Those numbers frame what “normal” might look like after this reset in demand and pricing.
For you as a shareholder, that guidance effectively becomes the scoreboard for execution. Deliveries, community openings and incentive levels will all be judged against those ranges. If the builder hits the midpoint while keeping cancellations and build times in check, it supports the view that current profitability is a cyclical squeeze rather than a structural break in the KB Home model.
KB Home's current analyst narrative points to revenues of US$5.8b and earnings of US$326.2 million by 2029, based on revenue growth of 1.8% per year and an increase in earnings of about US$56.7 million from US$269.5 million today.
Uncover why KB Home's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate KB Home angle focuses on long term demand risk. The most pessimistic analysts worry that slower household formation could leave revenue drifting closer to US$5.7b by 2029, not far from their pre news expectations. This compares with consensus forecasts nearer US$5.8b. That gap shows how sharply opinions can split, so it is worth comparing several viewpoints as this latest guidance filters into fresh models.
Explore 2 other KB Home fair value estimates, including one that suggests as much as 84% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KB Home research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for KB Home. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KB Home's overall financial health at a glance.
Looking For More Investment Ideas Beyond KB Home?
Once you have a view on KB Home, it can help to compare it against other listed businesses with different risk and income profiles. The Simply Wall St screener lets you filter by balance sheet strength, income potential and valuation so you can build a watchlist that actually fits your goals.
- For investors who care most about stability and capital preservation, check out a 30 resilient stocks with low risk scores that screens for resilient businesses with lower risk profiles.
- If you want income on top of potential price moves, there is a curated 7 dividend fortresses focused on companies offering higher yields that may appeal to cash flow focused investors.
- When you are hunting for quality at a reasonable price, the hand picked 16 high quality undiscovered gems can surface lesser known stocks with fundamentals that may not be fully reflected in their current valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com