
Is Mobility Spinoff Altering The Investment Case For Eaton (ETN)?
- Eaton developed Workbench 360, a connected experience that links its electrical equipment data and expertise with Autodesk Revit, Forma and Tandem to support building projects from design through long term operations.
- The platform ties Eaton equipment data into Autodesk digital twins and Brightlayer, which may help customers manage assets and energy use more efficiently across complex facilities.
- We will now look at how Eaton's Workbench 360 launch could influence the investment narrative built around its electrical focus.
Scan Eaton's push into electrified infrastructure in the context of a wider field of grid and data center suppliers by reviewing our curated list of 40 power grid technology and infrastructure stocks poised to benefit from similar demand shifts.
Eaton Investment Narrative Recap
To stay comfortable as a shareholder in Eaton, you need to believe the electrical and aerospace tilt, backed by US$30.0b of revenue and US$3.8b of net income, keeps earning power anchored in real projects like data centers and grid upgrades. Workbench 360 fits that story by tying Eaton gear into building design and operations, but it does not change the core thesis.
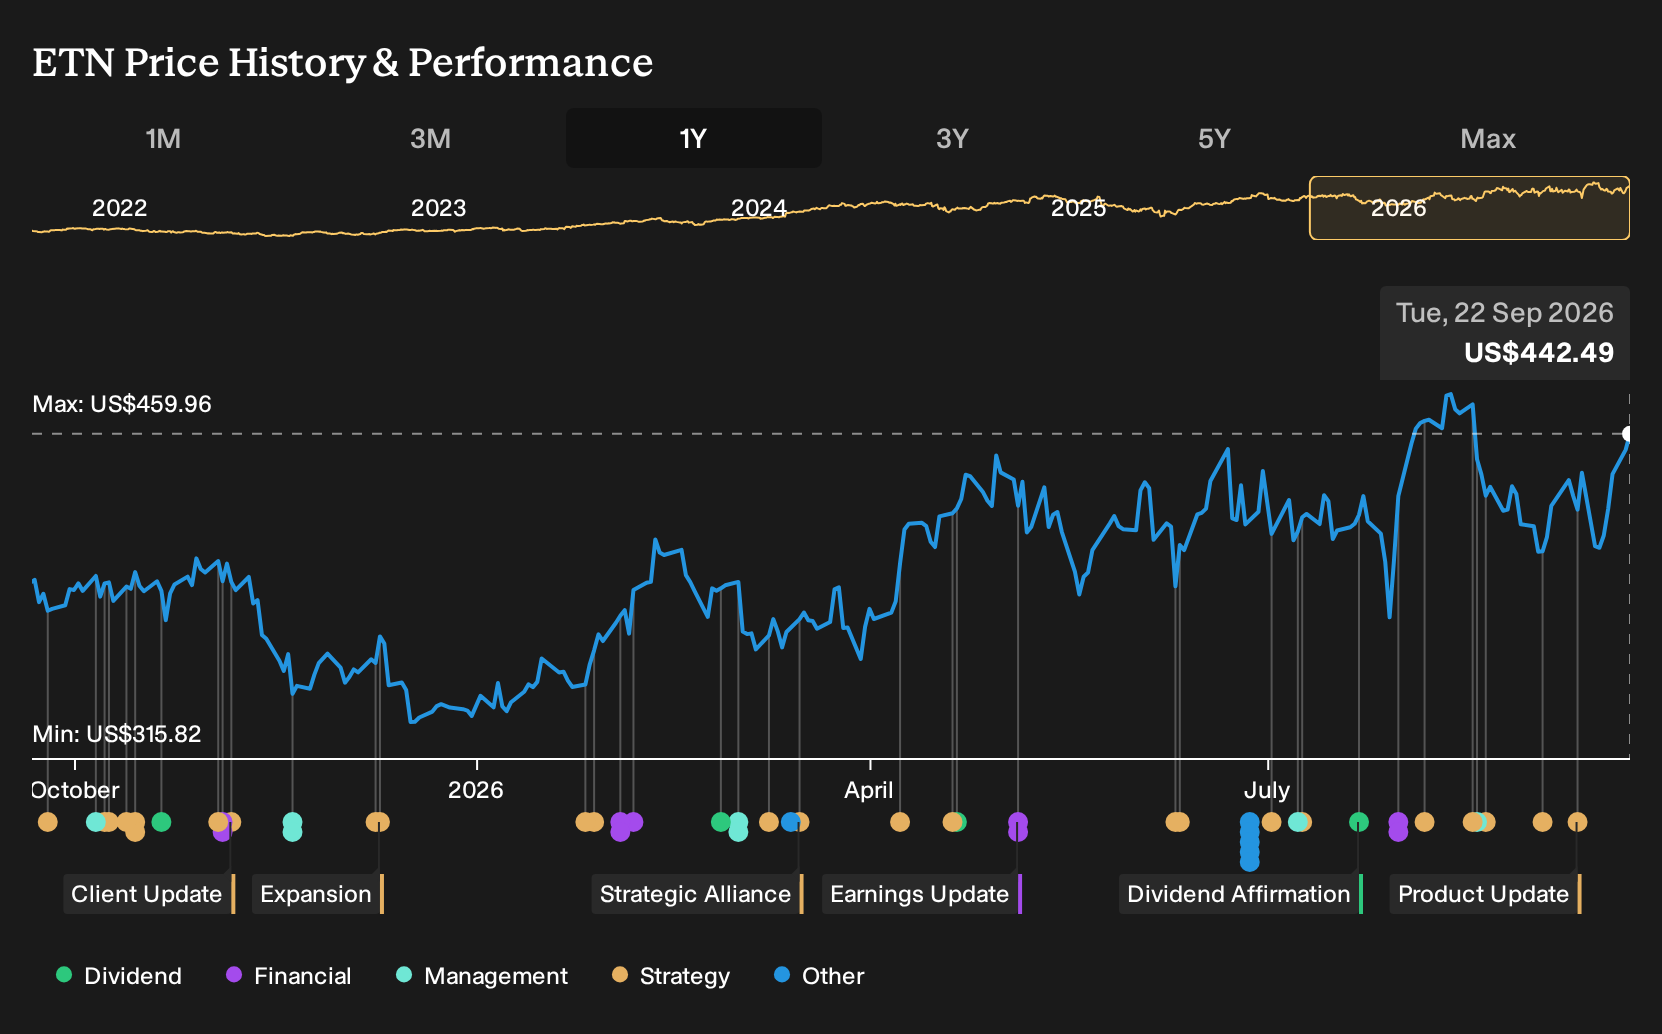
The near term swing factor is still execution on big electrical backlogs, capacity build outs and integrating deals like Boyd and Fibrebond without pressuring margins that already dipped from 15.1% to 12.8%. The biggest risk remains sensitivity to any earnings miss or slowdown, given a rich P/E of 44.9x and past sharp share price reactions.
The Workbench 360 rollout connects Eaton equipment data with Autodesk tools across the building lifecycle. That matters most where the firm is already leaning hardest for future growth, especially data centers, campuses and healthcare facilities that rely on reliable, efficient power and where digital twins can help customers run these assets more tightly.
Recent commentary tying data center demand to the high end of Eaton’s 11% to 13% 2026 revenue growth range means anything that deepens integration with customers in that ecosystem is relevant. Workbench 360 could reinforce the grid to chip pitch and long dated backlog pipeline, while still leaving investors watching execution risk, debt levels and valuation sensitivity very closely.
Eaton's analyst narrative points to revenues of US$43.4b and earnings of US$7.5b by 2029, based on an assumed 13.0% yearly revenue growth rate and an earnings increase of US$3.7b from the current US$3.8b base.
Uncover why Eaton's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Eaton analysts were already leaning hard into the data center and mega project story, with revenue growth assumptions of 14.3% a year and earnings reaching about US$7.3b by 2029. If Workbench 360 deepens Eaton’s role inside Autodesk workflows, that scenario could either gain support or face tougher questions. You should compare these upbeat views against more cautious forecasts and decide which perspective seems more realistic for your own assessment.
Explore 8 other Eaton fair value estimates, including one that suggests up to 21% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eaton research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eaton?
If the Eaton story has sharpened your thinking about electrification, it can help to compare it with other businesses that fit clear financial themes. The Simply Wall St Screener lets you filter the market quickly so you can focus on companies that match your risk tolerance and return goals.
- If capital preservation is a priority, start with lower volatility prospects by checking out 30 resilient stocks with low risk scores that may offer more defensive profiles.
- If dependable income matters most, review companies in the 7 dividend fortresses that can help you build a portfolio focused on yield.
- If you want to cast a wider net for overlooked opportunities, scan the 16 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com