
Production Move Could Be A Big Moment For Woodward Stock (WWD)
- Woodward, Inc. has already outlined a major reorganization of its aerospace controls operations, shifting military flight control actuation from the Santa Clarita, California site to a new Spartanburg, South Carolina campus. The company is also selling certain legacy product lines and that facility and planning to wind down Santa Clarita activity by December 2027, affecting about 400 roles.
- The planned move of Airbus A350 spoiler actuation system production and other aerospace components into the Spartanburg plant signals a push to concentrate capital, technology, and supply chains into a single aerospace hub rather than maintaining a more fragmented manufacturing footprint.
- We will look at how Woodward's investment narrative is affected by consolidating flight control production into the upcoming Spartanburg aerospace campus.
Woodward Investment Narrative Recap
To own Woodward, you need to believe in a focused aerospace and industrial controls business that can keep turning heavy capital projects into durable cash generation. The Spartanburg shift keeps that thesis intact. It tightens the footprint around higher priority flight control programs, but also concentrates execution risk into a single large aerospace campus coming online in 2027.
The biggest near term swing factor is whether Woodward can bring that facility up smoothly while sustaining current margins and supply reliability. The main risk sits in integration and ramp timing. Prolonged disruption, cost overruns, or inventory build around the move could pressure free cash flow and test the current high P/E multiple.
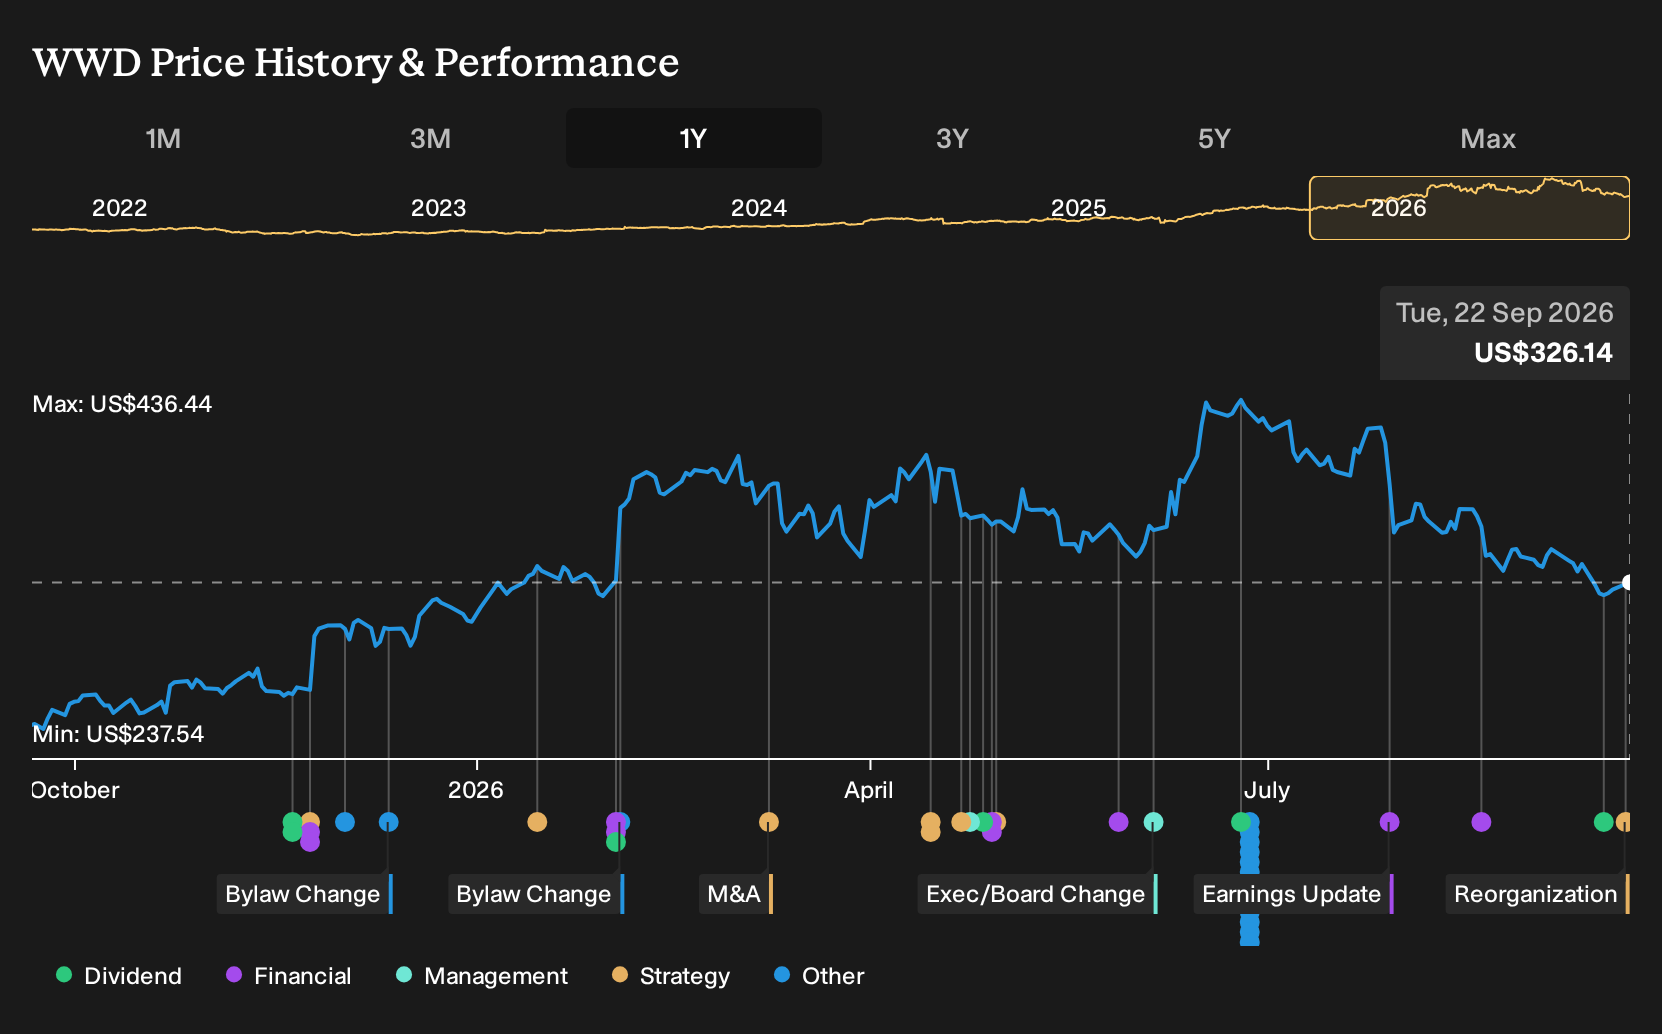
The dividend affirmation on 16 September 2026 at US$0.32 per share is the announcement that ties most directly into this reorganization story. Management is committing cash to shareholders as it prepares to fund several hundred million dollars of aerospace capacity, so investors are watching whether internal funding and balance sheet flexibility remain comfortable.
For readers, the key question is whether Woodward can keep supporting that payout while executing on the A350 spoiler program and broader aerospace ramp. Any sustained margin compression, working capital strain, or delays in the Spartanburg start up could limit future capital return options and weigh on confidence in near term earnings progress.
What The Consensus Woodward Forecasts Assume
Woodward's narrative projects US$5.1b revenue and US$749.1m earnings by 2029. This implies 8.6% yearly revenue growth and an earnings increase of roughly US$235m from US$513.8m today.
Discover how Woodward's fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Santa Clarita and Spartanburg shift as a potential accelerator for Woodward. Before this news, the bullish camp was already modeling revenue reaching about US$5.8b and earnings around US$904.2m by 2029. You can treat this reorganization as a fresh data point and compare it with those more upbeat expectations.
Explore 4 other Woodward fair value estimates, including one that suggests as much as 57% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Woodward research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Woodward. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodward's overall financial health at a glance.
Looking For More Ideas Beyond Woodward?
If the Woodward story has sharpened your thinking about aerospace supply chains and capital allocation, use that momentum to scan a wider watchlist. The Simply Wall St Screener can help you turn a broad market into a focused shortlist that actually fits your risk profile and income goals.
- If you want a starting point for potential mispriced opportunities with solid fundamentals, review our 29 high quality undervalued stocks that may warrant closer attention.
- If income is front of mind and you care about consistency of payouts, check out a curated 7 dividend fortresses that can help you focus your dividend research.
- If capital protection matters more than chasing every swing, filter for a 30 resilient stocks with low risk scores that could suit a more cautious approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com