
Madison Air Solutions (MAIR) Lifts Guidance, Is It Still Below Fair Value?
Madison Air Solutions (MAIR) raised its third quarter 2026 revenue guidance and now projects full year top line expansion in the high teens, compared with its prior outlook in the high single-digit-plus range.
That guidance shift lands after a bruising stretch for Madison Air Solutions, where the share price return has fallen 36.4% over the past 90 days and 21.1% year to date. The stock has rebounded 3.8% in the last session and 4.8% over the past week, hinting at improving momentum as investors reassess the outlook.
Scan for other industrials with shifting guidance and recent volatility by checking the hand picked 29 high quality undervalued stocks moving on revised outlooks similar to Madison Air Solutions.
Madison Air Solutions just lifted its growth outlook while the share price is still nursing a steep recent slide. Strong air quality franchise, weaker chart. Is the stock now cheap or just less expensive?
Preferred P/E of 88.4x: Is it justified?
Valuation on Madison Air Solutions is tight. The SWS model flags the stock as trading 16.3% below an estimated future cash flow value of $29.92, while the last close sits at $25.05, yet the headline P/E ratio is a steep 88.4x.
P/E compares what investors pay per share with the earnings generated per share. For a business like Madison Air Solutions, which reported earnings of $142.2m on $3.7b of revenue and operates across both commercial and residential air quality markets, that ratio gives a quick sense of how much future profit growth is already reflected in the current tag.
The multiple is high against both reference points provided. The 88.4x P/E is described as expensive compared with the US Building industry average of 20.2x and also expensive relative to peer companies on 17.4x. That gap suggests the market is assigning a sizeable premium to Madison Air Solutions despite low current Return on Equity of 4.5% and interest costs that are not well covered by earnings, even though earnings are forecast to grow 46.9% per year and have risen 48.9% over the past year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 88.4x (OVERVALUED)
Still, the recent share price slide and low 4.5% Return on Equity leave plenty of room for sentiment to sour again if guidance or financing costs disappoint.
Find out about the key risks to this Madison Air Solutions narrative.
Another View on Madison Air Solutions' Value
The P/E looks stretched, but the SWS DCF model presents a different view. It puts Madison Air Solutions' fair value at $29.92 a share, which is around 16.3% above the current $25.05 price. That suggests potential undervaluation. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
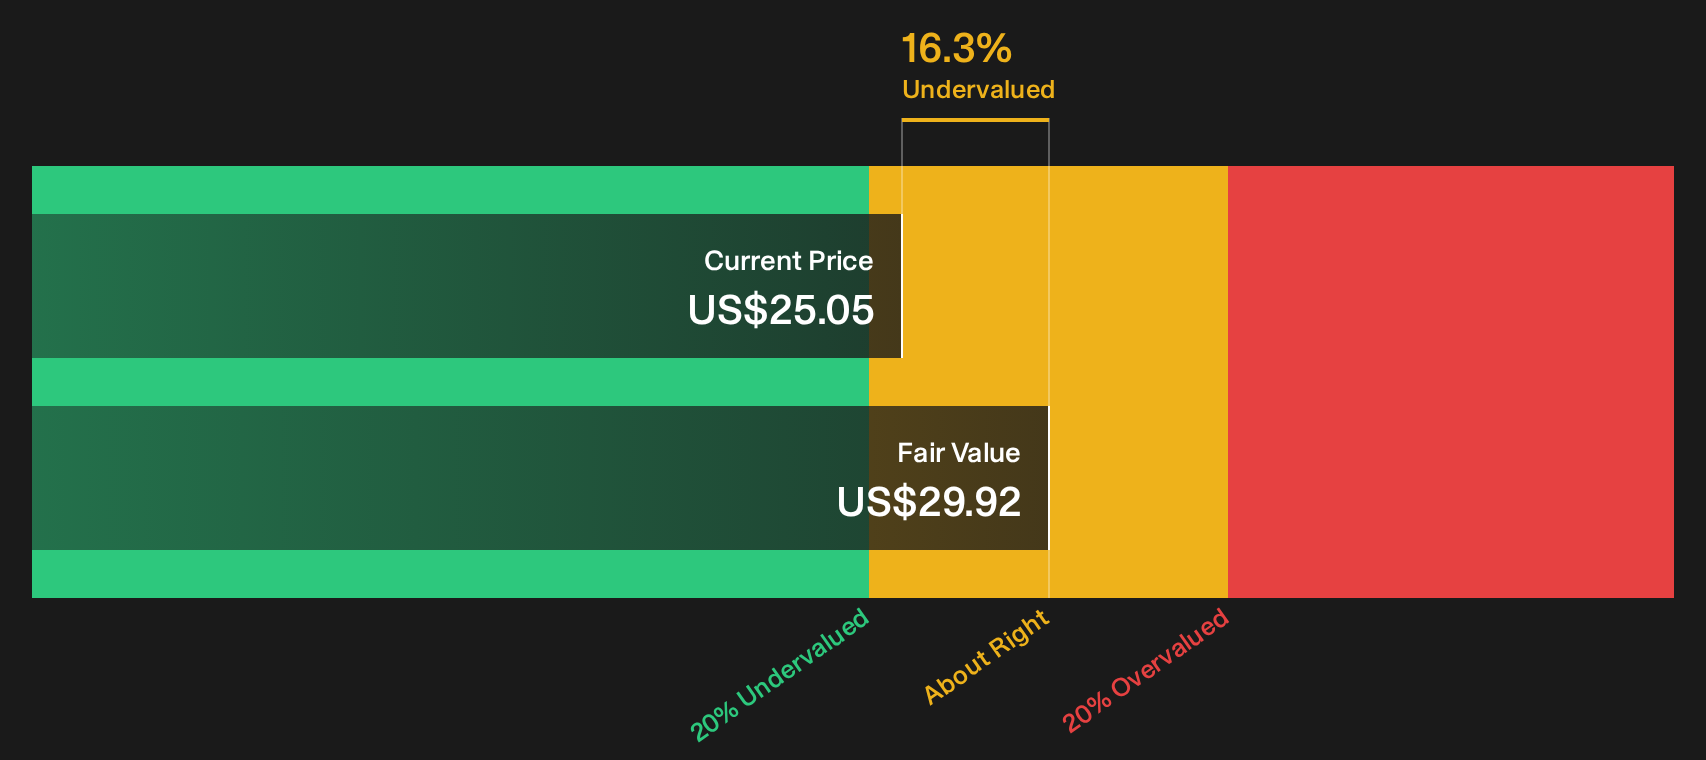
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Madison Air Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Madison Air Solutions so far. If you want to move fast and evaluate the balance of concerns against the potential upside for yourself, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Madison Air Solutions?
If Madison Air Solutions has you rethinking value, do not stop here. Fresh ideas often come from comparing very different businesses side by side.
- Target dependable compounding by scanning companies prioritizing resilience and disciplined balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential bargains by zeroing in on quality businesses that screen as mispriced using the 29 high quality undervalued stocks.
- Spot under-the-radar opportunities before they are crowded by tracking the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com