
Installed Building Products (IBP) Could Be 13% Undervalued After Its 20% Monthly Slide
Installed Building Products (IBP) has come under the spotlight after its shares declined about 20% over the past month. This has prompted a fresh look at cash flow resilience, acquisition activity, and future earnings potential.
The recent 20% slide over the past month sits against a much longer run of strong compounding for Installed Building Products, with a 3-year total shareholder return of 82.14% and a 5-year total shareholder return of 108.40%. This indicates that long-term holders have still done well despite the setback.
Compare how Installed Building Products stacks up against hand-picked construction and building services peers that screen as 29 high quality undervalued stocks right now.
The recent slide in Installed Building Products looks sharp on the chart, yet the 3 and 5 year returns tell a very different story. Is this drawdown signalling business problems, or just a reset in sentiment that has changed the price, not the cash flows investors are paying for?
Most Popular Narrative: 13.4% Undervalued
Installed Building Products is being framed as undervalued in the most followed narrative, with a fair value of about $244.82 against a last close of $211.94. That gap is being tied to a mix of acquisition potential, capital returns, and a broad mix of end markets rather than rapid headline growth.
Diversification, operational improvements, disciplined capital allocation, and supportive industry trends position IBP for resilient growth and profitability despite economic and sector challenges.
Long-term industry fundamentals such as tightening building codes and energy efficiency requirements, combined with undersupply of residential housing and IBP's proven ability to capture market share via acquisition in a fragmented industry, present durable secular growth opportunities that may drive revenue, margin expansion, and earnings growth over the coming years.
See why 5 investors see Installed Building Products as 13% undervalued
Result: Fair Value of $244.82 (UNDERVALUED)
Still, the bullish Installed Building Products story starts to wobble if commercial and multifamily backlogs soften, or if acquisition opportunities and cash generation fall short.
Find out about the key risks to this Installed Building Products narrative.
Another View On Installed Building Products Valuation
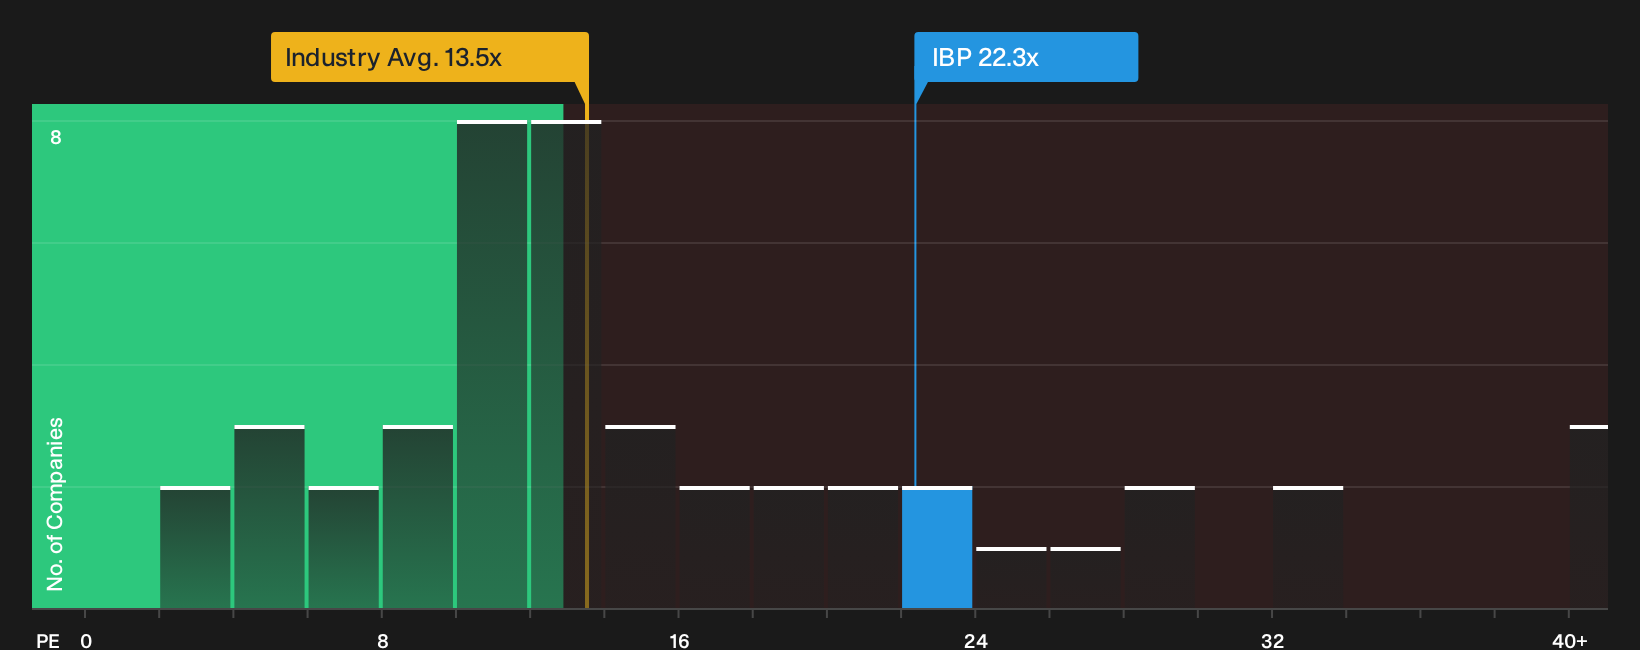
The headline story says Installed Building Products looks about 13.4% undervalued against an estimated fair value of $244.82. On simple P/E math, the picture is less comfortable. The stock trades around 22.3x earnings compared with a fair ratio of 15.6x and a US Consumer Durables average of 13.1x.
Against closer peers on P/E, IBP also looks full, with the group around 18.4x. That kind of premium can signal confidence in the quality of the business, or it can leave less room for error if earnings or acquisition momentum disappoint. Which story do you think the market is really pricing in right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Installed Building Products can make the story feel cloudy, so pull up the numbers yourself and test both sides of the argument while sentiment is still in flux. To frame that view against the key bullish and bearish points investors are focused on, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Installed Building Products?
If Installed Building Products has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist now with targeted stock ideas built from the same disciplined approach.
- Spot potential value up front by scanning a curated 29 high quality undervalued stocks that combines solid fundamentals with prices that may not fully reflect their underlying strength.
- Strengthen your income stream by reviewing a focused 7 dividend fortresses that offers higher yields with an emphasis on staying power rather than hype.
- Protect your downside by filtering for a 30 resilient stocks with low risk scores that scores well on balance sheet resilience and business quality so setbacks may have less impact.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com