
Weyerhaeuser (WY) Stock Looks Undervalued Even After A 27% Five Year Fall
Weyerhaeuser has seen its share price under pressure in recent years, and that raises a straightforward question for investors who care about valuation. Is the current US$21.54 price tag adequately supported by the earnings power of this timber REIT today?
- The stock has fallen 27.0% over the past 5 years, which puts the spotlight squarely on whether the long stretch of weaker returns lines up with the business it represents.
- A new agreement with Hexagon Energy to develop geothermal projects across parts of Weyerhaeuser land in Washington and Oregon may influence how investors think about future earnings mix, capital spending needs and potential cash flow from energy usage on these assets.
- The analysts covering Weyerhaeuser have run their own numbers. See what analysts think Weyerhaeuser's shares could be worth.
The issue now is whether Weyerhaeuser's current share price is justified by the earnings that investors can reasonably associate with the business today.
If you want to stress test Weyerhaeuser's earnings question against a wider field of potential ideas, apply the same lens to 29 high quality undervalued stocks.
Does Weyerhaeuser Look Undervalued on Earnings?
P/E fits Weyerhaeuser because investors often focus on earnings power for a timber REIT that already generates steady income streams from its assets.
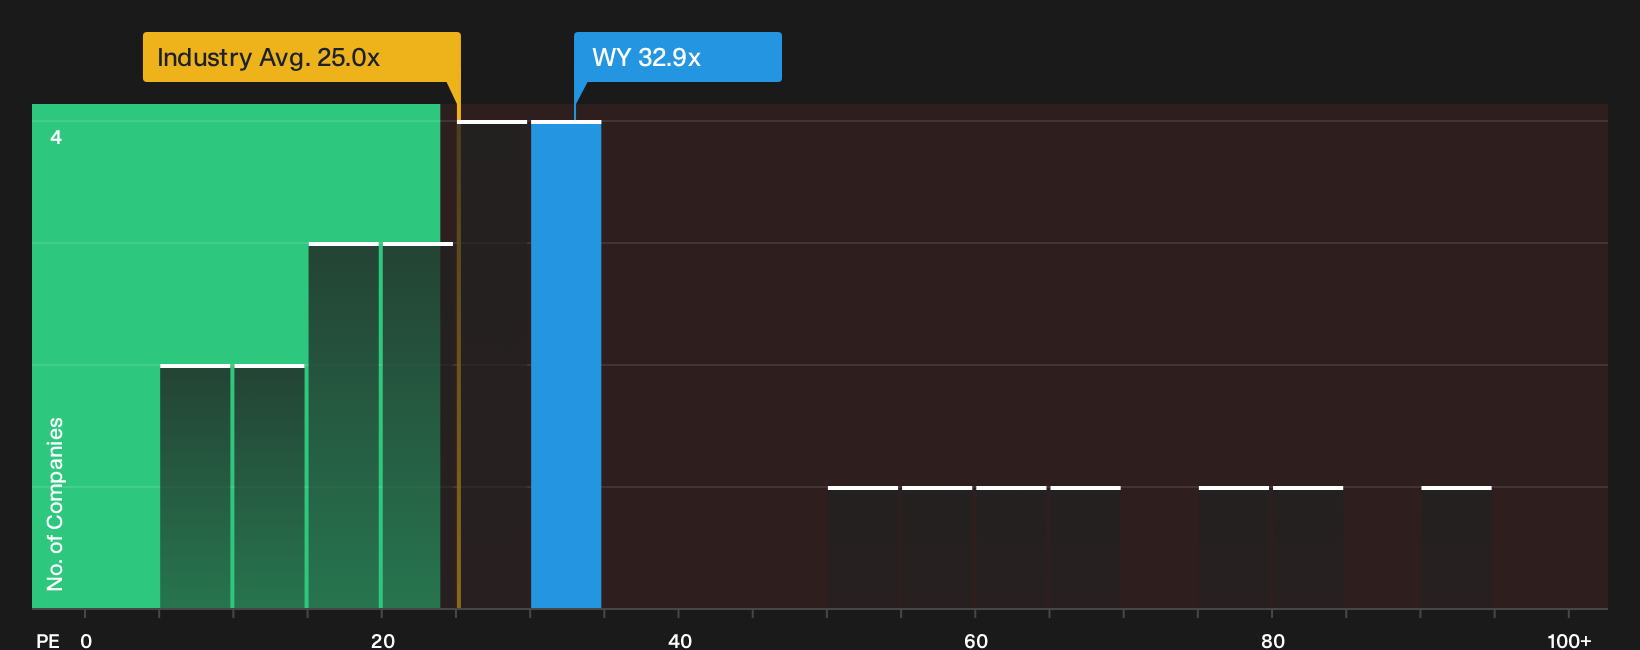
Based on the latest figures, Weyerhaeuser trades on a P/E of about 32.9x, which is roughly in line with the peer average of 34.2x but materially higher than the Specialized REITs industry average of around 16.2x. In this framework, the Fair Ratio, which adjusts for factors such as profitability, size and sector risk, points to a higher P/E than where the shares trade today, so the current multiple screens as undervalued relative to that tailored benchmark.
Because the new geothermal agreement with Hexagon Energy could reshape perceptions of Weyerhaeuser's earnings mix over time, it is notable that the current P/E still prices the stock at a discount to what the Fair Ratio suggests might be appropriate for the business. Explore the numbers behind Weyerhaeuser's P/E valuation.
The Weyerhaeuser Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as the bridge between Weyerhaeuser's current valuation puzzle and the assumptions investors might hold about its future earnings power. Each one spells out the growth, margin and earnings paths that would need to play out for the stock to be worth meaningfully more or less than today's price, and sets out the assumptions behind its implied value so you can compare them with actual results as they come through. They sit on Simply Wall St's Community page for Weyerhaeuser.
One of the top community narratives on Weyerhaeuser: 31% undervalued
"The main thing that has to go right is successful execution on the Climate Solutions and higher value wood products build out, including the Monticello TimberStrand mill, the biocarbon venture and the growing solar, wind, carbon and geothermal portfolios…"
Discover why this Narrative puts Weyerhaeuser at 31% undervalued.
The Weyerhaeuser share price is only one piece of your decision
Valuation gives you a snapshot of Weyerhaeuser today. The next question is how professional analysts currently map out this business a few years from now and how that compares with the price on your screen. Explore where analysts expect Weyerhaeuser to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com