
Akeso (SEHK:9926) After ESMO Trial Spotlight Is The Oncology Upside Already Priced In
Akeso (SEHK:9926) is back in focus after confirming that nearly 30 clinical studies of its bispecific antibodies will appear at ESMO 2026, including late breaking Phase III data for ivonescimab in advanced biliary tract cancer.
Against this backdrop of trial readouts and conference slots, Akeso’s share price has climbed over the past quarter, with a 90 day share price return of 14.10% and a 30 day gain of 10.36%, even though the year to date share price return is still down 13.95% and the 1 year total shareholder return has fallen 26.86%. The 3 year and 5 year total shareholder returns of 158.28% and 133.81% show that longer term holders have seen very strong compounding and suggest recent clinical headlines are being weighed against earlier gains and changing views on risk.
Capitalize on the momentum around Akeso’s oncology pipeline by scanning a curated set of late-stage and fundamentally strong biopharma names in the 620 high quality undiscovered gems.Akeso now trades at a sizeable discount to both analyst targets and some intrinsic value estimates despite the recent rebound. Is the market being sensibly cautious about clinical execution risk, or leaning too far to one side of fear, as the valuation suggests?
Most Popular Narrative: 38.4% Undervalued
Against a last close of HK$97.50, the most followed narrative suggests Akeso could be worth HK$158.28. This puts the current rebound in a very different light for anyone weighing oncology optionality against ongoing losses.
The initiation and ongoing progress of numerous Phase III trials for cadonilimab and ivonescimab across various cancer types indicate potential future approvals that could enhance revenue streams and market positioning globally.
The company's strong R&D pipeline, including advanced bispecific antibodies and ADC candidates, provides a foundation for long-term growth, setting the stage for potential increases in net margins as products move from development to commercialization.
See why 3 investors see Akeso as 38% undervalued.
The prevailing view leans on a HK$158.28 fair value estimate, built using a 7.45% discount rate and analyst forecasts for both revenue expansion and margin repair. That sits well above Akeso’s current HK$97.50 share price and implies the market is assigning a heavy discount to the oncology pipeline, the NRDL push and the ADC partnerships described in the narrative.
Those projections assume that CN¥11.8b of revenue and CN¥3.7b of earnings can be reached by around 2029, with the stock trading on a forward P/E of 42.2x at that point. The same storyline also expects a shift from a reported net loss of CN¥967.2m today to a profit margin of 31.2%, alongside forecast annual earnings growth of 51.31% and revenue growth around 30.8% per year.
Analyst targets are not tightly clustered, which signals genuine disagreement on how much of the oncology and immunology pipeline will translate into durable cash flows. The highest fair value estimate in that framework comes in at HK$226.04, while the lowest sits at HK$125.08. Readers need to decide where along that range their own expectations for trial execution, pricing power and competitive pressure fall.
Result: Fair Value of HK$158.28 (UNDERVALUED)
Still, the whole Akeso story hinges on costly late stage trials and on heavy dependence on ivonescimab and cadonilimab actually translating into durable commercial uptake.
Find out about the key risks to this Akeso narrative.
Another View: What Akeso’s Sales Multiple Is Telling You
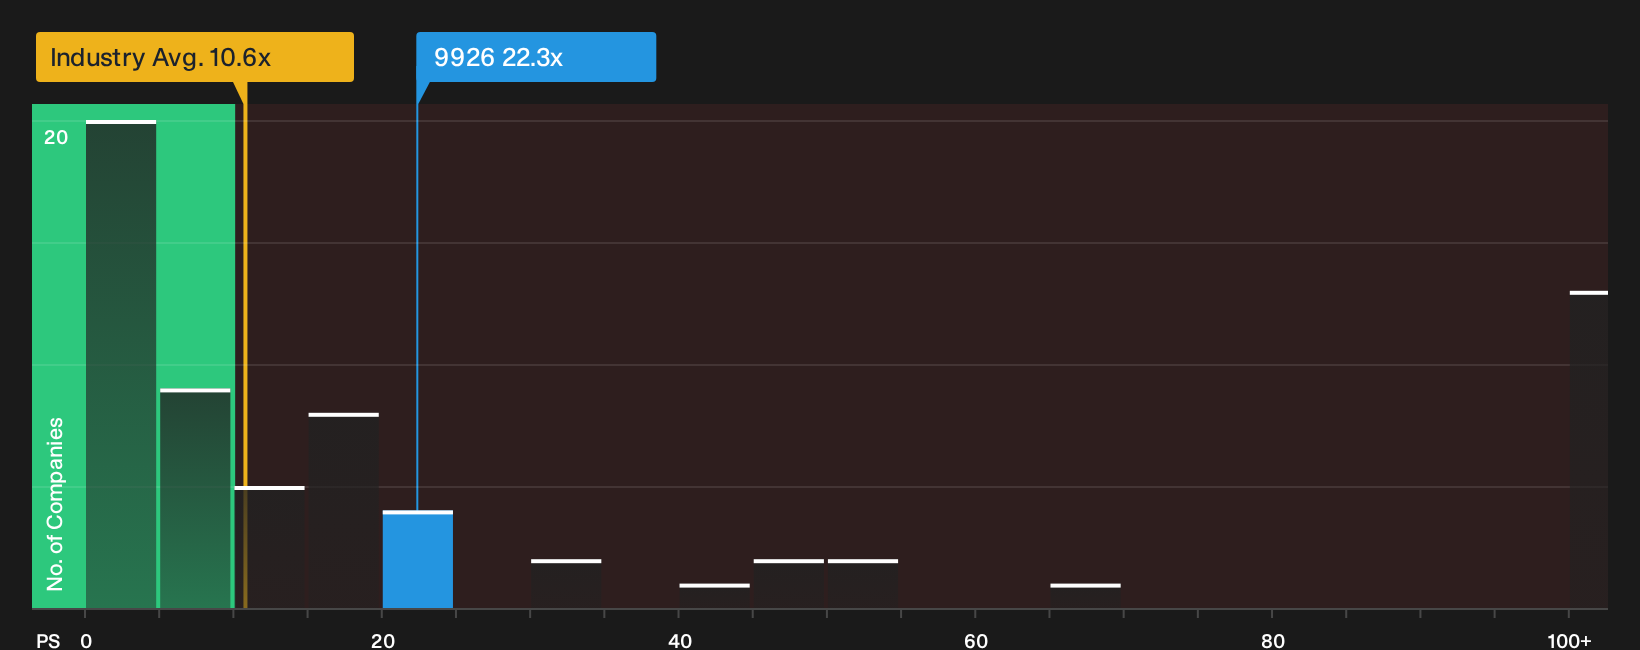
Akeso might screen as undervalued on fair value estimates, yet its current P/S of 22.3x is higher than the Hong Kong Biotechs average of 10.6x and also above a fair ratio of 13.4x. That gap points to valuation risk if sentiment on late stage oncology softens.
See what the numbers say about this price in more detail in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Does the debate around Akeso's valuation and oncology upside feel finely balanced or skewed? Take a moment to review the key rewards investors are focusing on, and pressure test them against your own expectations through the 2 key rewards.
Looking for more investment ideas beyond Akeso?
If Akeso has sharpened your focus on where capital could work harder, do not stop here. The broader opportunity set is too wide to ignore.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (198 results) that can help anchor your portfolio when sentiment shifts.
- Pursue quality at a discount through a 173 high quality undervalued stocks that lines up robust fundamentals with prices that appear out of sync.
- Prioritise sleep-at-night potential with a 229 resilient stocks with low risk scores that filters for calmer return profiles instead of constant volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com