
Can AptarGroup (ATR) Justify Its Price After The MGH Research Agreement?
AptarGroup (ATR) has placed its nasal drug delivery expertise at the center of a new research agreement with Massachusetts General Hospital, focusing on nose to brain transport for potential central nervous system therapies.
The AptarGroup share price has been choppy in recent months, with a 1-day share price return of 1.66% and a 7-day gain of 0.62%, but a 30-day share price decline of 6.94% that tempers short term momentum. Over longer stretches, a 1-year total shareholder return of 3.54% in decline alongside a 3-year total shareholder return of 5.52% and a 5-year total shareholder return of 11.62% points to modest progress over time rather than a rapid rerating. This suggests investors are still weighing the growth potential of initiatives like the MGH collaboration against perceived execution and valuation risks at a last close of US$125.45.
Scan AptarGroup alongside other specialist healthcare suppliers by reviewing the hand picked 37 healthcare AI stocks that could benefit as drug delivery and digital health tools gain more attention.
AptarGroup now trades at around US$125 while analyst and intrinsic estimates cluster much higher. Where does a reasonable fair value anchor for the stock actually land?
Most Popular Narrative: 26% Undervalued
AptarGroup last closed at $125.45 while the most followed narrative points to a fair value of about $170.14, framing a wide gap between current pricing and what long term earnings power could support under those assumptions.
Ongoing work to move from component supplier to a more integrated drug delivery and services partner, including formulation, analytical and regulatory support, clinical filling and digital patient tools, increases customer dependence on AptarGroup and can support higher value revenue and more resilient net margins.
See why 7 investors see AptarGroup as 26% undervalued.
Result: Fair Value of $170.14 (UNDERVALUED)
Still, the AptarGroup story depends on Pharma doing the heavy lifting, while weaker Beauty and Closures performance or persistent legal costs could easily unsettle that fair value gap.
Find out about the key risks to this AptarGroup narrative.
Another View: AptarGroup Through The P/E Lens
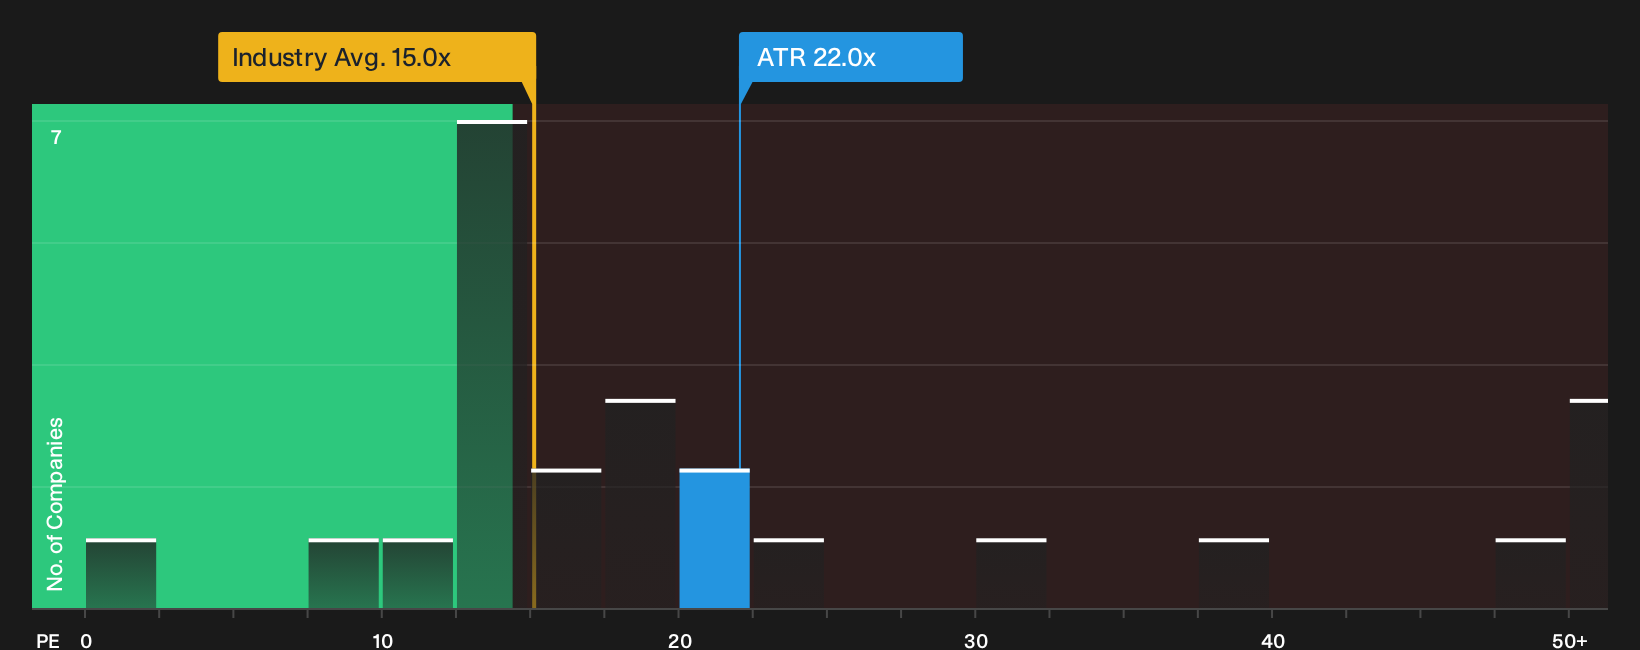
The story looks very different once the focus shifts from discounted cash flows to plain P/E. AptarGroup trades on about 22x earnings, while the global packaging industry sits near 15.3x and close peers around 16.9x. A fair ratio of 18.7x suggests investors are paying a premium that could compress if expectations cool. Is that premium a margin of safety or a margin of error for you?
See what the numbers say about this price gap in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of enthusiasm and hesitation around AptarGroup feels familiar, that is exactly why the data matters more than the headline. For a full picture of both upside and downside drivers, see 4 key rewards and 2 important warning signs.
Looking for more AptarGroup sized investment ideas?
Do not stop your research at AptarGroup. Broaden your watchlist with a few focused screens that surface different types of opportunities before the crowd catches on.
- Target potential mispricings by scanning a curated 29 high quality undervalued stocks that brings together quality businesses trading below many investors' implied expectations.
- Strengthen income potential by reviewing a hand picked 7 dividend fortresses that concentrates on higher yielding companies with a focus on durability.
- Protect the downside by filtering for a 30 resilient stocks with low risk scores that highlights businesses with more resilient profiles when conditions become less forgiving.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com