
Should First Two Story HUD Code Home Require Action From UMH Properties (UMH) Investors?
- UMH Properties recently attended HUD's 2026 Innovative Housing Showcase on the National Mall, displaying a HUD-code two-story manufactured home from Champion Homes and an off-frame multi-section model from Cavco Industries, both focused on high-quality affordable housing.
- The debut of a HUD-code two-story design and an off-frame multi-section home gives UMH Properties tangible product examples that align with policy discussions on affordability, construction methods, and future zoning rules.
- We will now look at how UMH Properties' investment narrative could be influenced by its HUD-code two-story manufactured home showcase.
Scan beyond UMH Properties and compare its push into manufactured housing with a handpicked list of solid balance sheet and fundamentals (23 results) that is leading progress in real-world affordable housing solutions.
UMH Properties Investment Narrative Recap
To own UMH Properties, you need to believe the manufactured housing shortage and regulatory support for HUD-code homes keep demand for its 145 communities and 27,100 sites healthy. The HUD Innovative Housing Showcase fits that belief but does not change the fact that near term progress still leans on filling sites, managing costs, and keeping home sales profitable.
The biggest near term swing factor remains access to capital on acceptable terms, given earnings cover interest and dividends only modestly. Rising borrowing costs or slower acquisition opportunities would bite hardest. Tenant credit quality, lower profit margins in home sales, and elevated operating expenses remain the key operational pressure points.
The HUD-code two story and off-frame models on the National Mall tie directly into UMH Properties' long running push to align with HUD and zoning reforms. That exposure supports the existing catalyst around regulatory momentum for manufactured housing, which is already central to analysts' expectations for new site development and higher net operating income over time.
With no fresh corporate announcements beyond this HUD event, the focus stays on how effectively UMH converts that policy spotlight into practical wins such as community expansion, home sales volume, and occupancy. Execution here matters because earnings growth expectations, a relatively high P/E, and limited coverage of interest and dividends leave less room for operational missteps.
UMH Properties' current analyst narrative points to forecast revenue of $330.1 million and earnings of $19.7 million by 2029, based on an assumed 7.5% yearly revenue growth rate and a move from $8.8 million in earnings today to that 2029 consensus level, which is an increase of roughly 2.2 times.
Uncover why UMH Properties' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
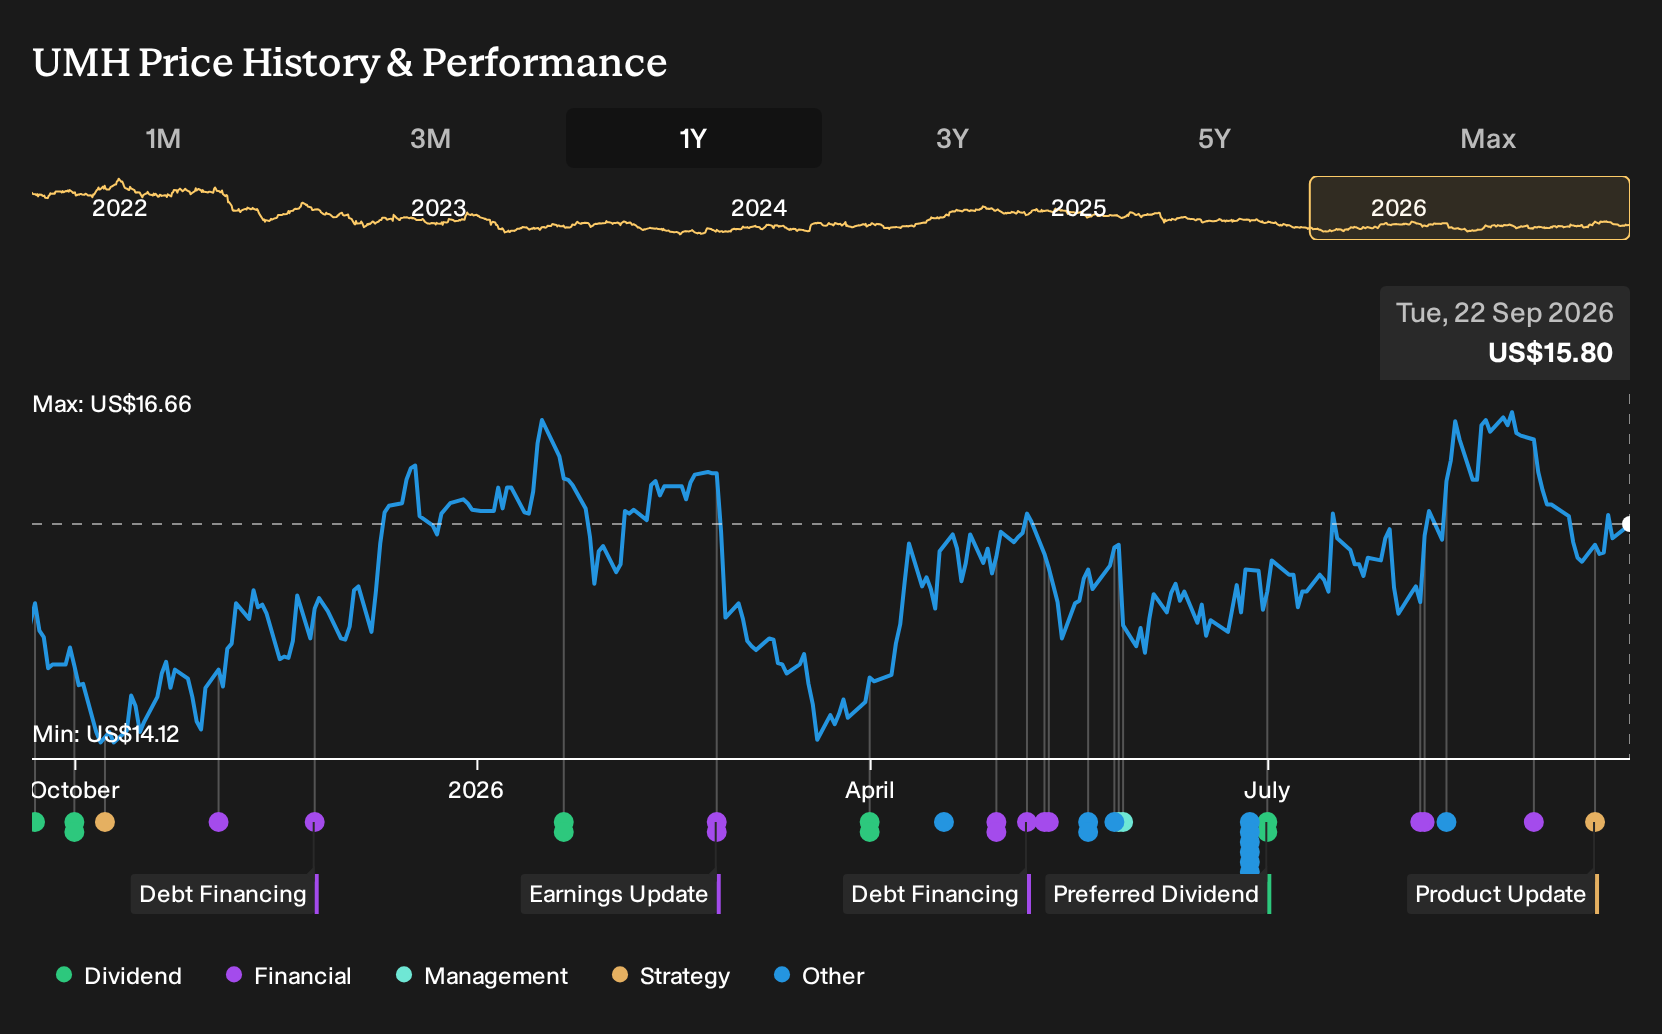
Exploring Other Perspectives
The alternate view on UMH Properties leans heavily on margin risk. Where the baseline expects earnings of $19.7 million by 2029, the lowest analysts plug in just $7.3 million on roughly $333.8 million of revenue. Those forecasts were set before this HUD showcase, so treat them as moving parts that could shift as you weigh the impact of UMH's two new homes on future profitability assumptions.
Explore 3 other UMH Properties fair value estimates, including one that suggests as much as 31% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UMH Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking For More Ideas Beyond UMH Properties?
If you want to pressure test your view on UMH Properties and widen your watchlist, the Simply Wall St Screener can surface other businesses with very different risk and return profiles.
- For investors hunting for quality at a discount, start with a 29 high quality undervalued stocks that combine solid fundamentals with prices that screens flag as below their estimated worth.
- If capital preservation sits high on your list, filter for stability using a 30 resilient stocks with low risk scores that score well on volatility and balance sheet strength.
- When income is the priority, focus on reliable cash returns to shareholders through a 7 dividend fortresses that target higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com