
Is Fastly (FSLY) Fully Valued On Its AI Edge Security Push?
Fastly (FSLY) grabbed investor attention after its stock climbed 15% following the launch of three new AI-focused security products designed to manage model and agent traffic directly at the network edge.
The recent jump sits on top of a much bigger move. Fastly’s 90-day share price return of 59.22% and year-to-date share price gain of 155.94% point to strong positive momentum. At the same time, the 1-year total shareholder return of 204.67% highlights how powerful that trend has been over a longer stretch, even though the 5-year total shareholder return of 34.73% below zero shows earlier investors have not all been rewarded yet.
Scan how Fastly’s AI edge story compares with other potential breakouts by reviewing the hand-picked 85 AI infrastructure stocks that is now setting the pace for infrastructure behind machine learning and real-time security.
Fastly now trades only about 4% below the average analyst target, even as one valuation model sits far higher. After the AI fueled surge, is this a justified safety margin or a mispriced opportunity?
Most Popular Narrative: 3% Undervalued
Fastly’s most followed valuation story pegs fair value at $27.00, only slightly above the last close at $26.08. This keeps the spotlight firmly on how durable its security and compute expansion really is.
The acceleration of cloud migration and edge computing, combined with Fastly's increased product velocity (especially in Compute and adaptive observability analytics at the edge), expands the company's addressable market and underpins durable multi-year revenue growth.
Successful execution of a platform-based cross-sell and upsell strategy (with nearly 50% of customers now using 2+ products and these generating over 75% of revenue) boosts wallet share, increases net retention rates, and supports higher revenue per customer.
See why 30 investors see Fastly as 3% undervalued.
Result: Fair Value of $27.00 (UNDERVALUED)
Still, Fastly’s reliance on a concentrated group of large customers and heavy ongoing spend on network and R&D could quickly test that 3% undervalued thesis.
Find out about the key risks to this Fastly narrative.
Another View: Fastly Through The Sales Lens
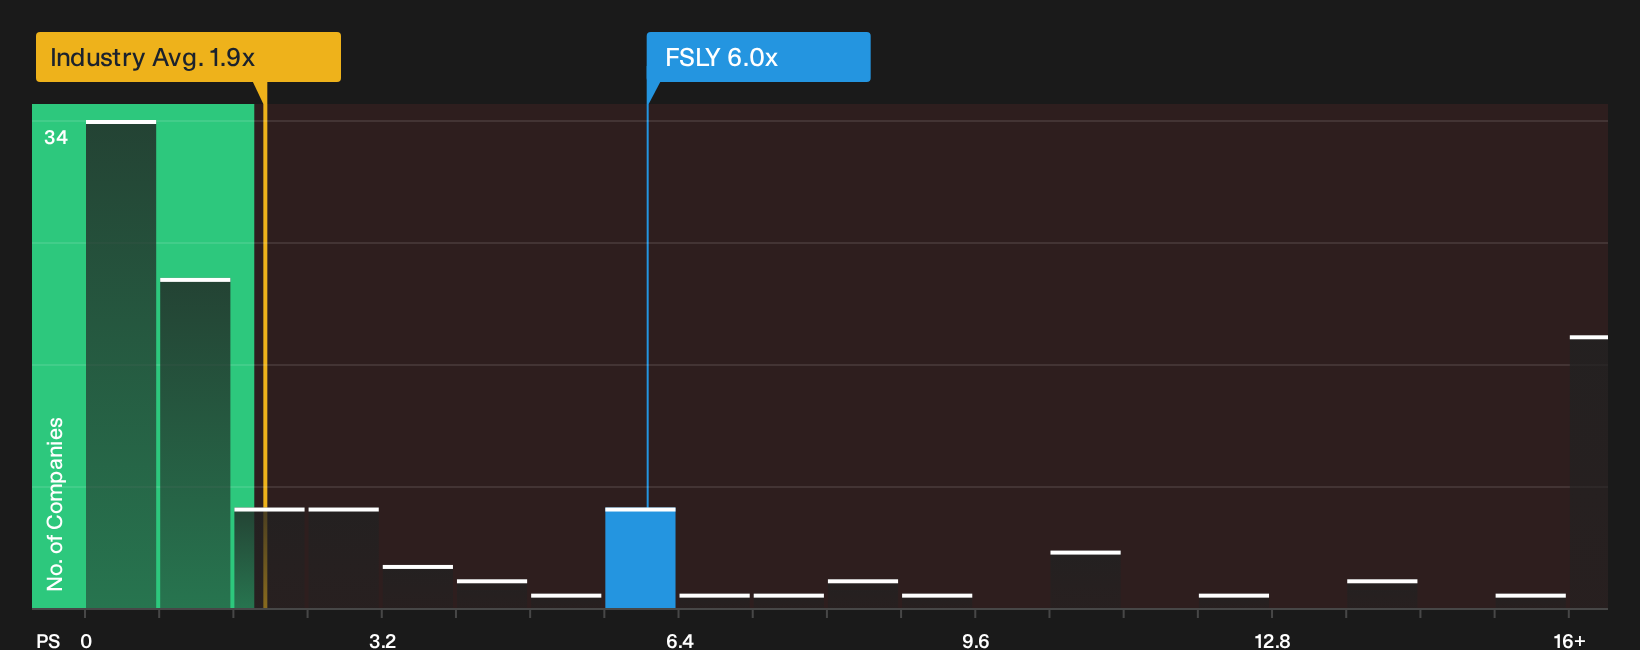
Fastly looks inexpensive based on its narrative, but its current P/S ratio of 6x is well above the US IT industry at 1.9x and above its own fair ratio of 4.5x. That gap points to valuation risk if sentiment cools. Is the AI edge story strong enough to keep investors paying a premium?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Fastly story so far. Move quickly, review both the positive and negative factors, then weigh the 1 key reward and 3 important warning signs against your own expectations.
Hunting For Your Next Idea Beyond Fastly?
If Fastly has sharpened your interest in AI and infrastructure, do not stop here. Broaden your watchlist with focused idea sets built from clear, transparent data.
- Target potential mispricing by scanning a curated pool of companies trading below their assessed value using the 29 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Seek differentiated opportunities by reviewing a hand picked group of companies with strong fundamentals via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com