
Toyota (TSE:7203) Stock May Be Undervalued As Robot Rollout Nears
Toyota Motor has delivered a 66.2% return over the past 5 years, which puts a lot of expectation into the share price and raises a straightforward question for investors about how well that move lines up with its earnings power today.
- That 66.2% gain over 5 years means anyone looking at Toyota Motor now is effectively asking whether the market is already reflecting the earnings profile that drove those returns.
- Recent news around Toyota's push to deploy in house humanoid robots across its plants, alongside restructuring moves in China, can influence how investors think about future efficiency, capital spending and the timing of cash flows that feed into earnings.
- Your read on Toyota Motor is one view; the desks covering it have another. See what analysts think Toyota Motor's shares could be worth.
The stock's next move may depend on whether Toyota Motor's current price is well supported by the earnings it is generating today and is expected to produce in the coming years.
If you want a broader starting point for research alongside Toyota Motor's robotics push and earnings story, apply the same lens to 95 robotics and automation stocks.
Is Toyota Motor a Bargain on Earnings?
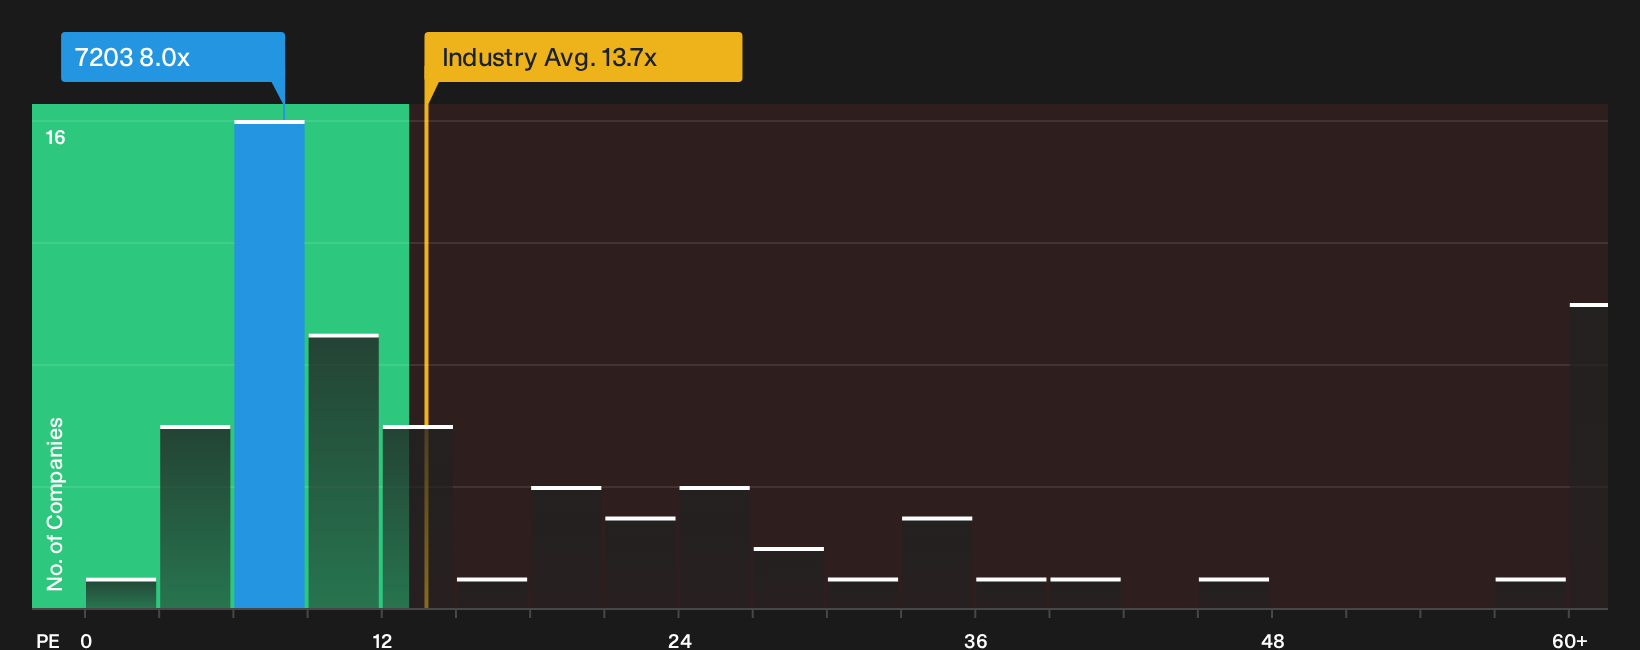
The P/E lens suits Toyota Motor because earnings remain a primary anchor for how investors weigh a mature auto group with heavy capital needs. On this measure, the stock trades at about 8.0x earnings compared with an Auto sector average near 13.8x and a peer group around 11.7x. That points to a clear discount to both the wider industry and closer rivals on simple headline earnings.
Because the model based on Toyota Motor's growth profile, profitability, size and risk points to a higher earnings multiple than where the shares trade today, the current P/E looks undervalued against that tailored benchmark. News around restructuring in China and the planned rollout of in house humanoid robots means investors are weighing sizeable investment commitments. Even with that backdrop, the market price still assigns a lower earnings multiple than both sector norms and this more customised yardstick. Explore the numbers behind Toyota Motor's P/E valuation.
The Toyota Motor Narrative: What Would Justify Today's Price?
Narratives for Toyota Motor pick up where the P/E puzzle leaves off. They spell out what kind of growth, margins and earnings path would need to hold for the current valuation to look either too low or too rich. Each storyline lays out the specific assumptions behind its view of fair value in plain terms, so you can compare those expectations with Toyota Motor's reported numbers as they arrive on Simply Wall St's Community page.
Views on Toyota Motor’s valuation split cleanly between a community bull camp and a group that sees the stock priced well ahead of itself.
Bull case: 33% undervalued
"Ongoing productivity gains from reinforced manufacturing foundations, stable capacity, and company wide efforts to lower breakeven volume are expected to convert current record sales and cost reductions into stronger free cash flow and earnings growth…"
Discover why this Narrative puts Toyota Motor at 33% undervalued.
Bear case: 42% overvalued
"The primary factor in recognizing Toyota as a company of the future is its technological breakthrough in solid-state batteries…"
Explore why this Narrative puts Toyota Motor at 42% overvalued.
One more angle on Toyota Motor that deserves a closer look
Before you park this research and move on, it is worth checking what Toyota Motor’s underlying risk checks are quietly flagging, since any small concern in those diagnostics can change how you read the valuation story. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com