
Is Clean Harbors (CLH) Undervalued On Its $600 Million Notes Offering?
Clean Harbors (CLH) has just priced a private offering of US$600 million in senior notes due 2034 at a 6.250% coupon, to fund pending acquisitions and refinance existing revolving credit facility borrowings.
At a share price of US$312.85, Clean Harbors has edged higher over the past quarter with a 90 day share price return of 4.71%, building on a year to date share price gain of 28.51% and a 1 year total shareholder return of 32.48% that extends to more than 3x over five years.
Spot similar acquisition driven stories and compare Clean Harbors with a curated group of list of solid balance sheet and fundamentals (23 results).Clean Harbors now trades well above its level at the start of the year, while both analyst targets and intrinsic value estimates still point higher. Is that gap signalling undervaluation, or simply reflecting optimism that has already been priced in?
Most Popular Narrative: 10.6% Undervalued
Against the last close at $312.85, the most followed narrative on Clean Harbors points to a fair value of $350, framing the current share price as below that internal estimate and tying the story closely to its infrastructure moat.
The most attractive part of the story is that the company's moat should potentially become more valuable over time.
As society becomes:
🏭 More industrialized
🧪 More technologically complex
🌎 More environmentally conscious
📜 More heavily regulated
the need for specialized environmental infrastructure is unlikely to disappear.
See why 2 investors see Clean Harbors as 11% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors narrative depends on regulators maintaining strict disposal standards and on acquisition integration going smoothly; any reversal could quickly weaken the perceived moat.
Find out about the key risks to this Clean Harbors narrative.
Another View: Clean Harbors Through The Earnings Lens
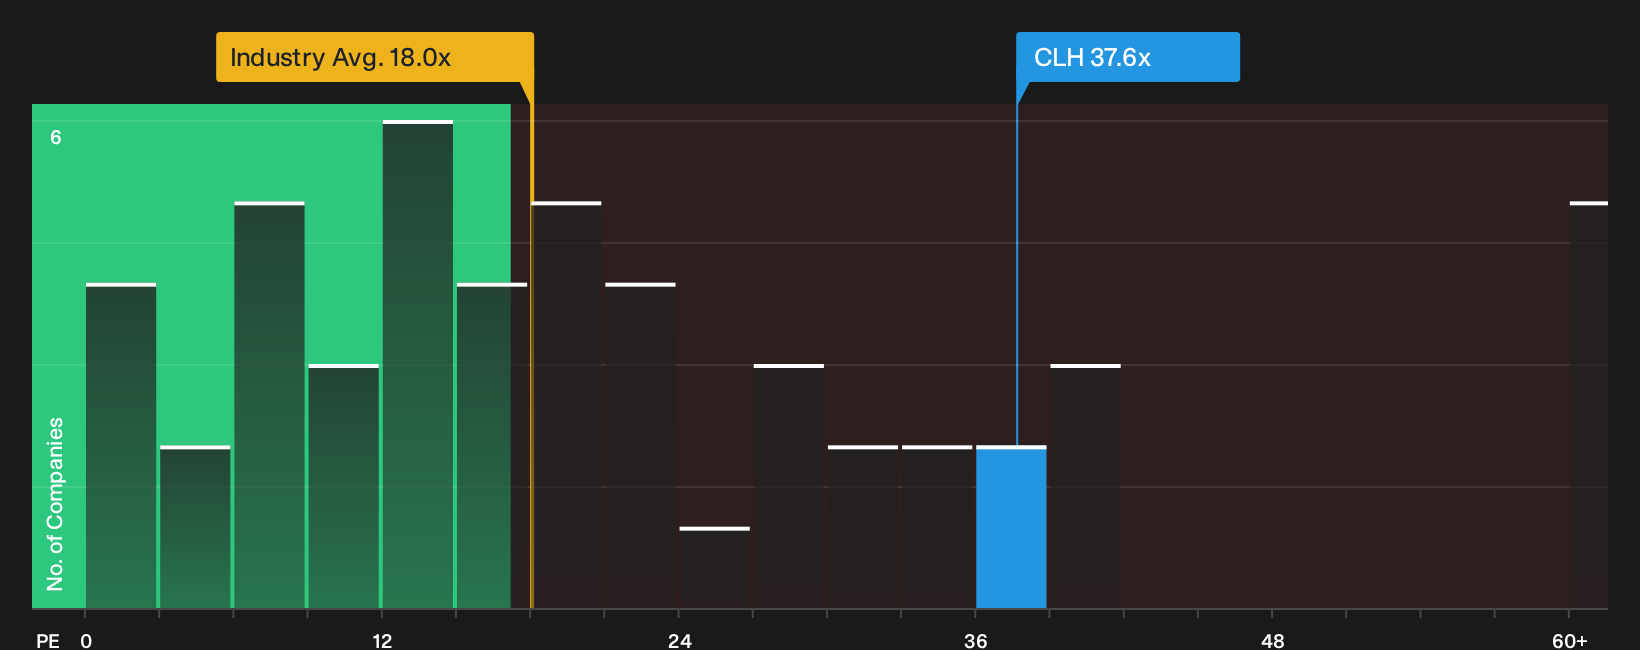
Clean Harbors might look undervalued on a fair value of $350, yet the simple earnings yardstick tells a different story. The stock trades on a P/E of 37.6x, which is roughly double the US Commercial Services industry at 18x and comfortably above peer levels around 27.8x. It also sits well above a fair ratio of 21.7x that the market could move towards, which raises the risk that a lot of good news is already reflected in the price.
For investors comparing valuation stories, that gap between the current multiple and the fair ratio prompts a practical question. Is this a quality premium that can be tolerated, or a pricing level that leaves less room for mistakes in the Clean Harbors thesis?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Clean Harbors story and valuation case make this a moment to move from reading to testing the numbers yourself. To weigh both the potential upside and the downside being flagged, start with the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Clean Harbors?
If you only stop with Clean Harbors, you miss a wider field of opportunities that could suit different risk levels, income needs, and valuation preferences.
- Target potential value opportunities by scanning a curated 29 high quality undervalued stocks that filters for quality fundamentals at prices that may appeal to patient investors.
- Strengthen capital preservation by reviewing a focused 30 resilient stocks with low risk scores tailored for investors who want resilience to sit closer to the top of the priority list.
- Expand your watchlist with a hand picked 16 high quality undiscovered gems that spotlights companies the broader market may not be paying close attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com