
What Is Behind Floor & Decor Holdings (FND) Latest Move?
Fresh concerns around Floor & Decor Holdings (FND) have resurfaced after recent analysis flagged weak long-term revenue trends and declining same-store sales. This has prompted investors to reassess demand durability and past expansion efforts.
Recent trading has been choppy for Floor & Decor Holdings. The share price is up 3.9% on the day and 6.5% over the past week, yet it remains down 9.5% over 30 days and 22% year to date, while the 1 year total shareholder return has fallen 40.1%.
Balance that Floor & Decor Holdings risk by scanning a curated set of retailers with sturdier fundamentals and price momentum using the list of solid balance sheet and fundamentals (23 results).
Floor & Decor Holdings now trades below the average analyst price target, yet sentiment has cooled after weaker same-store performance. Is this discount compensation for real risk, or has caution gone too far as valuation resets?
Most Popular Narrative: 14% Undervalued
On the most followed narrative, Floor & Decor Holdings screens as undervalued, with a fair value of about $56.95 against the latest $49.09 close. This puts a lot of weight on how the long-run store rollout and earnings profile play out.
Floor & Decor's ongoing aggressive store expansion strategy, opening 20 new warehouse-format stores this year and at least 20 planned for next year, with the infrastructure to accelerate openings further as housing market conditions improve, positions the company to capture outsized revenue growth and future operating leverage as end-market demand returns.
The company's deepening relationships with pro customers, who now account for ~50% of sales and are growing faster than the company average, alongside targeted investments in design services that drive higher average ticket and margin, set the stage for sustained same-store sales growth and margin expansion as project complexity and frequency increase.
See why 13 investors see Floor & Decor Holdings as 14% undervalued.
Result: Fair Value of $56.95 (UNDERVALUED)
Still, the bullish Floor & Decor Holdings story can crack if aggressive store openings weigh on profitability or if housing related softness keeps comparable sales under pressure.
Find out about the key risks to this Floor & Decor Holdings narrative.
Another View On Floor & Decor Holdings Valuation
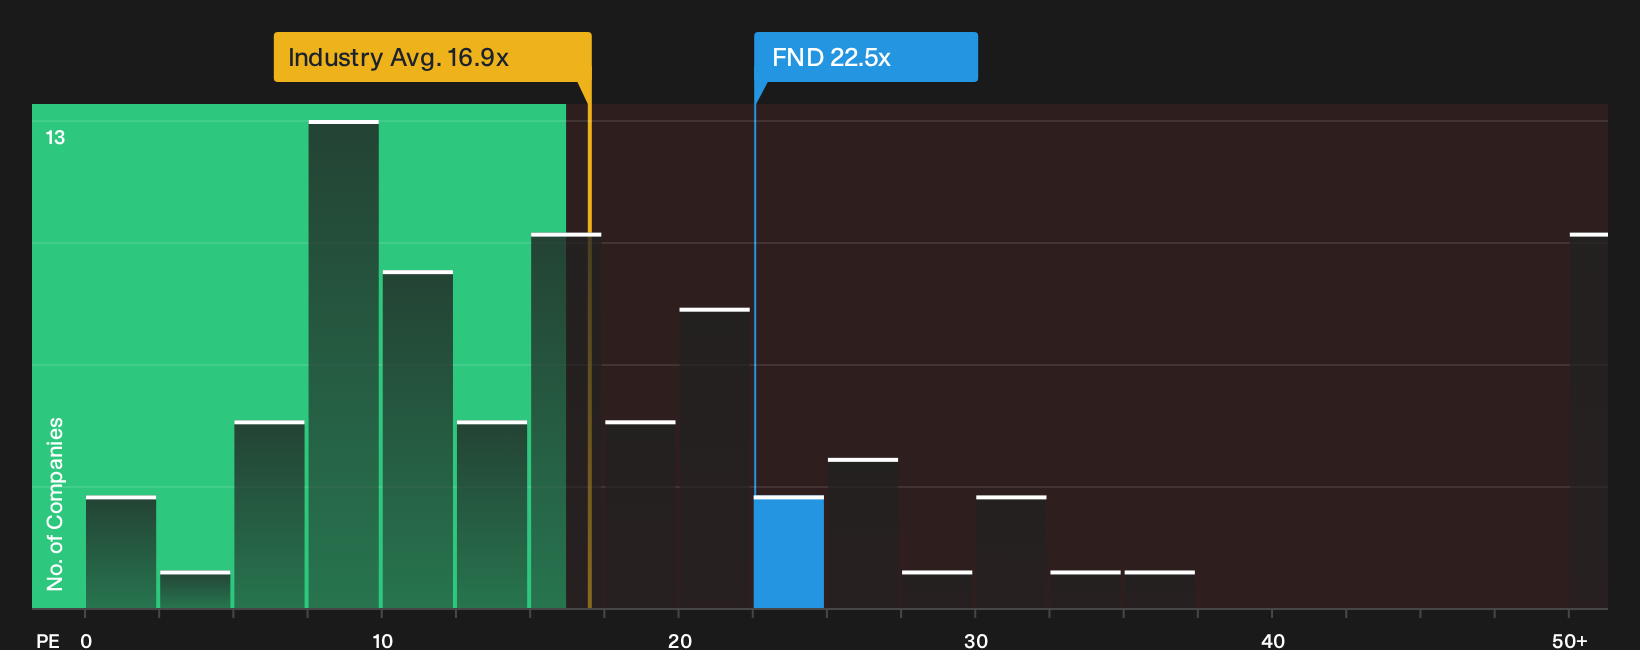
The analyst narrative points to Floor & Decor Holdings trading below an estimated fair value, yet the market is attaching a rich P/E of 22.5x. That compares with 16.6x for the US Specialty Retail group and a fair ratio of 12.8x. The stock looks expensive on this measure, which raises a simple question for investors: Is the market paying up for growth that might not arrive on the schedule implied by the story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Worried the Floor & Decor Holdings story sounds either too cautious or too optimistic right now? Move quickly, compare that feeling with the data, and focus on what the market is already concerned about by reviewing the 1 important warning sign.
Ready For More Investment Ideas Beyond Floor & Decor Holdings?
You have seen how sentiment can swing on one stock. Do not stop here when a broader watchlist could sharpen your next investing decision.
- Target dependable balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) to find companies built to handle tougher conditions.
- Zero in on potential mispricings by reviewing the 29 high quality undervalued stocks and see which businesses the market may be overlooking right now.
- Build a more defensive income stream by checking the 7 dividend fortresses and focus on payouts that might complement your growth holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com