
Will Bigger Credit Line Change AutoNation (AN) Narrative
- AutoNation amended and restated its unsecured credit agreement in mid September 2026, lifting the revolving facility to US$2.0b, expanding the accordion capacity to US$1.0b, extending maturity to 2031, and keeping commitment fees and loan margins at the same or lower levels.
- The revised facility gives AutoNation extra balance sheet flexibility for acquisitions and capital deployment while maintaining leverage and interest coverage covenants that still anchor the business to a defined risk profile.
- This article examines how AutoNation's larger US$2.0b revolving credit line affects the investment narrative around growth, risk, and flexibility.
Compare AutoNation's expanded firepower with peers by scanning companies that also pair flexible credit with disciplined balance sheets, using our curated list of solid balance sheet and fundamentals (23 results).
AutoNation Investment Narrative Recap
To own AutoNation, you need to be comfortable with a traditional dealer model that is leaning harder into high margin after sales, used vehicles, and its AN Finance arm. The bigger revolving credit line does not change that core story. It mainly gives the retailer extra room to fund store expansion and digital projects if demand holds up.
The trade off is clear. Extra liquidity can support acquisitions and AutoNation USA growth, but it sits against risks like pressure on used vehicle profitability, rising competition from online focused platforms, and the long term impact of EV adoption on service revenue. In the near term, the credit tweak looks more like plumbing than a major catalyst.
The most relevant recent move is the Fifth Amended and Restated Credit Agreement signed on 14 September 2026. AutoNation now has a US$2.0b revolving facility, a US$1.0b accordion feature, and a maturity date pushed out to 2031. Commitment fees and loan margins are the same or lower than before, which matters if funding costs stay in focus.
Those terms sit next to covenants that still cap leverage at 3.75x, with a temporary step up to 4.25x after a material acquisition, and require at least 3.00x interest coverage. For investors, that means any push into more used stores, service capacity, or AutoNation Finance growth still has to respect those limits, which can help keep balance sheet risk in check while management pursues its current catalysts.
Analyst Forecasts Around AutoNation's Credit Headroom
AutoNation's narrative projects US$29.9b revenue and US$816.2m earnings by 2029. This assumes 2.8% yearly revenue growth and an earnings increase of about US$137m from US$679.0m today.
Uncover how AutoNation's fair value indicates a 43% potential upside to its current price before the market closes that gap.
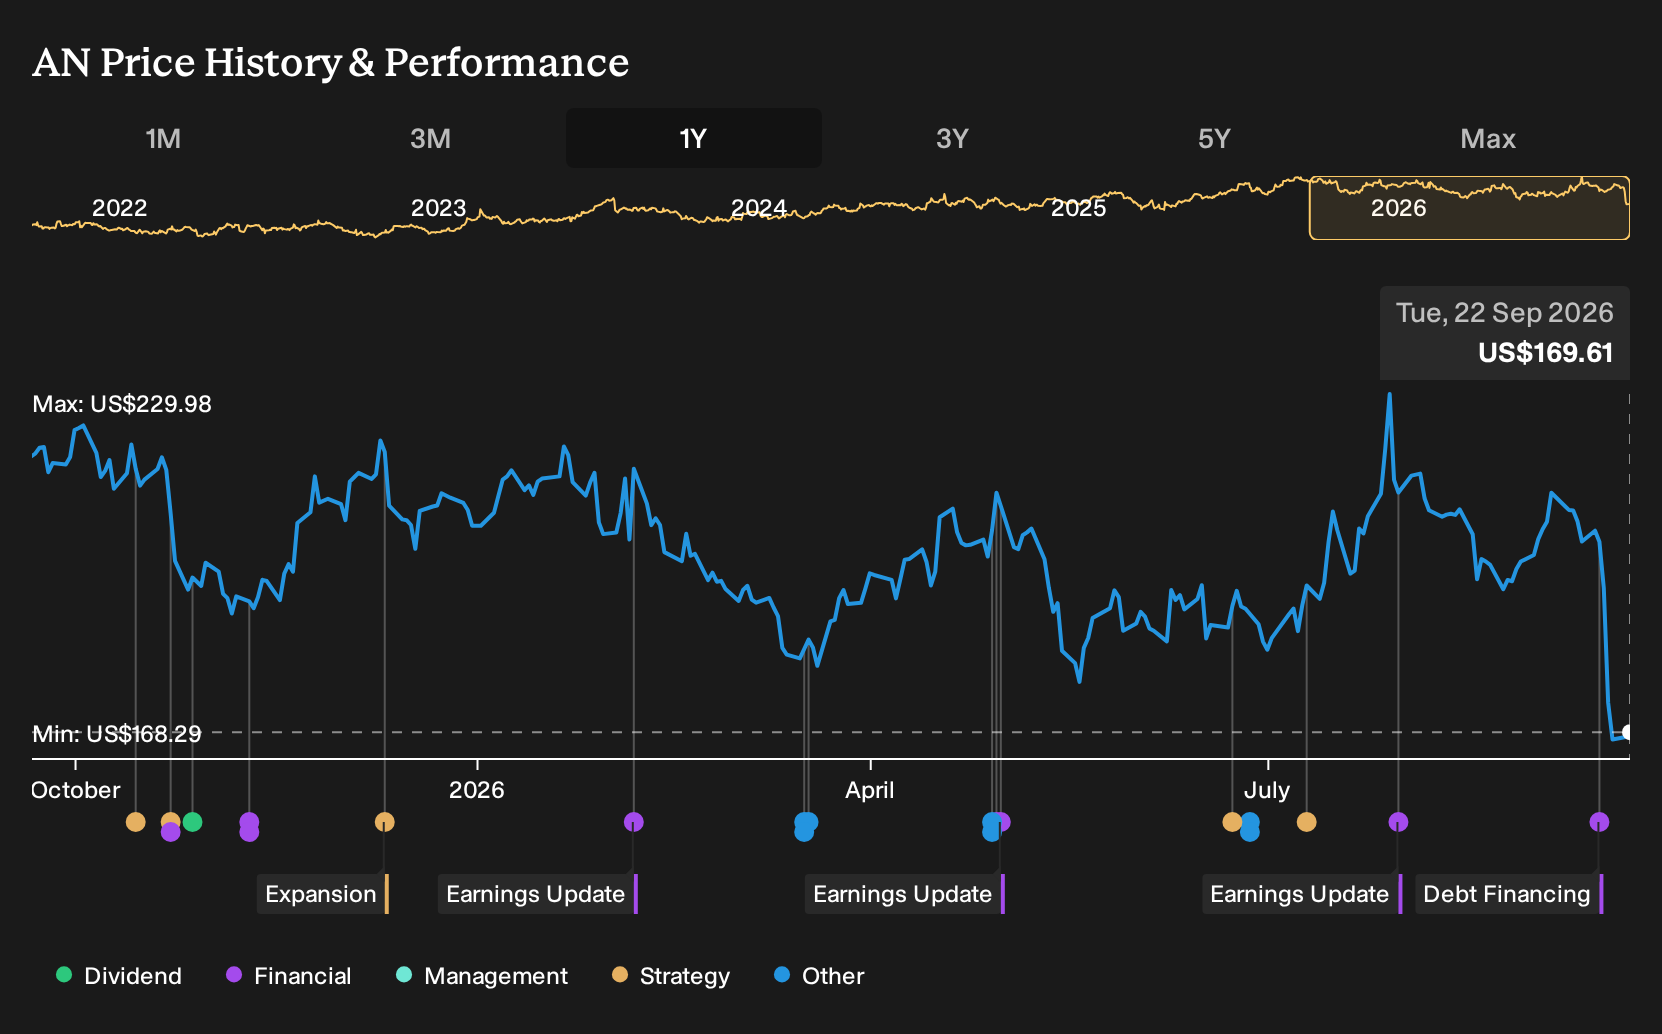
Exploring Other Perspectives
Some of the most optimistic analysts frame AutoNation’s expanded credit as fuel for faster AutoNation Finance growth, not just more store spending. Before this news, the bullish cohort already penciled in US$31.6b revenue and US$881.5m earnings by 2029. You can judge for yourself whether this extra balance sheet capacity nudges those already upbeat forecasts even higher.
Explore another AutoNation fair value estimate, including one that suggests as much as 43% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AutoNation research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking For More Investment Ideas Beyond AutoNation?
Once you have a view on AutoNation, it can help to compare it with other opportunities that match your risk appetite, income needs, or value focus. The Simply Wall St Screener lets you do that in a structured way using the same data framework.
- If you want to focus on value and quality together, start with a curated set of 29 high quality undervalued stocks that already pass basic fundamental checks.
- For investors who care most about stability, filter for resilient businesses with stronger balance sheets and lower risk profiles using the 30 resilient stocks with low risk scores.
- If you are hunting for underfollowed ideas with solid fundamentals, scan through a hand picked pool of 16 high quality undiscovered gems that might not yet be widely tracked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com