
Akamai Technologies (AKAM) Expands MuleSoft Tie Up, Is The Undervaluation Case Still Intact?
Akamai Technologies (AKAM) is back in focus after expanding its collaboration with MuleSoft to tighten API security and governance, while its TrafficPeak tooling supported ITV’s World Cup streaming reliability and real-time threat monitoring.
Akamai Technologies has seen momentum pick up recently, with a 7-day share price return of 12.28% and a 30-day share price gain of 7.17%, while the stock’s year-to-date share price return of 39.06% and 1-year total shareholder return of 57.22% point to strong recent performance, despite a slight 90-day share price decline of 0.95%.
Scan how Akamai Technologies fits into the broader security and cloud trend, and size up other potential contenders through our hand picked 85 AI infrastructure stocks.
The recent jump in Akamai Technologies raises a simple tension. Are investors finally catching up to what its security and cloud push already supports, or has sentiment sprinted ahead of what the current fundamentals justify?
Most Popular Narrative: 23% Undervalued
Akamai Technologies last closed at $118.34, while the most followed narrative pins fair value closer to $153.31, which frames the recent price strength as only part of the story rather than the full rerating some might assume.
The proliferation of AI applications requiring secure, ultra-low-latency infrastructure benefits Akamai's globally distributed platform, as evidenced by new AI Gateway and Firewall for AI offerings, which positions the company to capture new AI-driven workloads, supporting both future top-line growth and potentially higher net margins via value-added solutions.
See why 33 investors see Akamai Technologies as 23% undervalued.
Result: Fair Value of $153.31 (UNDERVALUED)
Still, the Akamai Technologies story can break if heavy cloud and compute spending continues to squeeze margins, or if a few large contracts slow or disappoint.
Find out about the key risks to this Akamai Technologies narrative.
Another View: Akamai Technologies Looks Pricey On Earnings
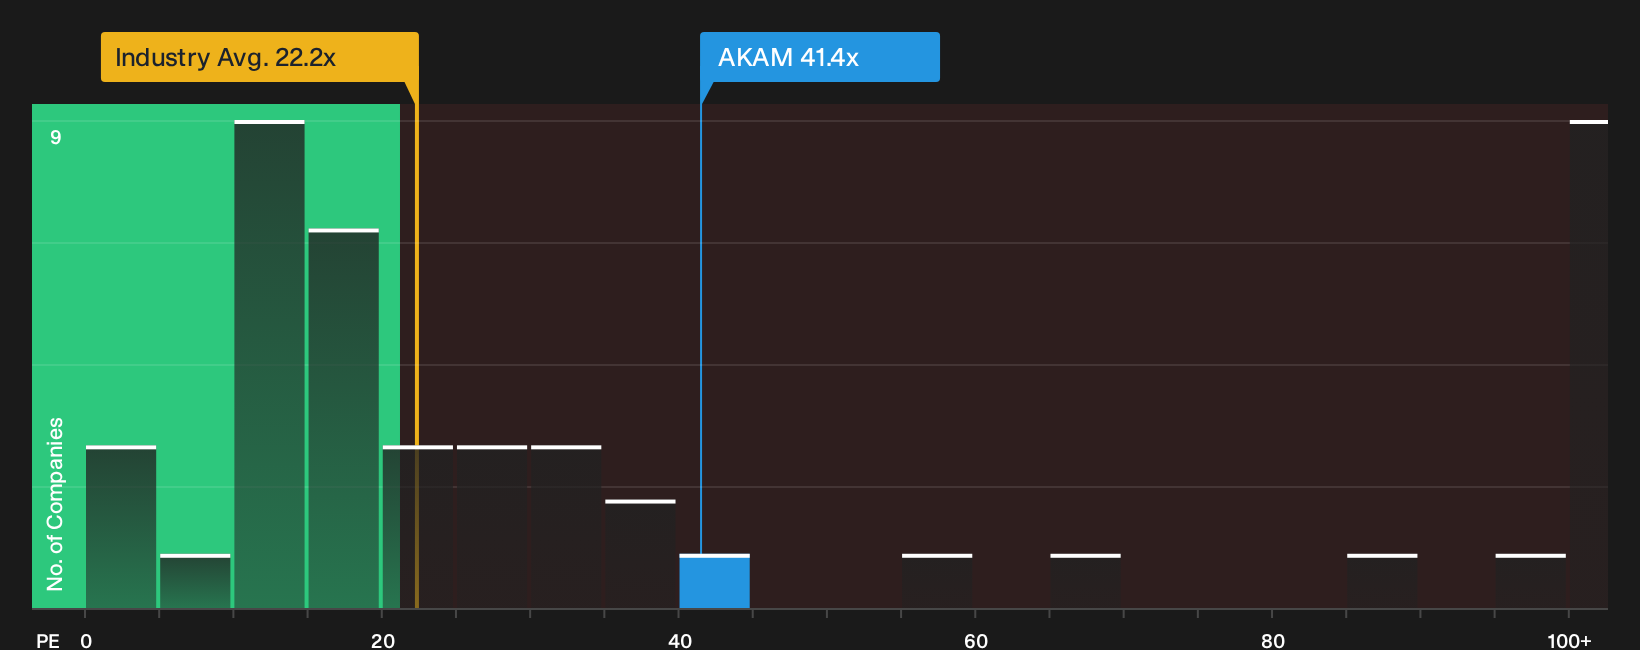
Analyst narratives point to Akamai Technologies trading below a fair value of $153.31, yet its P/E of 41.4x tells a different story. That multiple sits well above the US IT sector on 22.2x and above a fair ratio of 36.7x. This suggests there may be less margin for error if growth or margins disappoint.
Investors weighing these signals need to ask a simple question: Is this a quality business priced for perfection, or is the earnings multiple leaving too little room if expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Akamai Technologies are evident, so consider acting promptly, reviewing the numbers, and forming your own stance by weighing its 1 key reward and 1 important warning sign.
Looking for more Akamai Technologies sized ideas?
If Akamai Technologies has sharpened your focus on opportunity and risk, do not stop here. Broaden your watchlist and pressure test your thinking against fresh ideas.
- Target resilient cash generators by scanning a 29 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their strengths.
- Secure income-focused opportunities by reviewing a 7 dividend fortresses that pairs higher yields with businesses built to support ongoing payouts.
- Protect your downside by filtering for a 30 resilient stocks with low risk scores that screens for steadier profiles with fewer red flags on financial health.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com