
Did AI Supply Chain Rollout Just Shift SPS Commerce (SPSC) Stock Narrative?
- SPS Commerce reported a new suite of agentic AI tools across fulfillment, onboarding, analytics, and supply chain visibility, and confirmed MAX, its AI supply chain layer, is now generally available to tens of thousands of fulfillment customers.
- The business is embedding MAX directly into onboarding and operations so SPS teams can spend more time on customer needs and less on manual setup, which could reshape how efficiently the company serves its more than 300,000 trading relationships.
- We will now see how SPS Commerce's investment narrative could be affected by the rollout of MAX across its supply chain platform.
SPS Commerce Investment Narrative Recap
To own SPS Commerce, you need to believe retailers and suppliers keep leaning on outsourced supply chain software instead of building their own tools. The near term story is about whether MAX and agentic onboarding can support subscription growth while customer budgets remain tight. The latest AI rollout feels directionally helpful, but does not remove macro or spending risk.
The most important near term catalyst is execution on MAX inside fulfillment and visibility. If SPS Commerce can keep customers engaged and reduce onboarding friction, that can support network usage and limit ARPU pressure. The biggest risk remains cautious U.S. supplier spending, which could slow new deals and encourage invoice optimization.
The general availability of MAX across tens of thousands of fulfillment customers looks like the most relevant update. It directly touches onboarding, error detection, and supply chain visibility, which sit at the center of how this platform earns subscription and transactional revenue. Faster onboarding and fewer errors are operational levers, not just product headlines.
If MAX really keeps onboarding times tight and speeds exception handling, SPS Commerce could be better positioned against competition and commoditization risk. That would relate directly to the key catalyst investors watch, which is margin efficiency from automation, while still leaving considerable execution risk if customers delay projects or trim analytics spend.
SPS Commerce's current earnings are $78.0 million, with analysts expecting this to reach $166.5 million by 2029, which is an earnings increase of about 2.1x. That forecast lines up with an assumption of 6.1% yearly revenue growth and implies revenues of $922.9 million by 2029.
Uncover why SPS Commerce's fair value indicates a 10% potential downside to its current price, which leaves little room for error.
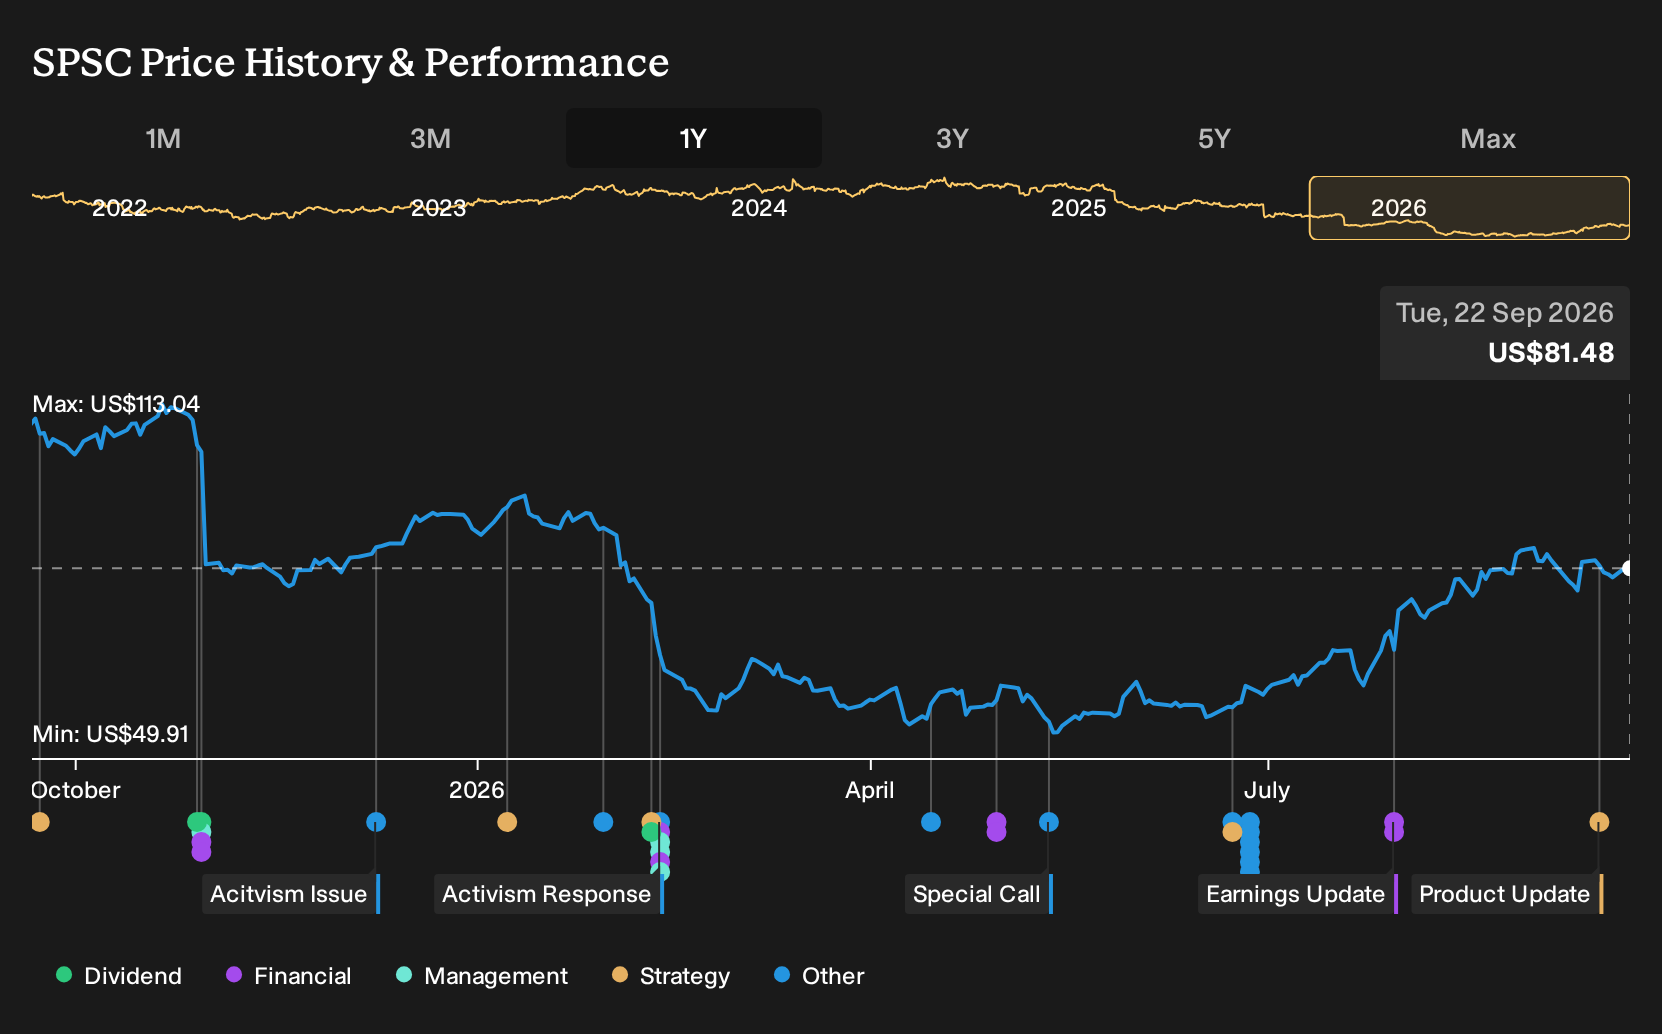
Exploring Other Perspectives
The most bearish analysts fixate on pricing pressure rather than MAX. They worry that in house AI and rival automation platforms could squeeze SPS Commerce’s connection based subscriptions. Those forecasts were already baking in slower growth, with revenues of about $912.1 million and earnings of $157.0 million by 2029. This new AI rollout could push that story in a different direction, so consider it one more reason to compare several narratives before deciding how you view the stock.
Explore 4 other SPS Commerce fair value estimates, including one that suggests as much as 41% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your SPS Commerce research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for SPS Commerce. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPS Commerce's overall financial health at a glance.
Looking For More Ideas Beyond SPS Commerce?
Once you have a view on SPS Commerce, it can help to line it up against other opportunities that fit different portfolio roles. The Simply Wall St Screener can surface focused shortlists so you are not drowning in tickers.
- If you are hunting for resilient balance sheets and cleaner fundamentals, filter for a list of solid balance sheet and fundamentals (23 results) that might handle tougher conditions with fewer surprises.
- For readers who want value opportunities with quality characteristics, start with 29 high quality undervalued stocks that combine stronger cash flows with more reasonable pricing.
- Income focused investors can narrow their search using 7 dividend fortresses that put a 5%+ yield side by side with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com