
Prestige Consumer Healthcare (PBH) Could Be 29% Undervalued Following Its Latest Bounce
Prestige Consumer Healthcare (PBH) moved onto investor radar after its recent share price swings, with the stock closing at $47.73 on 23 September 2026 following a mixed short term performance profile.
Over the past year, Prestige Consumer Healthcare has seen short bursts of buying interest followed by heavier selling pressure. The company has a 1-day share price return of 1.99% and a 7-day share price return of 2.25%, set against a year-to-date share price return that is down 22.04% and a 1-year total shareholder return that has fallen 24.21%. This performance points to fading momentum rather than a sustained rebound.
Spot under pressure in Prestige Consumer Healthcare and compare it with a curated 29 high quality undervalued stocks that share stronger recent return profiles or deeper valuation gaps.That kind of choppy record leaves a practical decision for you as an investor: Should you lean into Prestige Consumer Healthcare after this latest bounce, or hold back and wait for valuation to offer a clearer margin of safety?
Most Popular Narrative: 29% Undervalued
On the narrative view, Prestige Consumer Healthcare screens as undervalued, with a fair value of $66.80 against the latest close at $47.73. This puts the focus squarely on whether the current price reflects its cash generation and brand portfolio.
Prestige's strong and consistent free cash flow generation (~$245 million projected for the year) provides financial flexibility for continued deleveraging and opportunistic share repurchases, supporting future earnings per share (EPS) growth and value for shareholders.
See why 1 investors see Prestige Consumer Healthcare as 29% undervalued.
Result: Fair Value of $66.80 (UNDERVALUED)
Still, Prestige Consumer Healthcare faces pressure from ongoing supply chain issues around key eye care products and from an investor investigation into whether recent financial disclosures were misleading.
Find out about the key risks to this Prestige Consumer Healthcare narrative.
Another View on Prestige Consumer Healthcare’s Valuation
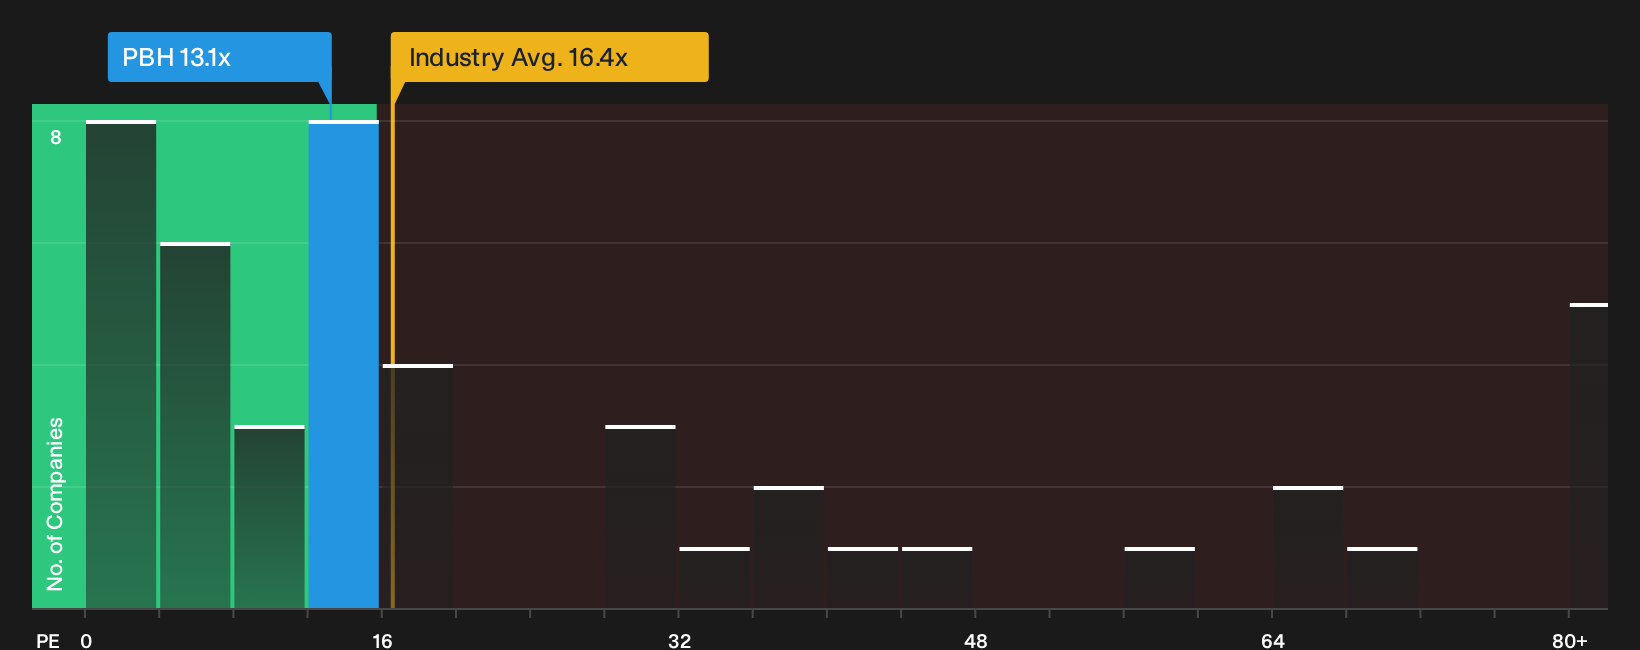
On a simple earnings multiple, Prestige Consumer Healthcare looks less cheap than the cash flow story suggests. The stock trades on a P/E of 13.1x, which is higher than the 10.3x average for direct peers, yet below both the US Pharmaceuticals group at 16.5x and its own fair ratio of 15.4x. That mix points to some valuation support, but it also raises the question of whether the discount reflects real business risks rather than just market pessimism.
For a closer look at how that earnings multiple compares with what the numbers imply, including the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Prestige Consumer Healthcare can easily cloud judgment, so move quickly to review the full picture and weigh both sides of the story for yourself. Then pressure test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Prestige Consumer Healthcare?
If Prestige Consumer Healthcare has you thinking harder about price and quality, do not stop with one ticker. Broaden your watchlist with focused screeners built to surface clear, data driven ideas.
- Target quality at a discount and scan a curated pool of stocks that combine fundamentals with marked valuation gaps through the 29 high quality undervalued stocks.
- Seek resilience first and filter for companies with stronger balance sheets and healthier fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Hunt for tomorrow's potential standouts and zero in on under-followed opportunities with solid metrics through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com