
SoftBank (TSE:9434) Could Be 6% Undervalued On Sceye Laser Tracking Test
Sceye’s recent world first stratospheric laser tracking test, run with SoftBank (TSE:9434) and Japanese research partners, gives investors a fresh angle on the telecom group’s push into high altitude platform systems and optical communications.
SoftBank’s latest Sceye test lands at a time when momentum in the stock has been picking up, with a 30-day share price return of 5.57% and a 90-day move of 22.04%. Meanwhile, the 1-year total shareholder return of 13.57% and 5-year total shareholder return of 101.29% point to gains that long term holders have already seen priced into the story.
Scan beyond SoftBank and see how other telecom and connectivity players are positioned around this theme with our hand picked 85 AI infrastructure stocks.
After a 22.04% move over 90 days and a share price sitting modestly below consensus targets, SoftBank now poses a simple timing call. Should investors step in after this run, or wait for a cleaner entry and a greater margin of safety?
Most Popular Narrative: 6% Undervalued
SoftBank’s most followed valuation story pegs fair value at ¥263.4, a touch above the last close of ¥248.1. This frames the recent Sceye news against an already optimistic set of expectations.
Planned rollout of homegrown large language models (LLMs) and commercial GPU as a service targeting Japan-based enterprises capitalizes on surging enterprise AI adoption. This is set to accelerate recurring revenues and support margin expansion from higher-value digital infrastructure services.
Integration of AI solutions (e.g., contact center agentic AI) into financial services partnerships with firms like Sumitomo Mitsui Card and PayPay creates new monetization channels. This further increases transaction volume and cross-selling opportunities, and supports top-line revenue and net income growth.
See why 6 investors see SoftBank as 6% undervalued.
Result: Fair Value of ¥263.4 (UNDERVALUED)
Still, the SoftBank story can break if rising network and data center costs squeeze margins faster than expected, or if tougher mobile competition caps pricing power.
Find out about the key risks to this SoftBank narrative.
Another View On SoftBank’s Valuation
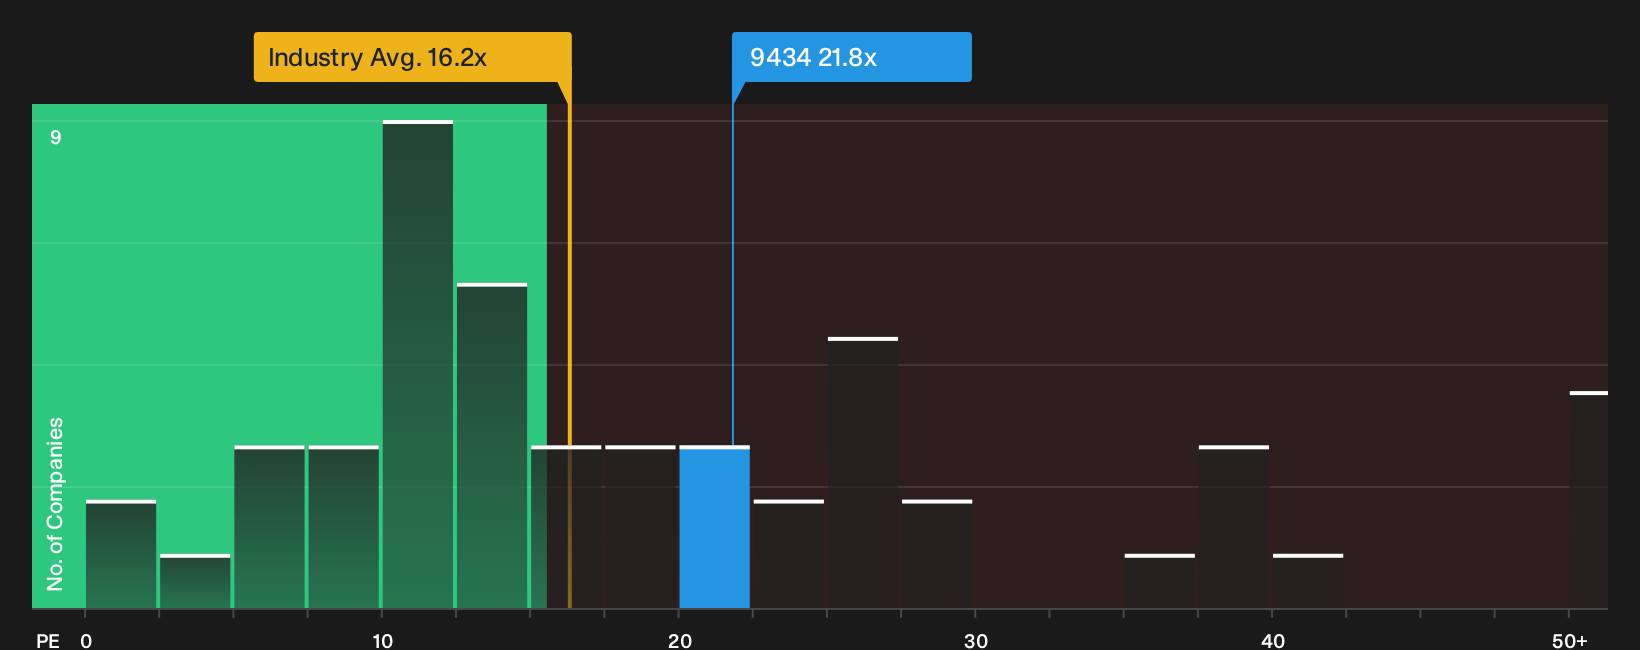
On multiples, SoftBank looks less forgiving. The shares trade on a P/E of 21.8x, while the Asian wireless telecom group sits at 16.2x, peers average 16.5x, and the fair ratio is 13.9x. That richer tag raises a simple question: Is the premium comfort, or is it crowding out future upside?
For a closer look at how this earnings multiple stacks up against what the numbers suggest the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the SoftBank story so far. If you want to move quickly and judge the balance for yourself, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SoftBank?
If SoftBank has your attention, do not stop there. Use a few targeted screeners to quickly surface other stocks that might better fit your plan.
- Target dependable payouts and keep your income watchlist sharp by reviewing the 14 dividend fortresses tailored for yield focused investors.
- Hunt for mispriced quality and see which companies show up in the 75 high quality undiscovered gems before they attract wider attention.
- Prioritize resilience and stress test your downside by checking the 21 resilient stocks with low risk scores that filters for sturdier balance sheets and calmer volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com