
Is YASKAWA Electric (TSE:6506) Fully Priced After A 42% Gain?
YASKAWA Electric has delivered a strong 42.3% return over the past year, even though shorter term moves have been more mixed, which naturally puts its earnings under the spotlight. With the share price recently closing at ¥4,383, the question is whether that level is adequately supported by the profits the business is currently generating.
- The 42.3% gain over the last 12 months raises the stakes for anyone asking if YASKAWA Electric's current earnings profile can support this kind of rerating.
- The group relies heavily on automation and motion control equipment, so future earnings may hinge on how efficiently it can convert that installed base into recurring, higher margin revenue and cash flow.
- The analysts covering YASKAWA Electric have run their own numbers. See what analysts think YASKAWA Electric's shares could be worth.
The issue now is whether YASKAWA Electric's present share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to cross check YASKAWA Electric against other earnings focused ideas, a targeted screen of 17 high quality undervalued stocks can be a useful next step in your research.
Does YASKAWA Electric Look Pricey on Earnings?
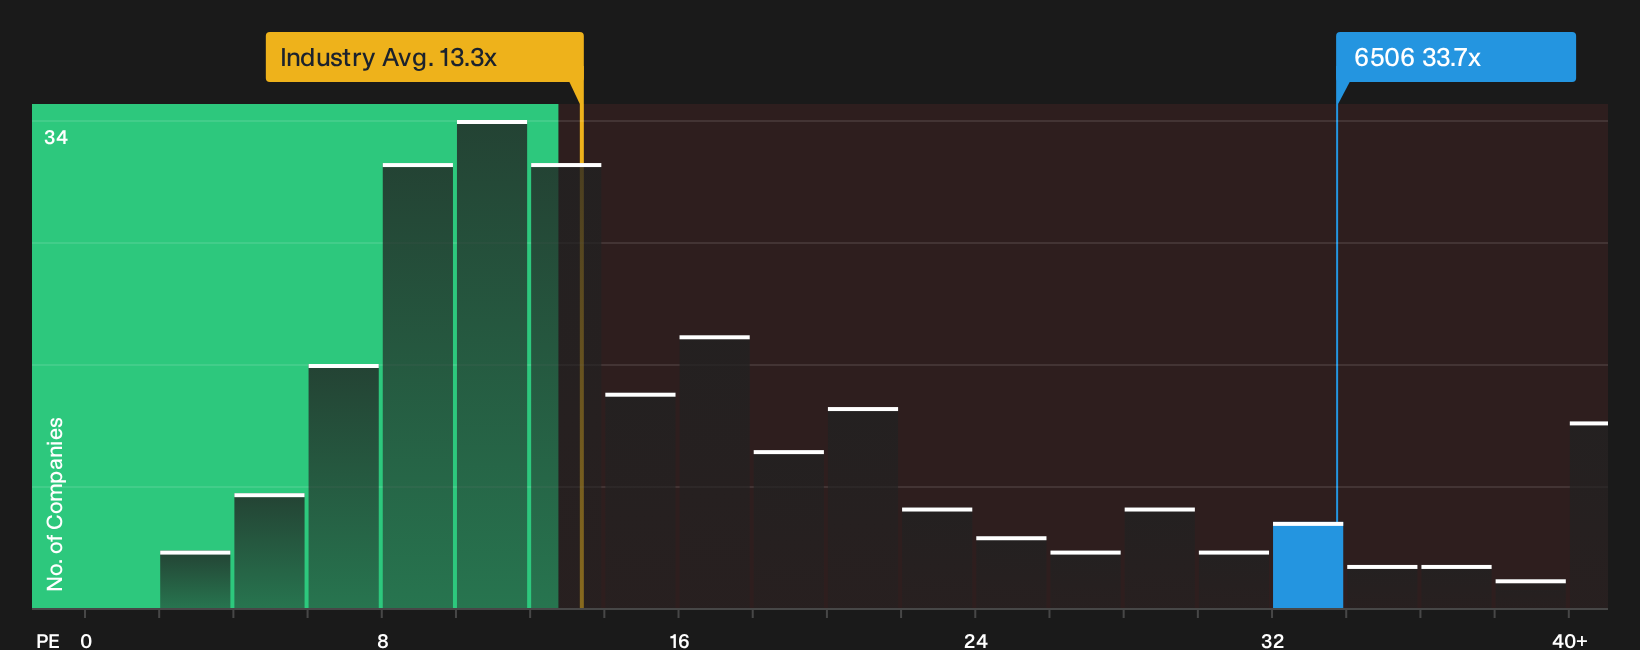
The P/E ratio is a useful lens for YASKAWA Electric because earnings remain a central reference point for how the market values its automation and motion control exposure. On this measure, the stock trades on about 33.7x earnings, which is materially higher than the Machinery industry average of roughly 13.3x.
Compared with the broader peer group, which is closer to 17.8x, YASKAWA Electric also carries a clear premium. The Fair Ratio framework, which blends factors such as growth profile, profitability, sector norms and perceived risk, points to a lower P/E than the market is currently paying, so the shares screen as overvalued on this metric. For anyone weighing up the current price, the key question is whether YASKAWA Electric can deliver an earnings trajectory that justifies paying this kind of multiple rather than something nearer that tailored benchmark. Explore the numbers behind YASKAWA Electric's P/E valuation.
The YASKAWA Electric Narrative: What Would Justify Today's Price?
Narratives for YASKAWA Electric pick up where the valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would have to play out for the stock to be worth materially more or materially less than today’s share price on Simply Wall St’s Community page. Instead of a single output from a P/E or valuation model, Narratives unpack the underlying assumptions so you can watch over time whether those conditions actually hold.
A clear, number-driven Narrative on YASKAWA Electric's valuation gives you a structured way to test whether the current P/E premium lines up with your expectations for its growth, margins and execution. Putting those assumptions on paper makes it easier to adjust your view as new results arrive and the earnings story either tracks that path or drifts away from it.
Share your own Narrative for YASKAWA Electric and set out the assumptions behind your valuation.
One more crucial question for YASKAWA Electric
Price and earnings only tell part of the story for YASKAWA Electric, because the research checks have also flagged areas of concern that could change how you view the whole opportunity. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com