
ASX Insights Featuring JB Hi-Fi And Two More Stocks Priced Below Estimated Value
As the Australian Securities Exchange (ASX) opens with a modestly positive outlook, investors remain cautious amid potential interest rate hikes and key economic data releases. In this environment, identifying undervalued stocks can be crucial for those seeking opportunities that may offer growth potential despite broader market uncertainties.
Top 5 Undervalued Stocks Based On Cash Flows In Australia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woodside Energy Group (ASX:WDS) | A$31.13 | A$39.77 | 21.7% |
| Regis Resources (ASX:RRL) | A$7.96 | A$15.33 | 48.1% |
| NobleOak Life (ASX:NOL) | A$1.355 | A$2.03 | 33.3% |
| LaserBond (ASX:LBL) | A$0.565 | A$0.79 | 28.4% |
| JB Hi-Fi (ASX:JBH) | A$67.73 | A$111.07 | 39% |
Let's review some notable picks from our screened stocks.
JB Hi-Fi (ASX:JBH)
Overview: JB Hi-Fi Limited is a retailer of home consumer products with a market capitalization of A$7.41 billion.
Operations: The company's revenue is derived from several segments: E & S contributing A$273.10 million, The Good Guys generating A$2.94 billion, JB Hi-Fi Australia bringing in A$7.42 billion, and JB Hi-Fi New Zealand adding A$430.70 million.
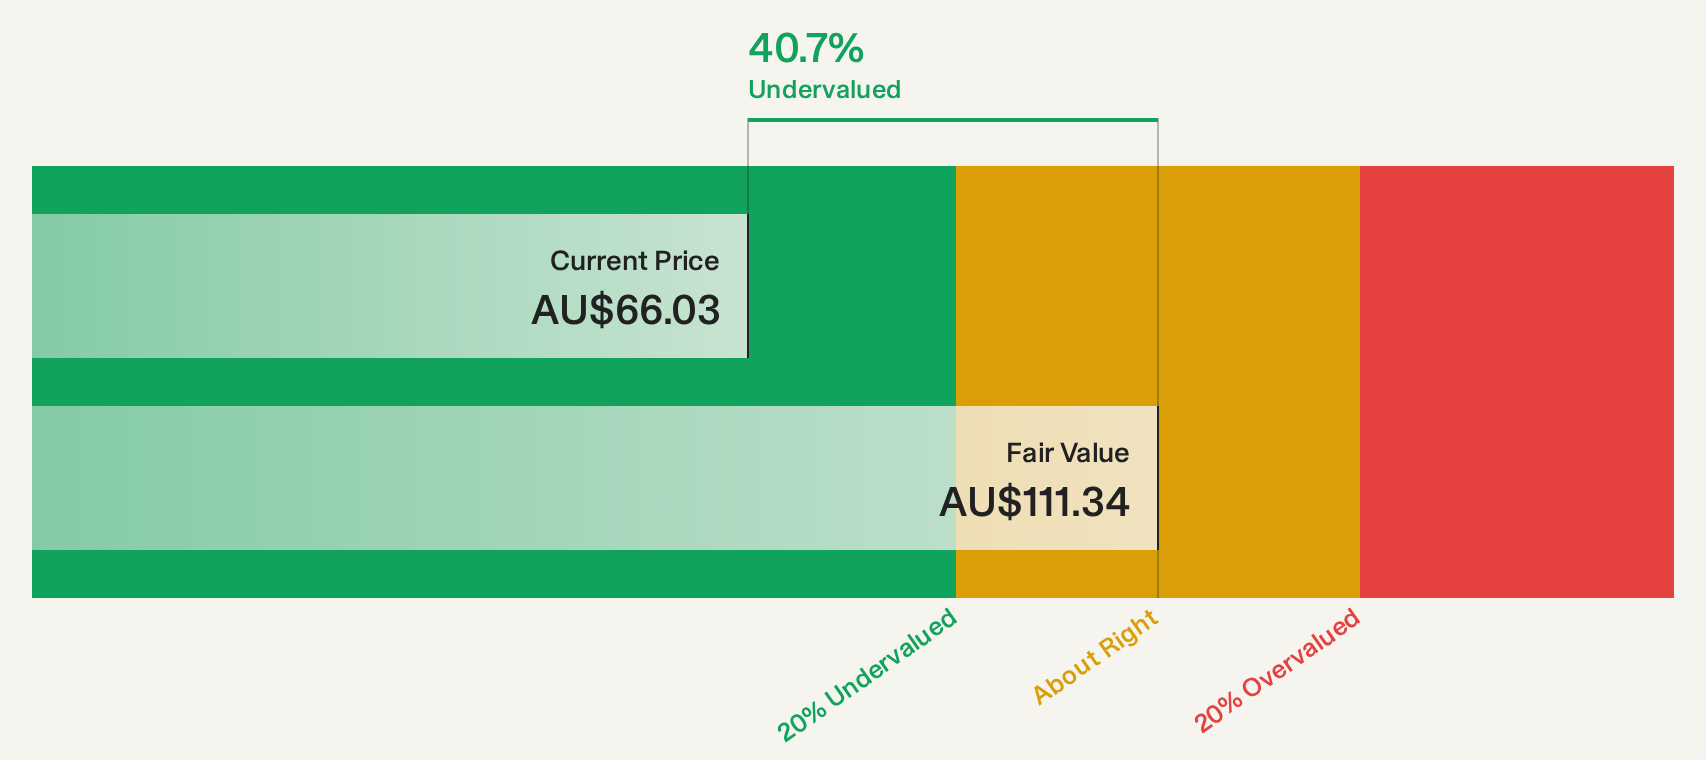
Estimated Discount To Fair Value: 39%
JB Hi-Fi is trading at a significant discount to its estimated future cash flow value, with shares priced at A$67.73 compared to an estimated A$111.07. Despite earnings growth of 5.9% last year and revenue reaching A$11.06 billion, its projected revenue and profit growth lag behind the broader Australian market. Recent board changes include Terry Smart joining as a non-executive director, while dividends remain unstable despite recent increases in payouts.
- Our comprehensive growth report raises the possibility that JB Hi-Fi is poised for substantial financial growth.
- Navigate through the intricacies of JB Hi-Fi with our comprehensive financial health report here.
Regis Resources (ASX:RRL)
Overview: Regis Resources Limited, along with its subsidiaries, focuses on the exploration, evaluation, and development of gold projects in Australia and has a market capitalization of A$6.03 billion.
Operations: The company generates revenue from its gold projects in Australia, with A$1.45 billion coming from Duketon and A$897.02 million from Tropicana.
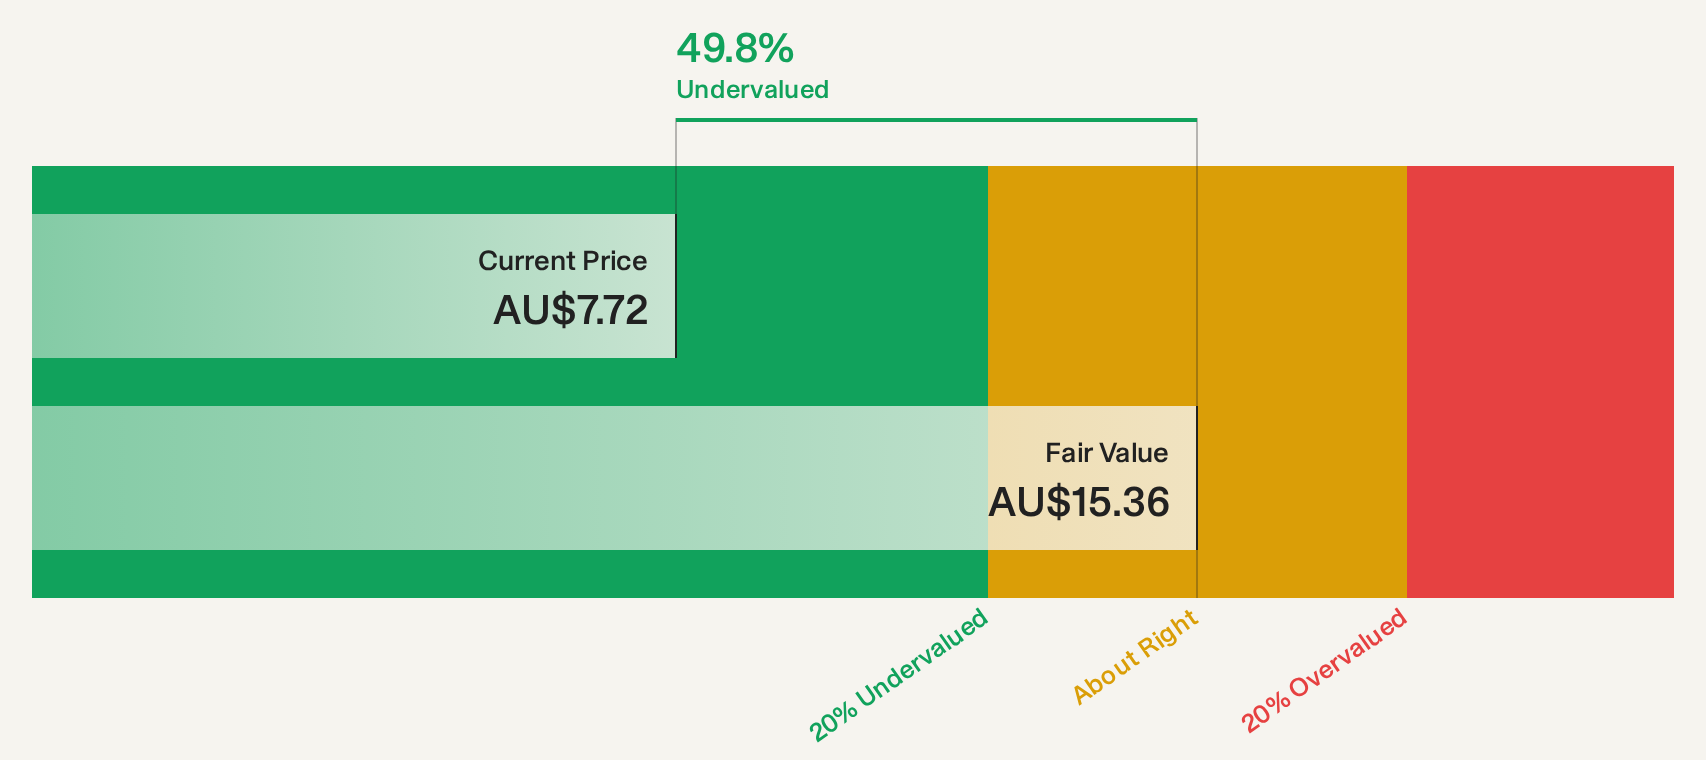
Estimated Discount To Fair Value: 48.1%
Regis Resources is trading at a substantial discount to its estimated future cash flow value, with shares priced at A$7.96 against an estimated A$15.33. Despite earnings growing significantly by 181.1% last year and sales reaching A$2.35 billion, forecasts indicate a decline in revenue and earnings over the next three years. Recent dividends include a regular A$0.15 and special A$0.05 per share, though dividend sustainability remains uncertain due to an unstable track record.
- According our earnings growth report, there's an indication that Regis Resources might be ready to expand.
- Unlock comprehensive insights into our analysis of Regis Resources stock in this financial health report.
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group Ltd is involved in the exploration, development, production, and sale of hydrocarbons across the Asia Pacific, Africa, the Americas, and Europe with a market cap of A$59.18 billion.
Operations: The company's revenue segments include $7.29 billion from Australia, $1.93 billion from Marketing, and $4.62 billion from International operations.
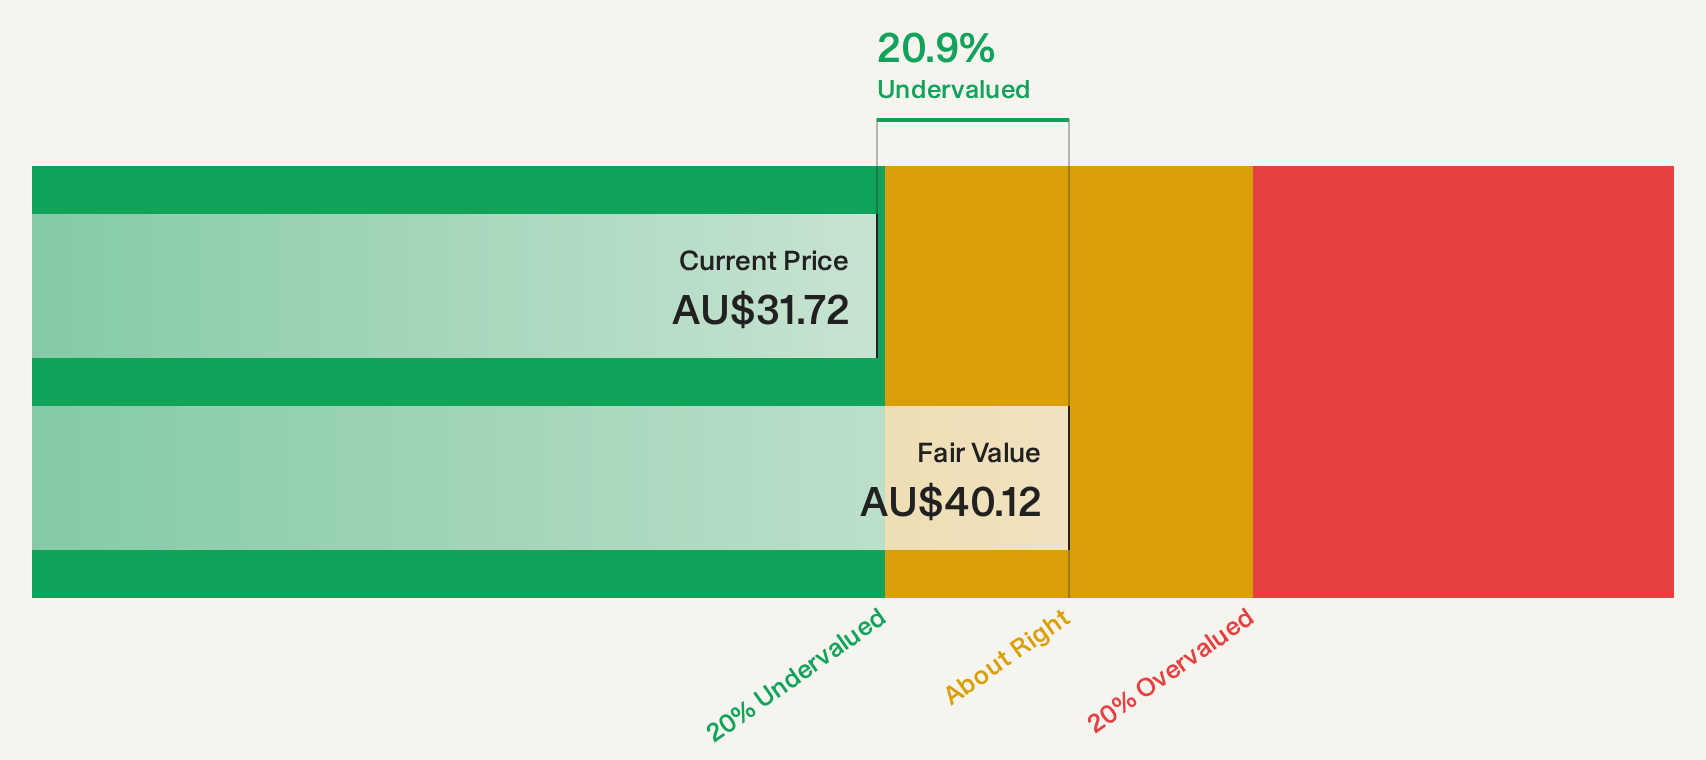
Estimated Discount To Fair Value: 21.7%
Woodside Energy Group is trading at A$31.13, significantly below its estimated future cash flow value of A$39.77, indicating potential undervaluation based on cash flows. Despite recent earnings growth and increased sales to US$7.45 billion for the half-year ending June 2026, forecasts suggest a decline in earnings over the next three years. The company's dividend yield of 5.08% is not well covered by free cash flows, raising sustainability concerns amidst strategic ventures like the Trion Oil Project with PEMEX.
- Insights from our recent growth report point to a promising forecast for Woodside Energy Group's business outlook.
- Click to explore a detailed breakdown of our findings in Woodside Energy Group's balance sheet health report.
Key Takeaways
- Unlock our comprehensive list of 5 Undervalued ASX Stocks Based On Cash Flows by clicking here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com