
Centrus Energy (LEU) Lands Fresh HALEU Deals On A Narrative That Still Looks Undervalued
Centrus Energy (LEU) has just locked in multi-year HALEU supply deals with Antares Nuclear and Radiant, anchored by customer prepayments and focused on advanced reactors and U.S. national security uses.
Centrus Energy’s latest HALEU contracts arrive after a volatile run for the shares, with the stock rallying 1.92% over the past day and 11.05% over the week but still down 42.08% on a year to date share price basis. Long term total shareholder return over five years sits above 3x, pointing to strong earlier gains but fading recent momentum as investors reassess both growth potential and risk around its specialized nuclear role.
Scan beyond Centrus Energy and compare it with other potential nuclear infrastructure beneficiaries using a curated list of 19 nuclear energy infrastructure stocks that may benefit from fuel security and advanced reactor build outs.
Centrus Energy now sits between fresh HALEU contracts and a share price that has already given back a large chunk of past gains. How much of the real upside is still in front of you rather than behind the stock?
Most Popular Narrative: 16.9% Undervalued
The most followed valuation narrative for Centrus Energy pegs fair value at $190 per share against a last close of $157.83, so the gap between story and screen price is already clear. Where that gap might close or widen comes down to how you view HALEU supply, policy support, and the pace of advanced reactor deployment.
High-Assay Low-Enriched Uranium (HALEU) is an advanced nuclear fuel required by many next-gen reactor designs. Compared with the fuel used in most existing commercial reactors, HALEU enables advanced designs to operate more efficiently, supports smaller reactor cores, and potentially allows for longer operating cycles.
See why 39 investors see Centrus Energy as 17% undervalued.
According to CentryResearch, this thesis values Centrus Energy at $190, which implies a 16.9% discount to that estimate at the latest close. The author anchors that figure on HALEU’s constrained supply chain, the firm’s enrichment role, and government backed contracts, with a 7.108% discount rate used to bring those expected cash flows back to today’s dollars.
That narrative leans heavily on Centrus Energy’s positioning as a specialist fuel supplier rather than a broad uranium producer or reactor developer. It frames the business as a potential bottleneck in HALEU, with $473.9m of revenue, $48.5m of net income, and two operating segments that tie together commercial utilities, technical services, and U.S. nuclear programs.
The same storyline also flags clear risks for investors to weigh. Earnings growth over the past year moved in the wrong direction, profit margins compressed from 24% to 10.2%, and forecast revenue growth of 4% a year trails broader U.S. expectations.
Result: Fair Value of $190 (UNDERVALUED)
Still, the CentryResearch narrative around Centrus Energy can break if government HALEU funding slows or if rival enrichment capacity scales faster than expected.
Find out about the key risks to this Centrus Energy narrative.
Another View: Centrus Energy Looks Pricey On Earnings
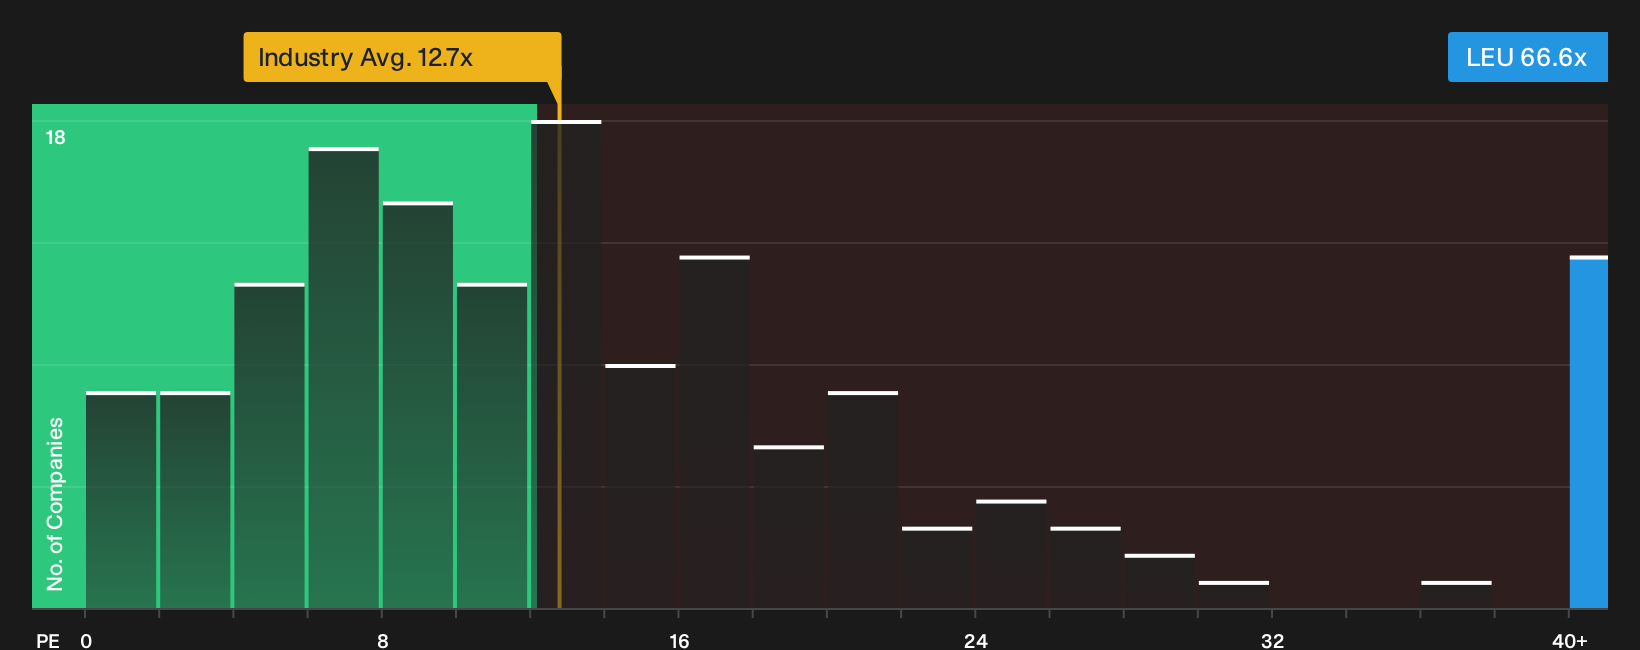
The $190 fair value case for Centrus Energy relies on HALEU bottleneck economics. A simple P/E check tells a very different story. The shares trade on 66.6x earnings compared with 12.7x for the wider US Oil and Gas industry and 22.3x for peers, while the fair ratio stands at just 10.8x. That gap puts a lot of expectation into the current quote. How comfortable are you paying that much upfront for a business with forecast earnings growth of 5.7% a year?
To see how the current valuation compares with what the numbers suggest the market could move toward, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Centrus Energy so far. Check the numbers, weigh the risks against the potential upside, and see whether the story stacks up in your view with 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Centrus Energy?
If Centrus Energy has sharpened your interest in nuclear and infrastructure themes, do not stop here. Broader opportunities often emerge where fewer investors are already looking.
- Tap into potential value by scanning a curated set of underpriced, financially solid opportunities using the 29 high quality undervalued stocks.
- Lock in income-focused ideas by reviewing companies in the 7 dividend fortresses that pair yield with fundamental resilience.
- Spot lesser-known opportunities early by searching through a 16 high quality undiscovered gems before attention and capital move in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com