
TJX Companies (TJX) Extends Its Retail Reach, Is The Stock Cheap Or Pricey?
TJX Companies (TJX) is back in focus after its board elected Craig A. Pintoff to join both the Board of Directors and the Audit and Finance Committee, giving investors a fresh angle on governance quality.
The TJX Companies share price has pulled back sharply over the past quarter, with a 90 day share price return down 20.8% and a year to date share price return down 15.2%. Long term holders still see a 3 year total shareholder return of 54.8% and a 5 year total shareholder return of 100.6%, so recent weakness contrasts with a much stronger multi year record as investors weigh fresh board changes, the affirmed dividend and upbeat commentary around its digital reach and earnings track record.
Surf 16 high quality undiscovered gems picked for off-price resilience and digital reach similar to TJX Companies, so you can compare this pullback story with other under the radar retailers.TJX Companies now trades well below its recent levels after that 20.8% 90 day slide. Does that setback still offer a favorable trade off between risk and reward, or has the pullback already run its course?
Most Popular Narrative: 24% Undervalued
The most followed valuation narrative puts TJX Companies’ fair value at $172.80, which is well above the recent $130.79 close. This frames the recent pullback as a gap between the price and the earnings story analysts are modeling out.
Stronger-than-expected and broad-based growth in customer transactions across all divisions, combined with consistent above-plan comp sales, signals that consumers are increasingly drawn to value-focused retail options in a macro environment marked by economic uncertainty, supporting ongoing revenue growth and market share gains.
See why 61 investors see TJX Companies as 24% undervalued.
Result: Fair Value of $172.80 (UNDERVALUED)
Still, the TJX Companies story can be derailed if customer spending shifts more aggressively online or if brands tighten inventory, which could squeeze off-price sourcing and future margins.
Find out about the key risks to this TJX Companies narrative.
Another View On TJX Companies Valuation
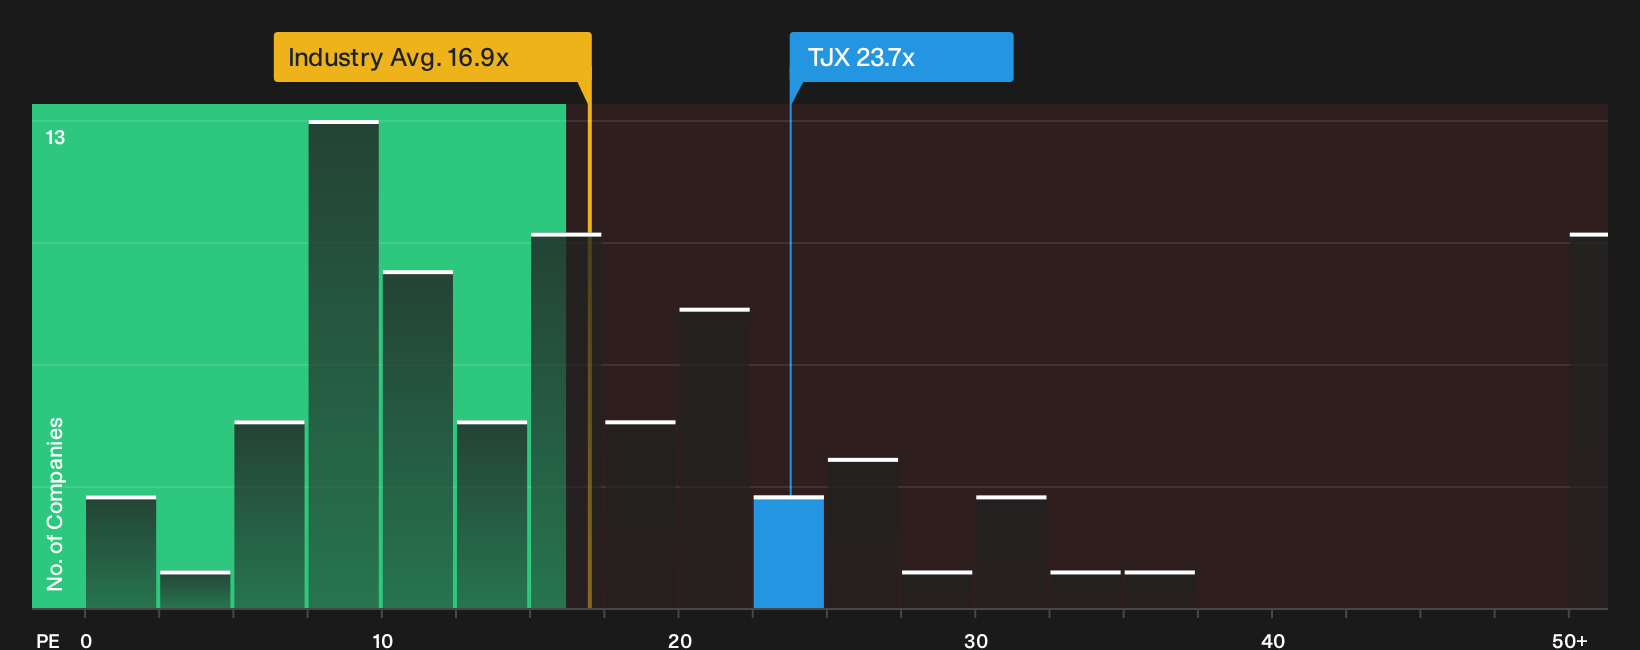
The first fair value story for TJX Companies leans heavily on analyst earnings forecasts and a premium future P/E. A different lens uses the current P/E of 23.7x, which screens as expensive against the US Specialty Retail industry at 16.9x and peers at 17x, and even sits above a 21.3x fair ratio that the market could eventually move toward.
That gap suggests any further rerating would demand very strong execution, because if TJX Companies drifts closer to the fair ratio or peer levels, the share price could face pressure instead of support. Which version of value do you want to lean on when the next set of numbers lands?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on TJX Companies is split, with recent weakness set against a richer long term record, so now is the moment to look through the numbers yourself and weigh both sides carefully. To see how the upside case compares with the downside, watch the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TJX Companies?
If TJX Companies has your attention, do not stop here. Broaden your watchlist with a few focused idea lists that target different risk and income profiles.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (23 results) that may better handle shocks when conditions get choppy.
- Focus on potential mispricing and study the 29 high quality undervalued stocks to see which businesses the numbers suggest could be trading at a discount.
- Build a cash flow focused watchlist and track the 7 dividend fortresses that might help you prioritise income alongside capital returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com