
3 British Undervalued Stocks For September 2026
Global banks are warning that a potential UK windfall tax could redirect capital away from London, which puts more focus on British companies that already generate solid cash and still trade below their estimated worth. When big money turns cautious, patient investors can often find better entry points. This article highlights three undervalued UK-listed stocks where current cash flows hint at more value than the share price implies.
The three ideas that follow are only a small sample of what screens as undervalued on cash flow today. The full Simply Wall St search currently flags 8 more UK stocks with equally interesting stories that are not covered here. To see the wider field, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the cash flow opportunities that best fit your style.
LSL Property Services (LSE:LSL)
LSL Property Services runs a capital light platform across mortgage advice, surveying and valuation, and franchised estate agency. The Surveying & Valuation arm provides the recurring valuation cash flows that tie it closely to this cash flow focused screener. The group generated about £110.7 million from Surveying and Valuation, £48.2 million from Financial Services and £26.7 million from Estate Agency, with a market value of roughly £245 million.
For investors screening for cash flow backed value rather than headline housing stories, LSL Property Services brings a different angle on the UK property cycle and may warrant a closer look through that lens.
"Structural growth in the private rental sector, supported by LSL’s program of lettings book acquisitions for franchisees, is expanding high visibility, recurring income streams that can smooth cyclicality in housing transactions and support group revenue resilience and net margins."
The key question is how this less visible shift in mix ultimately feeds through to pricing power and the durability of those margins.
That margin durability question is exactly what the full narrative for LSL Property Services unpacks. It also examines where recurring cash flows could be masking both upside and execution risk.

AltynGold (LSE:ALTN)
AltynGold is a London headquartered miner that focuses on gold and silver deposits in northeast Kazakhstan, where its 100% owned Sekisovskoye mine and Teren Sai projects generated about $175 million from exploration and development, supporting the group’s roughly £294 million market value.
AltynGold brings the screener theme to life through the Sekisovskoye and Teren Sai assets, which drive the cash flows behind a share price that trades about 45% below an internal fair value estimate and on a P/E of roughly 6.1x. The appeal of that gap rests on how one funding pressure resolves.
That funding overhang is the hinge. For a deeper look, read the analysis report for AltynGold to see how AltynGold’s cash generation and project timeline really line up.
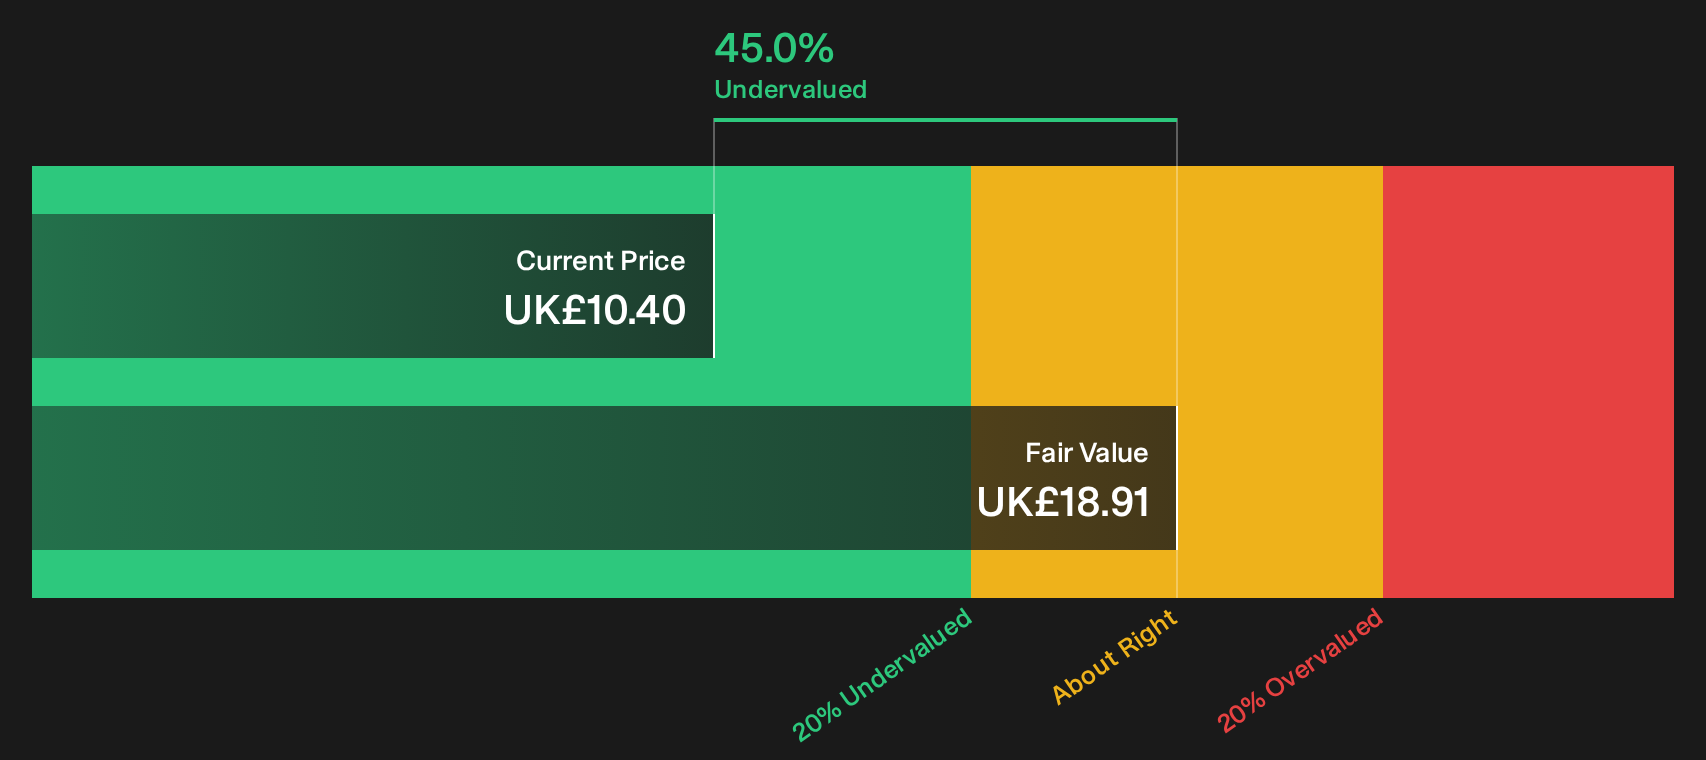
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings manages infrastructure and private equity funds, with its renewable real assets platform squarely aligned with the screener’s cash flow theme. The business generated about £114.8 million from Real Assets and £50.1 million from Private Equity, against a market value near £488.3 million.
For investors drawn to cash flow backed value ideas, Foresight Group Holdings offers a fund manager angle where long term contracts in renewable infrastructure help anchor visibility, while capital allocation choices add another lever that can shift what those cash streams are worth per share.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens to Foresight’s valuation gap if that growth path collides with even a small change in how much fee pressure the market will tolerate?
If that fee tension is what you are weighing, the full narrative for Foresight Group Holdings shows where cash flows could be decoupling from sentiment and explains why buybacks might quietly be accelerating value per share.

Seeking Fresh Alternatives Before Everyone Else
Fresh ideas move first. By the time momentum is flying, the best entry points can be gone. Scan these curated lists while it still matters and get in early.
- Spot shifting trends in digital assets and payments by scanning a curated set of 20 cryptocurrency and blockchain stocks before that story gets fully caught by the wider market.
- Target resilient income while prices are still dropping in and out of favor by running through a focused group of 1 dividend fortresses that aim to keep cash coming in.
- Hunt for early infrastructure momentum around power demand and grid upgrades with a filtered pool of 39 power grid technology and infrastructure stocks that remains under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com