
Should New Power Chip Launches Require Action From Vishay (VSH) Investors?
- Vishay Intertechnology recently announced four new DFN6546A surface mount rectifier series and a 15 part XclampR TVS range aimed at industrial, commercial, and AEC Q101 qualified automotive uses.
- The combination of higher current ratings, flat clamping behavior, and compact low profile packaging points to focused execution on power efficiency and PCB space constraints in core automotive and industrial designs.
- We will now look at how Vishay Intertechnology’s investment narrative could be influenced by these higher current DFN6546A rectifiers.
Scan other power efficiency and automotive electronics plays moving on similar themes to Vishay Intertechnology with our hand picked 39 power grid technology and infrastructure stocks
Vishay Intertechnology Investment Narrative Recap
To hold Vishay Intertechnology, you need to believe the heavy spending on capacity and new products eventually supports stronger margins and steadier free cash flow. The recent DFN6546A rectifiers and XclampR TVS lines fit that story by targeting higher value automotive and industrial sockets, although by themselves they look incremental rather than a clear near term inflection.
The more immediate swing factor remains how quickly utilization and profitability recover from recent low GAAP operating margins and negative free cash flow guidance. The biggest near term risk is that demand for discrete semiconductors and passives stays soft, which would leave Vishay Intertechnology carrying high capital intensity without a clean earnings payoff.
The DFN6546A rectifier launch looks most relevant for the near term narrative. These devices target rail to rail and polarity protection in industrial and AEC Q101 automotive designs, with higher current ratings in a smaller, lower profile footprint. That aligns cleanly with the push into higher content per vehicle and more electronics in factory and energy systems.
Operationally, the key question is execution. Design wins using these rectifiers could support utilization of new capacity and strengthen Vishay Intertechnology’s position in automotive and industrial power, which analysts already see as important growth areas. If uptake disappoints, the firm is still left with the same capital intensity and margin pressure, only with a broader catalog.
Vishay Intertechnology's narrative projects US$5.0b revenue and US$640.7 million earnings by 2029. This implies 14.6% yearly revenue growth and an earnings increase of about US$612 million from US$28.4 million today.
Uncover why Vishay Intertechnology's fair value indicates a 21% potential upside to its current price, a valuation gap that could narrow more quickly than investors expect.
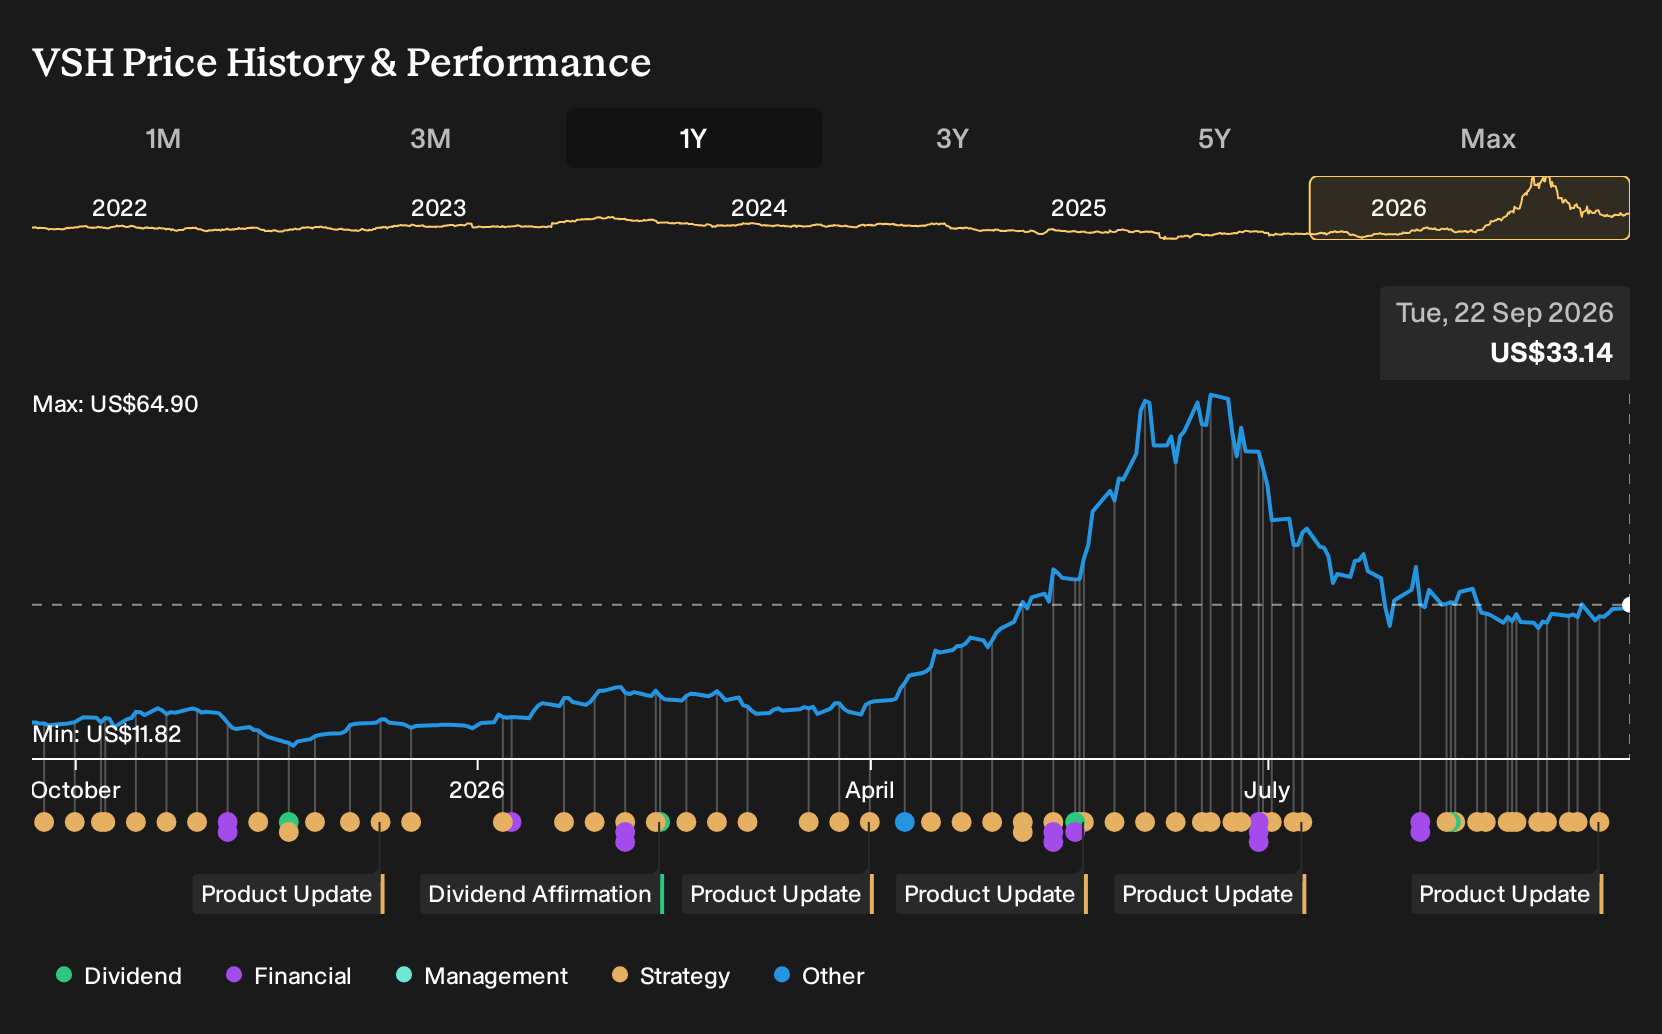
Exploring Other Perspectives
One alternate angle to watch is margin pressure. The more pessimistic analysts already had Vishay Intertechnology only reaching about US$5.2b of revenue and US$500.4 million of earnings by 2029, with a lower 9.6% margin assumption. Those forecasts came before this rectifier and XclampR news, so you should expect opinions could shift and consider both narratives.
Explore 2 other Vishay Intertechnology fair value estimates, including one that suggests it could be worth just $40.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vishay Intertechnology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vishay Intertechnology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vishay Intertechnology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vishay Intertechnology?
Once you have formed a view on Vishay Intertechnology, it can help to widen the lens and compare it with other listed businesses that share some of the qualities you care about most.
- If you want to focus on potential value combined with fundamentals, take a look at our hand picked 29 high quality undervalued stocks that might warrant a closer review.
- For investors who care most about balance sheet strength and financial resilience, start with this curated list of solid balance sheet and fundamentals (23 results) to see which companies line up with that preference.
- If you prefer to hunt for lesser known opportunities with strong metrics, you can scan our targeted 16 high quality undiscovered gems and build your own watchlist from there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com