
SoundHound AI (SOUN) Pushes Into Banking After LivePerson Deal But Is The Valuation Too Rich
SoundHound AI (SOUN) is back in focus after pushing deeper into banking and insurance, securing new contracts while closing the LivePerson deal to build multi channel AI agents for tightly regulated enterprise clients.
Recent contracts in banking and insurance, along with the LivePerson acquisition, come after a difficult period for SoundHound AI’s shareholders. The share price is down 16.4% over the past month and the year-to-date share price return has declined 42.3%.
Scan beyond SoundHound AI and see which hand picked AI infrastructure plays are showing real traction with 85 AI infrastructure stocks in the current market.
SoundHound AI now offers a broader product toolkit and has expanded its reach into regulated clients, yet the share price has retreated sharply. Is this a strong platform temporarily out of favor, or one that is already fully valued?
Most Popular Narrative: 64% Undervalued
On the most widely followed view, SoundHound AI’s fair value sits at $17 against a last close of $6.12. This frames a sharp disconnect that hinges on how far its voice agents can scale into real world deployments.
Amid the broad proliferation of AI voice-enabled devices spanning automotive, enterprise, and consumer markets, SoundHound is positioned to capture outsized upside as the only independent, high-performing multilingual voice AI provider. This is expected to lead to accelerating international demand, long-term revenue compounding, and superior operating leverage as speech interfaces become essential in everyday life.
See why 22 investors see SoundHound AI as 64% undervalued.
Result: Fair Value of $17 (UNDERVALUED)
Still, the bullish SoundHound AI story can crack if rising losses force fresh equity raises that dilute holders, or if larger tech rivals pressure pricing and margins.
Find out about the key risks to this SoundHound AI narrative.
Another View: Multiples Paint A Tougher Picture For SoundHound AI
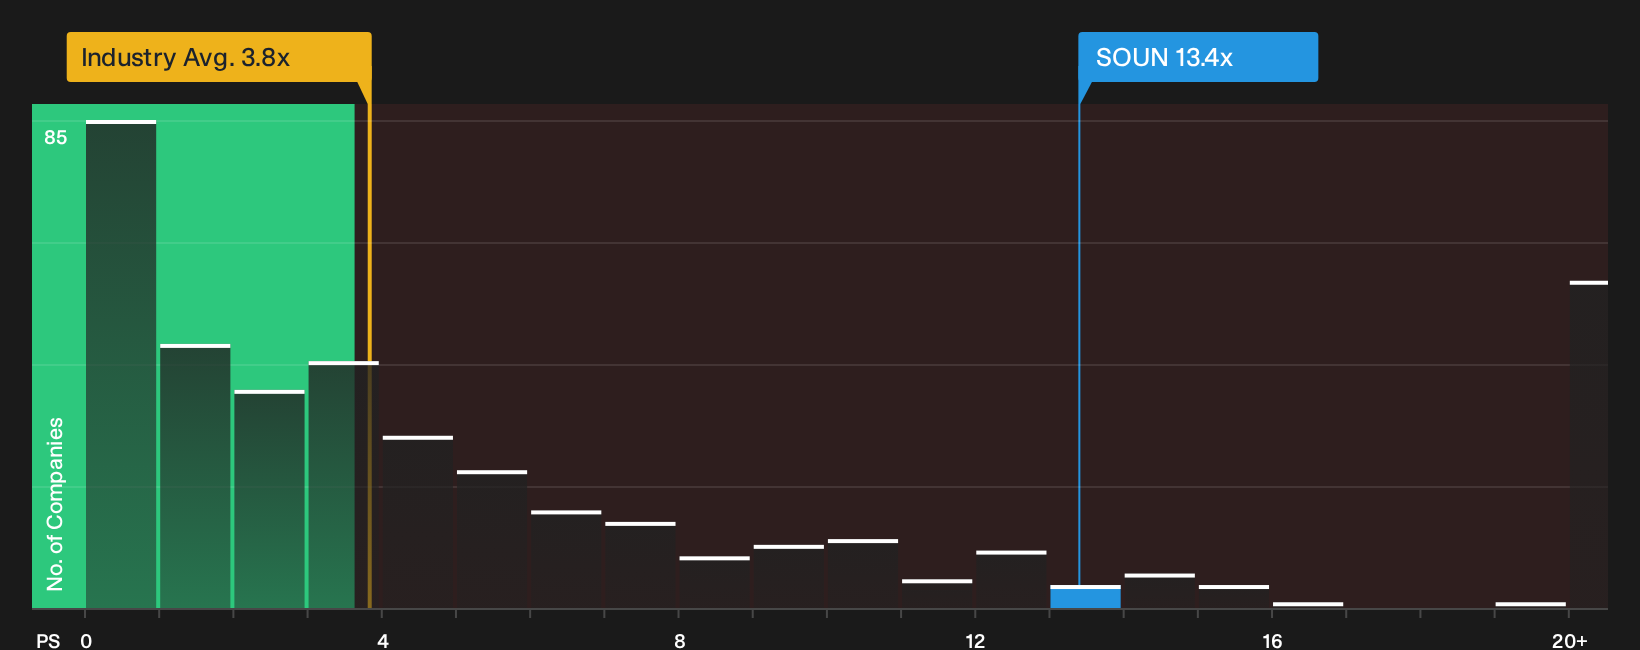
There is a sharp contrast between the bullish fair value narrative for SoundHound AI and what its current sales multiple implies. The stock trades on a P/S of 13.4x, compared with 3.8x for the wider US Software industry and 7.2x for its peer group, while the fair ratio sits at 4.3x.
In practical terms, that means the market is already assigning SoundHound AI a very rich revenue tag relative to both sector norms and the level our fair ratio suggests it could move toward over time. If the business underdelivers against the optimistic growth story, how much multiple risk are you really comfortable carrying?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on SoundHound AI after all this. If you want to move fast and base your stance on data, start with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond SoundHound AI?
If SoundHound AI has sharpened your thinking, do not stop here. Put that momentum to work by scanning other opportunities that match your style and risk tolerance.
- Target resilient compounding potential by focusing on financially strong businesses in our list of solid balance sheet and fundamentals (23 results) so weaker balance sheets do not drag your portfolio down.
- Pursue mispriced opportunities by zeroing in on companies our models flag as attractively priced through the 29 high quality undervalued stocks, before the crowd pays attention.
- Strengthen your income stream by finding dependable high yielders using the 7 dividend fortresses and avoid leaving potential cash returns on the table.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com