
Is Tennant (TNC) Below Fair Value On Weakening Sales And Returns?
Tennant (TNC) is back in focus after management prepared to speak at the Sidoti Small-Cap Virtual Conference on September 23, 2026, as investors weigh earlier commentary about pressure on sales, earnings per share, and returns on capital.
Tennant’s shares have retreated sharply over the past quarter, with a 90 day share price return of down 24.8% and a 1 year total shareholder return of down 16.9%, signalling fading momentum as investors react to concerns around sales, earnings and returns on capital.
Contrast Tennant’s current headwinds with those of other industrials by scanning a hand picked group of list of solid balance sheet and fundamentals (23 results) that may offer a different quality and risk profile.
That recent slide leaves Tennant caught between a bullish story about a cheaper, misunderstood industrial and a bearish read on structurally weaker returns. Which side do the numbers lean toward once valuation enters the frame?
Most Popular Narrative: 24% Undervalued
Tennant’s most followed narrative points to a fair value of $87.75 per share, above the last close at $66.72, which frames the recent pullback as a valuation gap rather than just a vote of no confidence.
Accelerated adoption of autonomous mobile robots (AMRs) and equipment-as-a-service programs is expanding Tennant's recurring revenue base, supported by robust customer demand amid labor shortages and higher labor costs, which are likely to drive both future revenue growth and margin expansion.
Heightened focus on hygiene and cleanliness standards in facilities globally, especially post-pandemic, is enlarging Tennant's addressable market and supporting stronger order pipelines. This trend may translate into steady sales growth over time.
See why 13 investors see Tennant as 24% undervalued.
Result: Fair Value of $87.75 (UNDERVALUED)
Still, that upside story can unravel quickly if international weakness in regions like APAC and EMEA deepens, or if pricing power fades against low cost competitors.
Find out about the key risks to this Tennant narrative.
Another View On Tennant’s Valuation
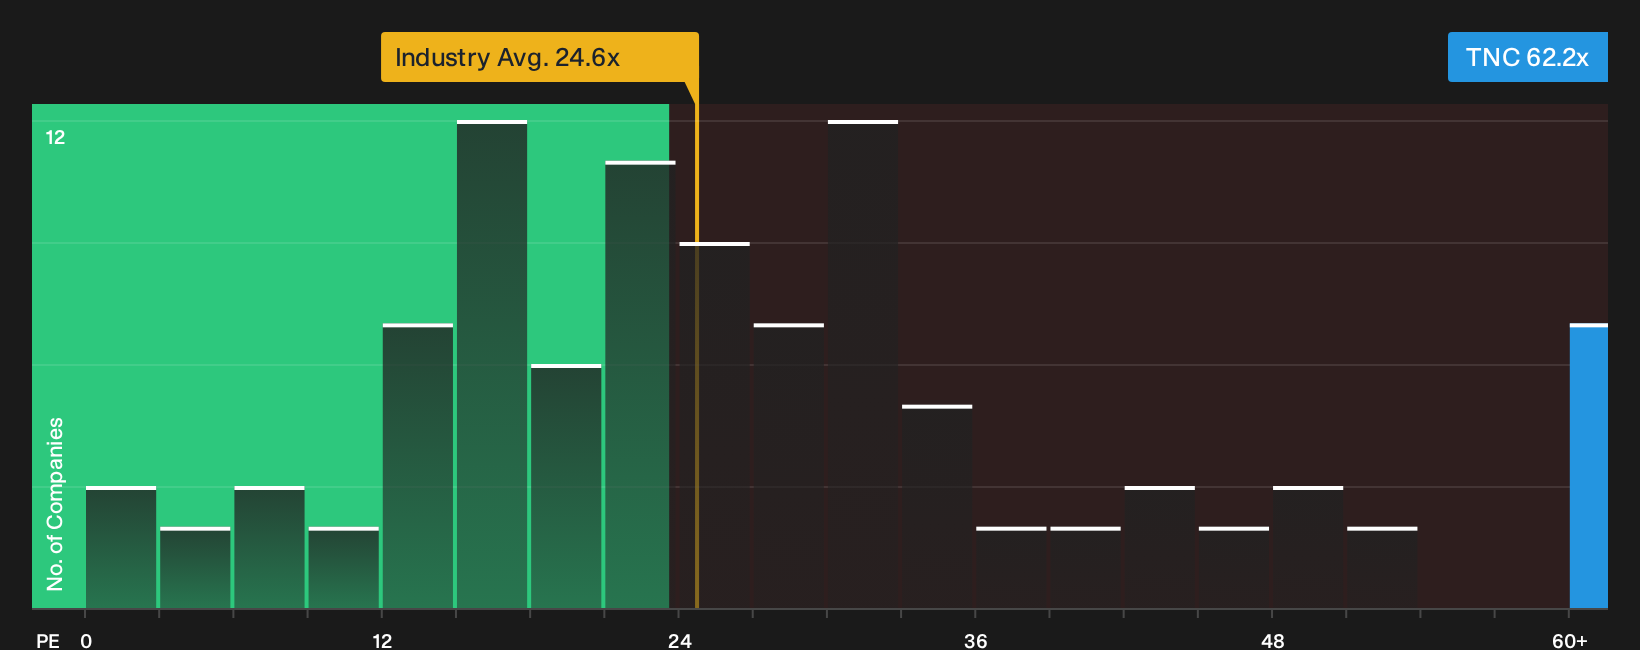
The story changes once the P/E is put under the microscope. Tennant trades on 62.2x earnings, while the US Machinery industry sits at 24.3x and close peers average 42.9x. Even against a fair ratio of 53x, the stock screens expensive. Is the premium a cushion or a crack in the bullish case?
To see how this pricing gap could close in either direction, and what it implies for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about what Tennant’s recent slide really signals? Act while sentiment is in flux and weigh both sides of the story by reviewing 3 key rewards and 4 important warning signs.
Looking for more Tennant sized investment ideas?
If Tennant has you rethinking where your money works hardest, do not stop here. Use the Simply Wall Street Screener to surface focused, data driven ideas across the market before the crowd catches up.
- Target underappreciated quality by scanning a curated set of 16 high quality undiscovered gems that combine strong fundamentals with limited attention from broader investors.
- Prioritize capital resilience and sleep better at night by filtering for 30 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- Zero in on resilient cash generators by reviewing a 7 dividend fortresses that couples high yields with a focus on sustainability and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com