
Asian Growth Stocks With Strong Insider Backing
As Asian markets navigate a landscape marked by fluctuating oil prices and evolving geopolitical tensions, investors are increasingly focused on identifying growth opportunities with robust backing. In this context, companies with high insider ownership can offer compelling prospects, as such alignment often signals confidence in the business's potential amidst current economic uncertainties.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
Here's a peek at a few of the choices from the screener.
TES (KOSDAQ:A095610)
Simply Wall St Growth Rating: ★★★★★★
Overview: TES Co., Ltd. is a company engaged in the manufacturing and sale of semiconductors, displays, and compound semiconductor equipment with a market cap of ₩2.98 trillion.
Operations: TES Co., Ltd. generates revenue primarily from its semiconductor manufacturing equipment segment, which accounts for approximately ₩405.47 billion.
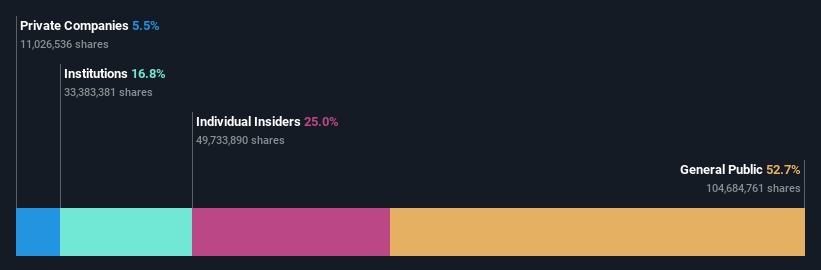
Insider Ownership: 31%
Earnings Growth Forecast: 30.6% p.a.
TES Co., Ltd demonstrates robust growth potential with earnings forecasted to increase by 30.6% annually, outpacing the Korean market's 28.2%. Despite recent volatility in its share price, TES shows significant revenue growth expectations of 21.3%, surpassing the market average of 14.5%. The company's recent earnings report highlights a substantial rise in net income to KRW 34 billion for Q2, reflecting strong financial performance despite negligible sales figures.
- Take a closer look at TES' potential here in our earnings growth report.
- Insights from our recent valuation report point to the potential overvaluation of TES shares in the market.

Shanghai Beite Technology group (SHSE:603009)
Simply Wall St Growth Rating: ★★★★★★
Overview: Shanghai Beite Technology Group Co., Ltd. operates in the technology sector and has a market capitalization of approximately CN¥16.68 billion.
Operations: Revenue segments for this company are not provided in the given text.
Insider Ownership: 38.9%
Earnings Growth Forecast: 29.1% p.a.
Shanghai Beite Technology group shows promising growth prospects with earnings projected to rise significantly at 29.1% annually, surpassing the Chinese market's average growth rate. Its revenue is also expected to grow faster than 20% per year. The recent earnings report for H1 2026 revealed an increase in net income to CNY 63.13 million from CNY 55 million a year ago, despite high share price volatility over the past three months and no substantial insider trading activity reported recently.
- Delve into the full analysis future growth report here for a deeper understanding of Shanghai Beite Technology group.
- According our valuation report, there's an indication that Shanghai Beite Technology group's share price might be on the expensive side.
PharmaBlock Sciences (Nanjing) (SZSE:300725)
Simply Wall St Growth Rating: ★★★★★☆
Overview: PharmaBlock Sciences (Nanjing), Inc. offers chemistry products and services for pharmaceutical research, development, and commercial manufacturing both in China and internationally, with a market cap of CN¥12.66 billion.
Operations: PharmaBlock Sciences (Nanjing) generates revenue primarily from its drug research and development and production-related business, amounting to CN¥2.11 billion.
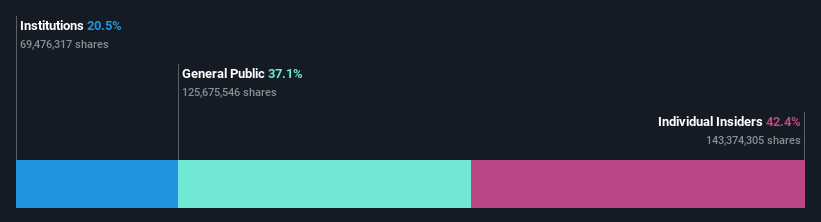
Insider Ownership: 20.8%
Earnings Growth Forecast: 30.3% p.a.
PharmaBlock Sciences (Nanjing) demonstrates solid growth potential with earnings forecasted to increase significantly at 30.3% per year, outpacing the Chinese market average. Revenue is also expected to grow faster than 20% annually. Despite a highly volatile share price recently and no substantial insider trading activity, the company reported an increase in net income for H1 2026 to CNY 99.44 million from CNY 72.5 million a year ago, alongside a modest dividend distribution proposal.
- Click here to discover the nuances of PharmaBlock Sciences (Nanjing) with our detailed analytical future growth report.
- Our valuation report unveils the possibility PharmaBlock Sciences (Nanjing)'s shares may be trading at a premium.
Where To Now?
- Unlock our comprehensive list of 493 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Interested In Other Possibilities? Explore 25 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com